


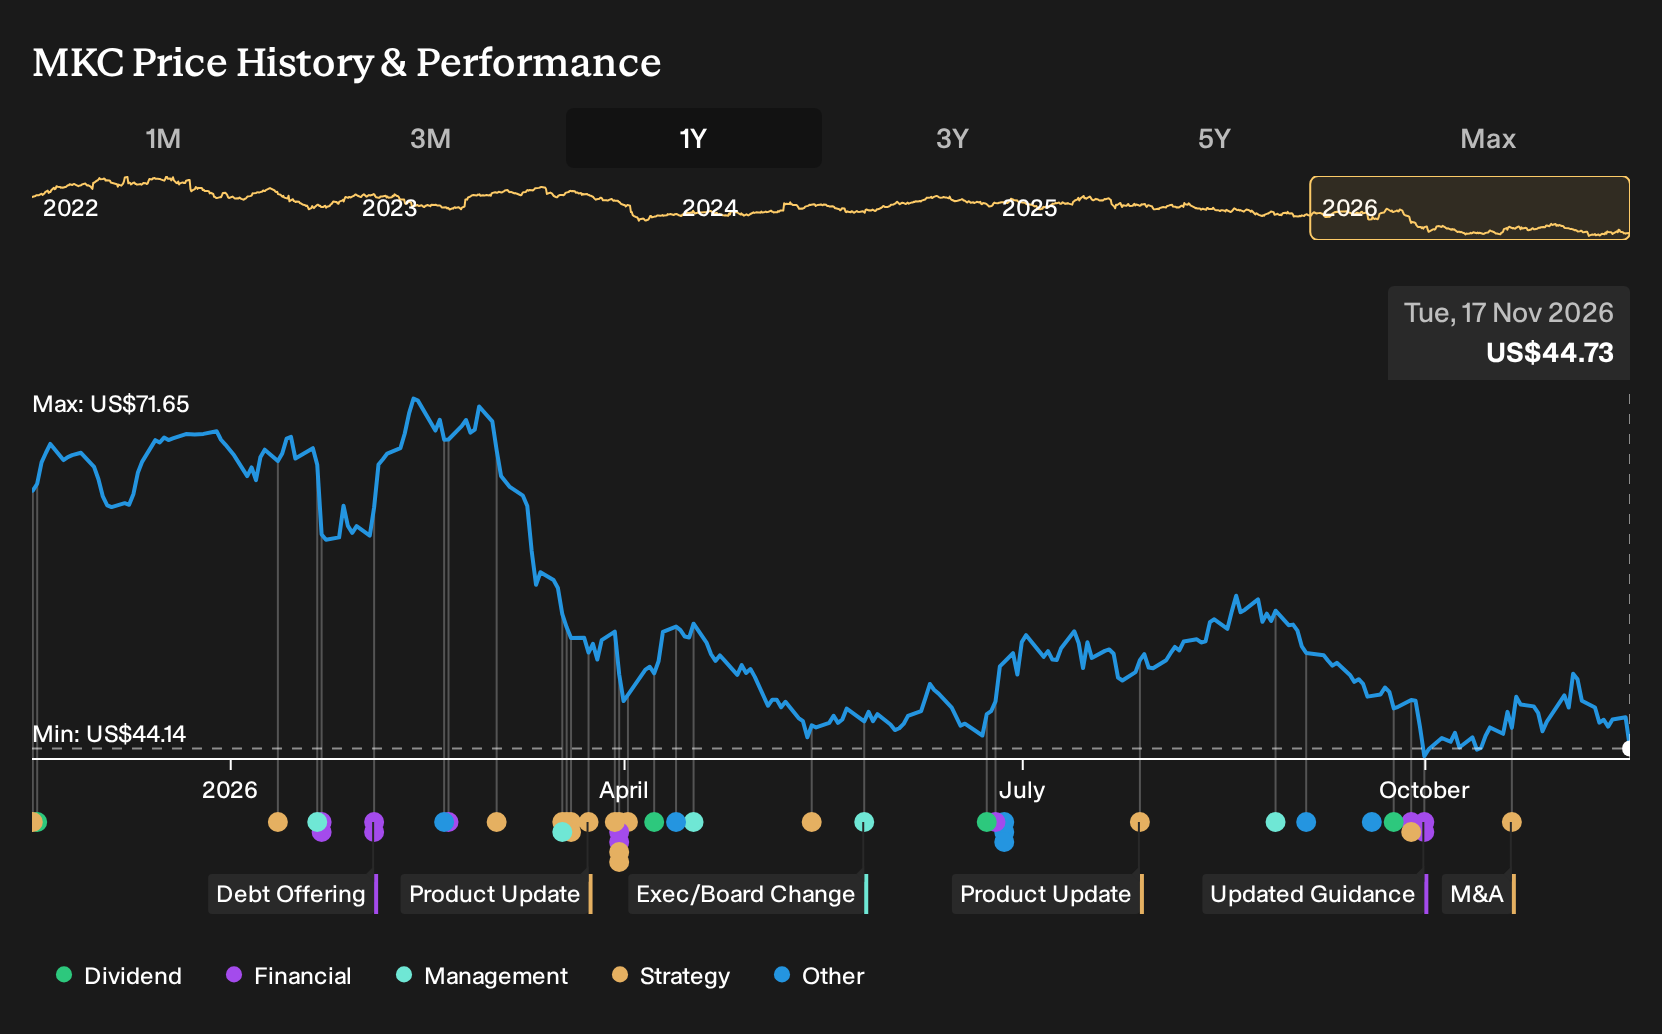
- McCormick & Company increased its quarterly dividend from US$0.48 to US$0.51 per share, payable on January 11, 2027. This marks 103 years of uninterrupted dividends and 41 consecutive years of dividend raises.
- This long record of dividend growth highlights how McCormick has prioritized consistent cash returns to shareholders, alongside its broader flavor platform expansion and integration plans.
- We will now examine how McCormick's latest dividend increase shapes the investment narrative around execution, cash generation and long term resilience.
Scan beyond McCormick and compare this long dividend track record with other income focused opportunities on our hand picked list of 7 dividend fortresses
McCormick Investment Narrative Recap
Owning McCormick means buying into a long term flavor platform that can keep earning returns from spices, sauces and seasoning for both households and food producers. To stay comfortable as a shareholder, you need confidence that Consumer Americas volume pressure and private label competition can be managed while Flavor Solutions keeps contributing to earnings and cash flow.
The dividend raise itself does not change the near term story. The more immediate swing factor remains execution on the planned Unilever Foods tie up and delivery of the targeted US$600m cost synergies. The key risks relate to regulatory outcomes, integration complexity and any further softness in U.S. spices and seasonings.
The analyst consensus narrative on Simply Wall St points heavily to the Unilever Foods acquisition as the key operational turning point, with margin ambitions of 23% to 25% by year three on the combined business. The latest dividend increase aligns with the message that management expects enough cash generation to support both integration work and ongoing shareholder distributions.
Dividend growth also interacts directly with McCormick's use of debt and its goal for stronger free cash flow. Higher regular payouts can tighten room for error if earnings track closer to the forecast decline of 23.9% per year over the next 3 years. For you as an investor, the real test is whether post deal productivity and Consumer volume trends can comfortably fund that rising dividend commitment.
McCormick's current analyst storyline points to revenues of US$8.9b and earnings of US$699.2m by 2029, built on a projected 5.1% annual revenue growth rate. That profit figure compares with about US$1.5b of earnings today, implying an earnings decline of roughly US$800m over the period rather than an increase.
Uncover why McCormick's fair value indicates a 23% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One angle you might explore is the bearish focus on packaging and supply bottlenecks. The lowest analysts were already penciling in revenue of about US$8.6b and earnings near US$710.7m by 2029 before this McCormick dividend news. That cohort reads the story far more cautiously, so this fresh payout move could prompt some of them to revisit those assumptions.
Explore 5 other McCormick fair value estimates, including one that suggests it could be worth just $47.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your McCormick research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for McCormick. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate McCormick's overall financial health at a glance.
Looking For More Investment Ideas Beyond McCormick?
If you want to pressure test your view on McCormick against a wider field of opportunities, using a focused screener can help you quickly zero in on companies that better match your risk tolerance, income needs, or balance sheet preferences.
- For investors who want income paired with resilience, consider screening for companies described as 29 resilient stocks with low risk scores.
- If you care most about financial strength and cleaner balance sheets, run a filter built around our list of solid balance sheet and fundamentals (24 results).
- When you are hunting for potential future leaders that are not widely followed, start with the 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com