


The National Retail Federation expects U.S. holiday sales to rise 4.2% to about $1.01 trillion in November and December 2026. But higher prices, rather than more purchases, are expected to drive roughly half of that increase.
Walmart (WMT) is looking to win over shoppers with three holiday shopping events running from Nov. 12 through Dec. 2. However, investors have another date to watch: Nov. 19, when the company's third-quarter results will arrive before the market opens.
Walmart heads into the report after Q2 revenue reached $187.9 billion, up 5.9% from a year earlier, while global e-commerce sales grew 23%. Tariff refunds also helped profits during the quarter. Can the Q3 results on Nov. 19 show that Walmart can keep growing profits without the extra help? Let’s take a closer look.
Key Metrics to Watch This Quarter
Walmart sells groceries and everyday goods in stores, online, and through its Sam’s Club membership business. Shares have risen 24% over the past 52 weeks and more than 14% on a year-to-date (YTD) basis.
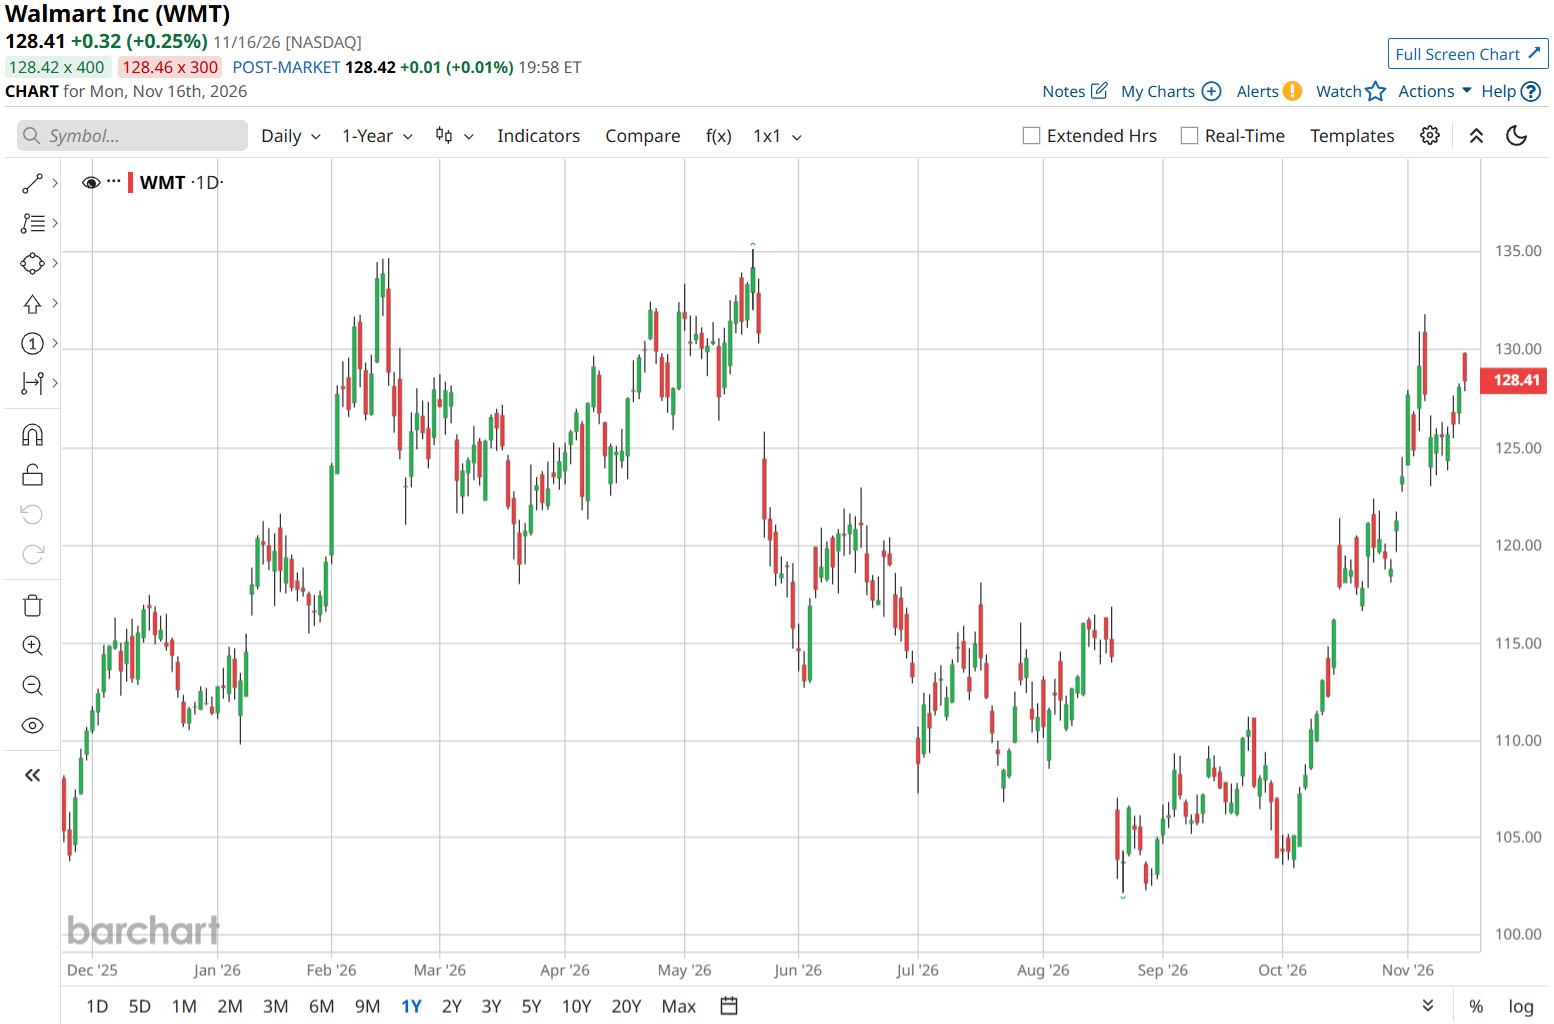
But WMT stock isn’t cheap. Its forward price-to-earnings (P/E) ratio is 44.5 times, compared with the sector average of about 16 times.
The dividend offers a smaller return but a long record of increases. Walmart has raised its payout for 53-straight years. Its latest quarterly dividend was about $0.248 per share, paid on Sept. 8 to shareholders of record on Aug. 21, with an annual yield of about 0.77%. The forward payout ratio of 34.05% suggests room for further increases, although that depends on earnings and spending needs.
Results for Q2 showed growth across several businesses. Revenue rose 5.9% to $187.9 billion, or 5.1% excluding currency changes. Net sales increased 5.9% to $186.1 billion, while membership and other income grew 11.2% to $1.84 billion. E-commerce sales climbed 23%, advertising revenue increased 38%, and global membership-fee revenue rose 17%.
Profits need a closer look. Operating income grew almost 29% year-over-year (YOY) to $9.38 billion, with adjusted growth of 17.4% excluding currency changes. Tariff refunds helped push gross margin to 25.4%, so not all of that improvement came from day-to-day operations. Net income fell 9.4% to $6.37 billion, while GAAP EPS dropped 9.1% to $0.80. Adjusted EPS, which excluded a $0.12-per-share investment loss and a $0.11-per-share tax benefit, rose to $0.81.
All three segments grew. Walmart’s U.S. sales rose 3.5% to $125.2 billion, while operating income increased 20.6% to $8.1 billion. International sales grew 12.8% to $35.2 billion, and operating income rose 16.6% to $1.4 billion. Excluding currency changes, those increases were 7.9% and 5.7%, respectively. Sam’s Club sales climbed 8.8% to $25.7 billion, while operating income rose 44.3% to $700 million, or 23.3% on an adjusted basis. Inventory increased 6.7% to $61.6 billion, slightly faster than revenue. Return on assets stood at 8%, while return on investment was 15.4%.
The Businesses Driving Walmart’s Growth
In October, Walmart invested in Texas-based Base Power and agreed to offer its home-energy services to Walmart customers and Sam’s Club members. Base Power’s batteries are designed to “lower energy costs when the grid is on and provide backup power when it’s not.”
Walmart also recently expanded its agreement with Symbotic (SYM) to add artificial intelligence (AI)-powered automation at 25 U.S. regional distribution centers. The agreement includes an initial multiyear spending commitment of about $6 billion, with opportunities to expand across Walmart’s global supply chain.
Finally, in healthcare, Walmart is expanding Better Care Services with an online store powered by General Medicine, bringing services from several third-party providers into one catalog and making it easier to compare care options, choose providers, and check costs with and without insurance. General Medicine provides the catalog, while Walmart brings its customer reach and existing services.
Analyst Expectations Set the Earnings Bar
Walmart will report earnings before the market opens on Nov. 19. Analysts expect earnings of $0.64 per share for the October quarter, up 3% from $0.62 a year earlier. For fiscal 2027, analysts expect EPS of $2.88, a 9% YOY increase from $2.64.
Deutsche Bank turned more positive on WMT stock on Oct. 15, upgrading Walmart from “Hold” to “Buy” and raising its price target from $113 to $136. Shares rose by more than 1% following the upgrade. Deutsche Bank pointed to management’s comments about inflation making low prices more appealing and helping Walmart gain grocery market share. The bank also noted that higher-margin advertising, marketplace merchant services, and memberships were growing faster than the core retail business.
Argus Research analyst Christopher Graja kept a “Buy” rating after the Q2 earnings report but lowered his target from $145 to $130. Graja praised Walmart’s low prices for attracting and retaining shoppers, but flagged slowing comparable-sales growth and the strain that higher gasoline prices have put on household budgets.
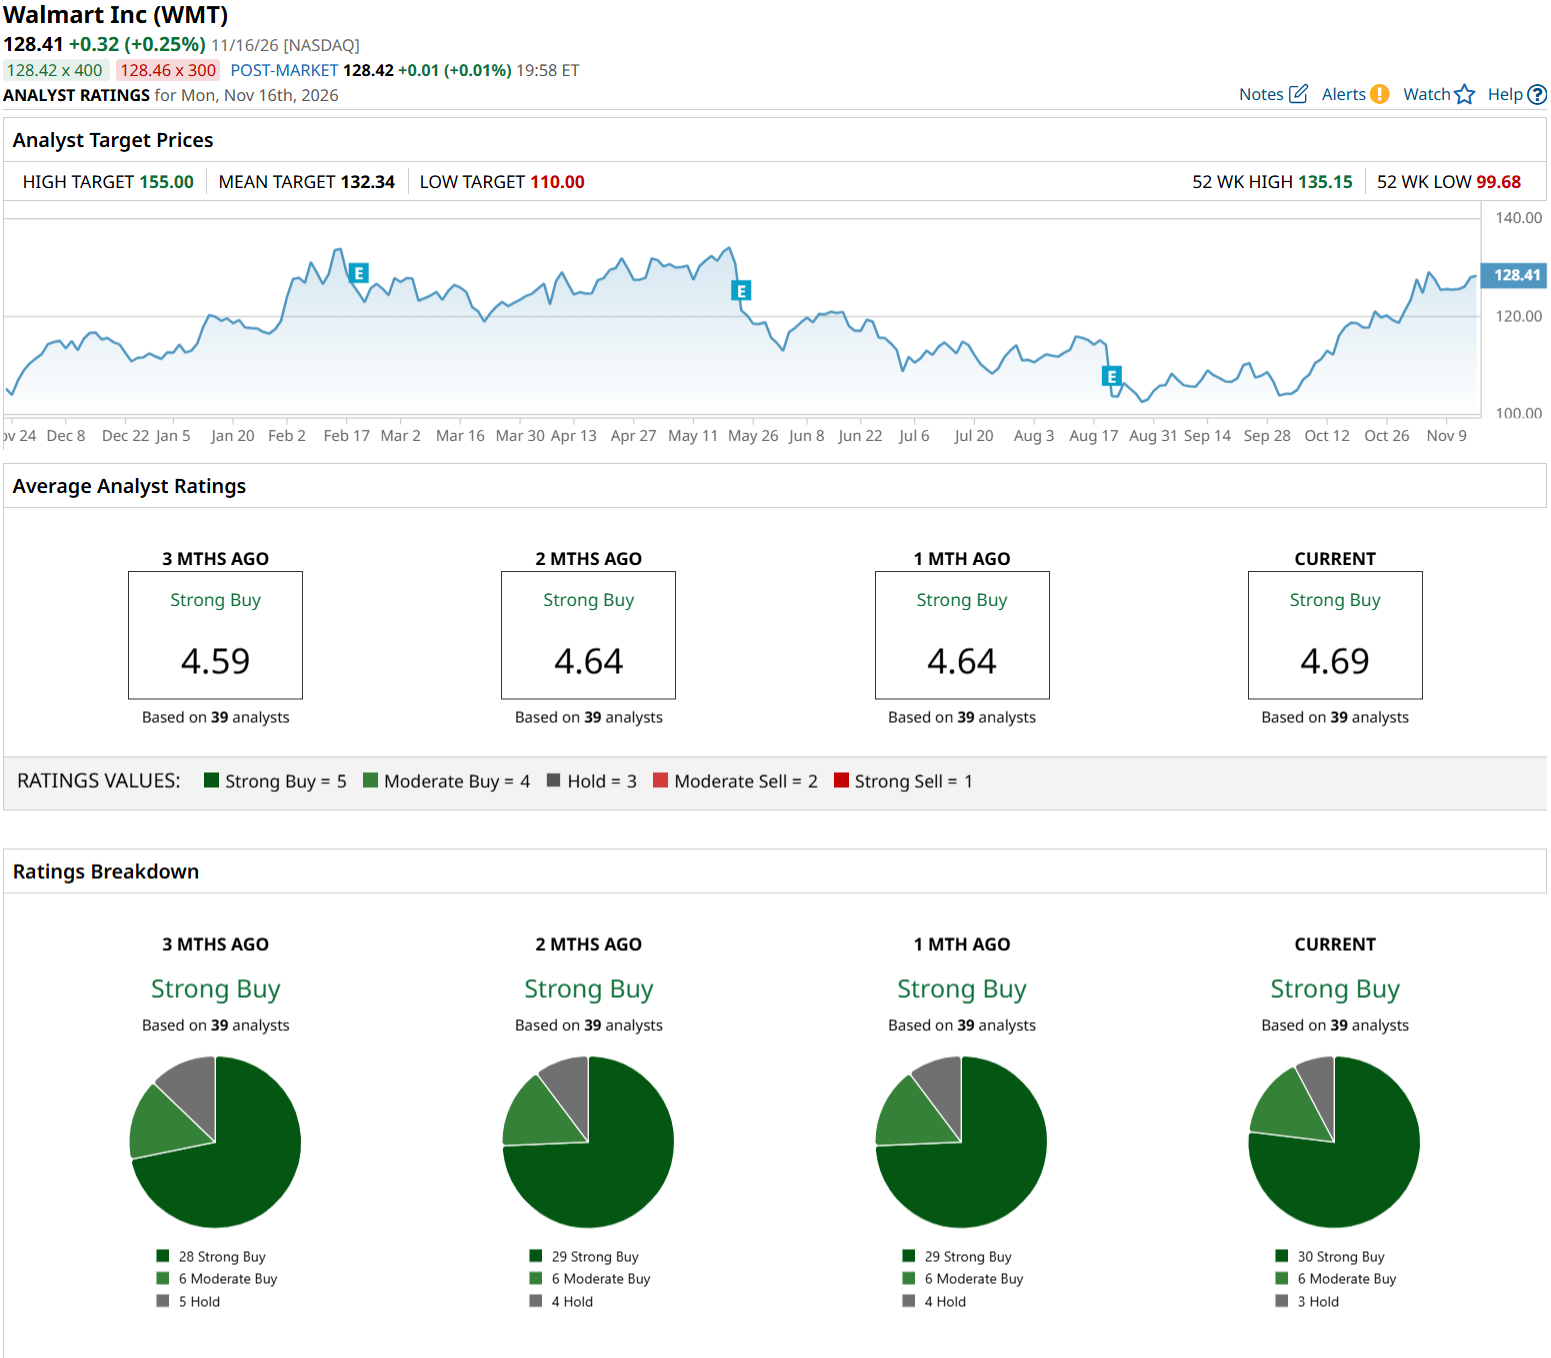
Based on 39 analysts with coverage, WMT stock has a consensus “Strong Buy” rating. Still, the average price target of $132.87 leaves just 4% potential upside from current levels.
Conclusion
Walmart looks capable of sustaining growth beyond tariff refunds, but the Nov. 19 report needs to show that strength translating into underlying profits. Advertising, memberships, and e-commerce support that case, while its premium valuation raises the bar for a positive surprise. My base case is a muted reaction rather than a sharp rally, unless earnings and guidance meaningfully exceed expectations. With the average analyst target offering limited upside, solid results alone may not be enough. The clearest bullish signal would be stronger profitability without temporary benefits, backed by guidance that gives investors a reason to raise their expectations.
On the date of publication, Ebube Jones did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.