


Baidu has seen its share price fall sharply in recent years, and the drop has pushed many investors to ask whether the current valuation still lines up with the earnings power of the business. With AI projects expanding and the core online advertising arm under pressure, the issue is whether the stock price fairly reflects what the company is actually earning today.
- Over the past 5 years, Baidu’s share price has declined 53.0%, which puts a lot of weight on the question of how much of the business’s earnings story the market is already pricing in.
- Rapid growth in AI cloud and autonomous driving services can change how investors think about Baidu’s future profit mix, and that may influence how much they are prepared to pay for each dollar of current earnings.
- The analysts covering Baidu have run their own numbers. See what analysts think Baidu's shares could be worth.
The issue now is whether Baidu’s current market price is justified by its earnings when judged against a Fair Ratio benchmark.
Given Baidu’s sharp share price decline and heavy AI focus, it can be useful to cross-check ideas against a wider set of stocks that meet clear rules using the 53 AI infrastructure stocks.
Does Baidu Look Undervalued on Earnings?
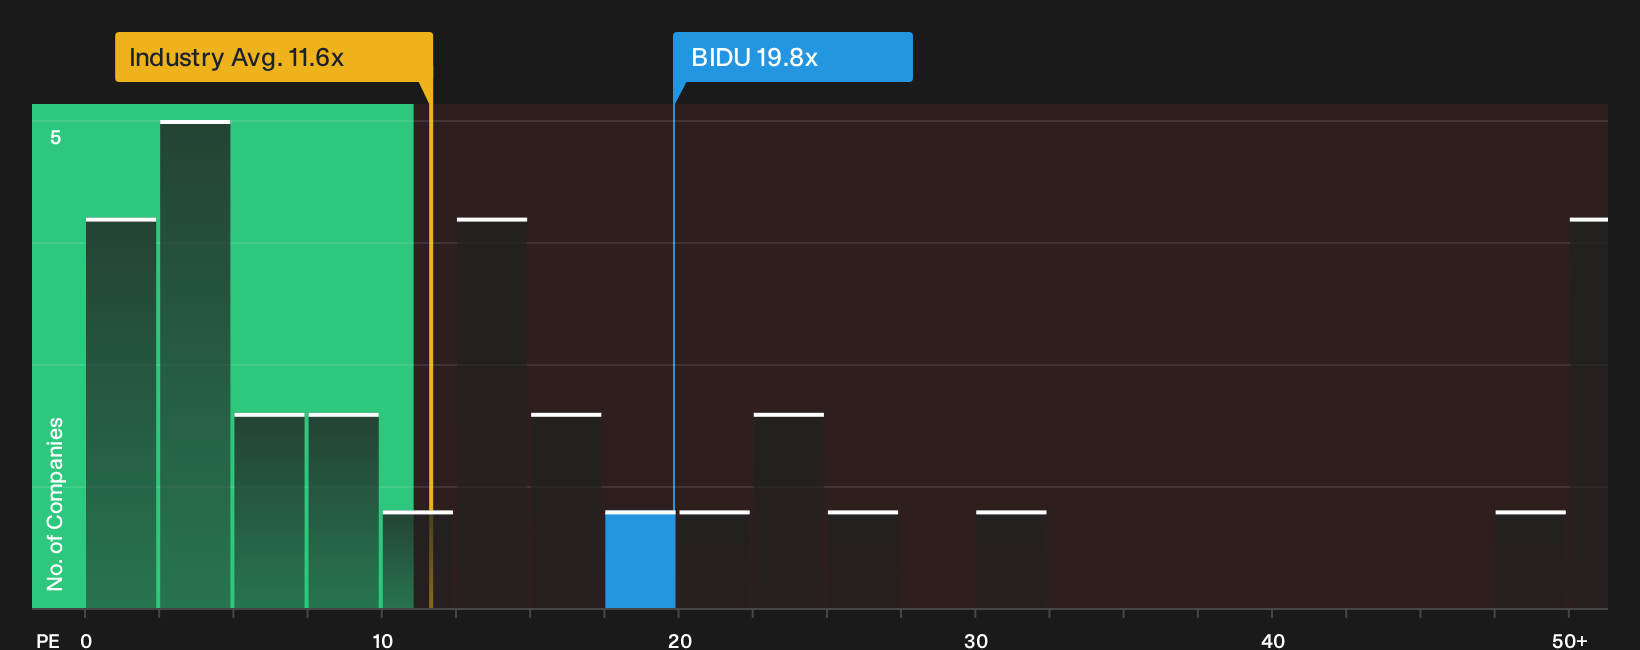
The P/E multiple is often a straightforward way to compare what investors are paying for each unit of Baidu’s current earnings. Baidu trades on roughly 19.8x earnings, which is below the peer average of about 27.6x and above the wider Interactive Media and Services group at around 11.6x. On this measure, the stock is priced between its sector and its closer peers.
A Fair Ratio built from Baidu’s own growth profile, margins, size and risk characteristics points to a higher earnings multiple than the one the market is assigning today. On this framework, the shares screen as undervalued. Because the recent surge in Baidu’s AI cloud revenue has not stopped the stock from lagging, the current P/E still places the business at a discount to where that tailored benchmark would place it. Explore the numbers behind Baidu's P/E valuation.
The Baidu Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take Baidu’s valuation puzzle and spell out the specific growth, margin and earnings paths that would need to play out for the stock to look meaningfully higher or lower than today’s price. Each scenario ties its number to a clear view on how Baidu's growth, profitability and risk profile could shift over time, which gives you something concrete to revisit as fresh information comes through.
One of the top narratives on Baidu: 47% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is that Baidu converts its AI leadership in cloud infrastructure, search monetisation and Apollo Go into sustained, profitable revenue..."
Discover why this Narrative puts Baidu at 47% undervalued.
One more big question for Baidu that this valuation does not answer
The price you see today is only half the story, because analysts have mapped out where they expect Baidu’s earnings and revenues to be in a few years and those paths can frame this valuation in a very different light. Explore where analysts expect Baidu to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com