


Intel (INTC) remains in focus on Nov. 18 following reports that it has cut jobs again as CEO Lip-Bu Tan continues to restructure the semiconductor giant. According to Business Insider, the layoffs have primarily affected the IT department, but the exact number of employees INTC has let go remains uncertain.
Note that Intel stock has been in a huge downtrend in recent weeks, currently trading roughly 60% below its year-to-date high.
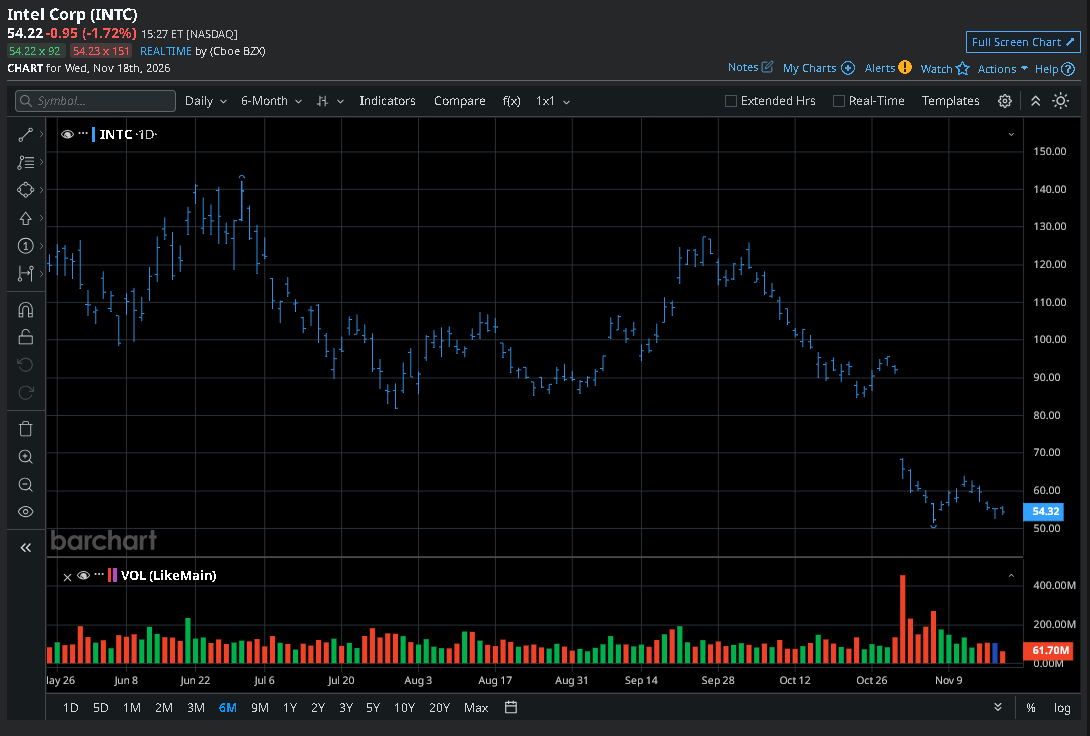
Are Layoffs Bullish for Intel Shares?
In a statement to Business Insider, Intel said it regularly reviews staffing to align resources with its priorities but declined to comment on the number of employees it has laid off. That makes it challenging for investors to evaluate how much these job cuts could cost Intel, or the kind of savings they could generate in the long run.
A leaner IT department could give Intel more room to fund chip development and manufacturing. But the test is whether those savings show up in margins — especially with INTC projecting fourth-quarter adjusted earnings of $0.25 per share, which would represent a significant sequential decline.
Is INTC Stock a Good Long-Term Investment?
While Intel shares’ valuation multiple has come down meaningfully from its peak in June, the bull case remains rooted in the foundry business.
In Q3, that segment posted an operating loss of $1.85 billion, but an external customer committing to INTC’s next-gen 14A manufacturing process would still make the stock more compelling. Why? Because the extra volume would position Intel to spread the cost of its factories across more wafers.
Until then, caution is warranted in playing INTC. The stock also has a history of closing December in the red — a seasonal pattern that dulls its near-term appeal.
How Wall Street Recommends Playing Intel
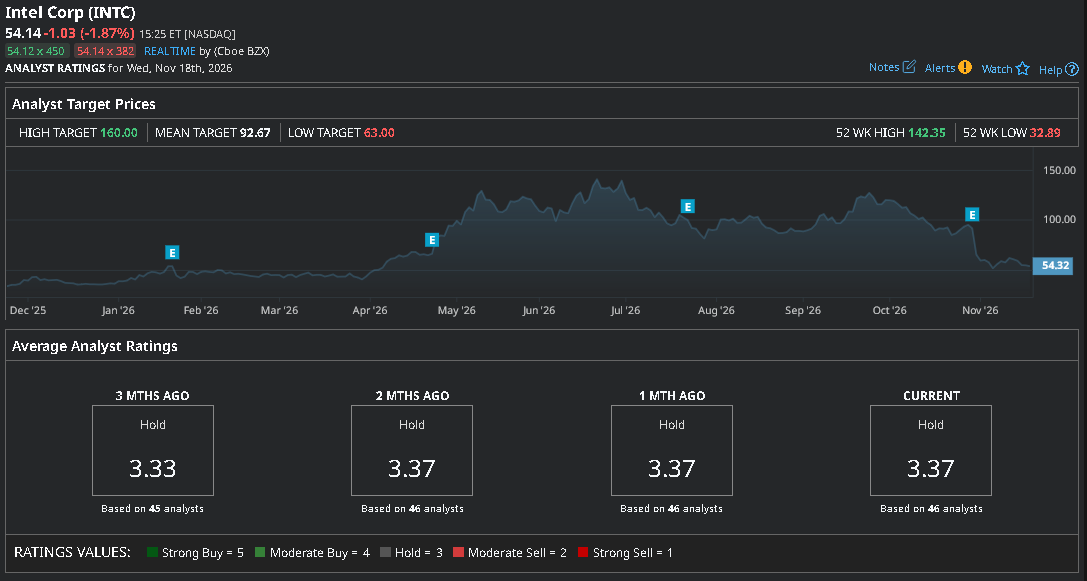
On the flip side, however, Wall Street analysts believe the sell-off in Intel amid a broader AI rout has overextended, creating a fine buying opportunity for long-term investors.
While the consensus rating on INTC stock sits at Hold, the mean price objective of about $92 suggests potential upside of more than 65% from current levels.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.