


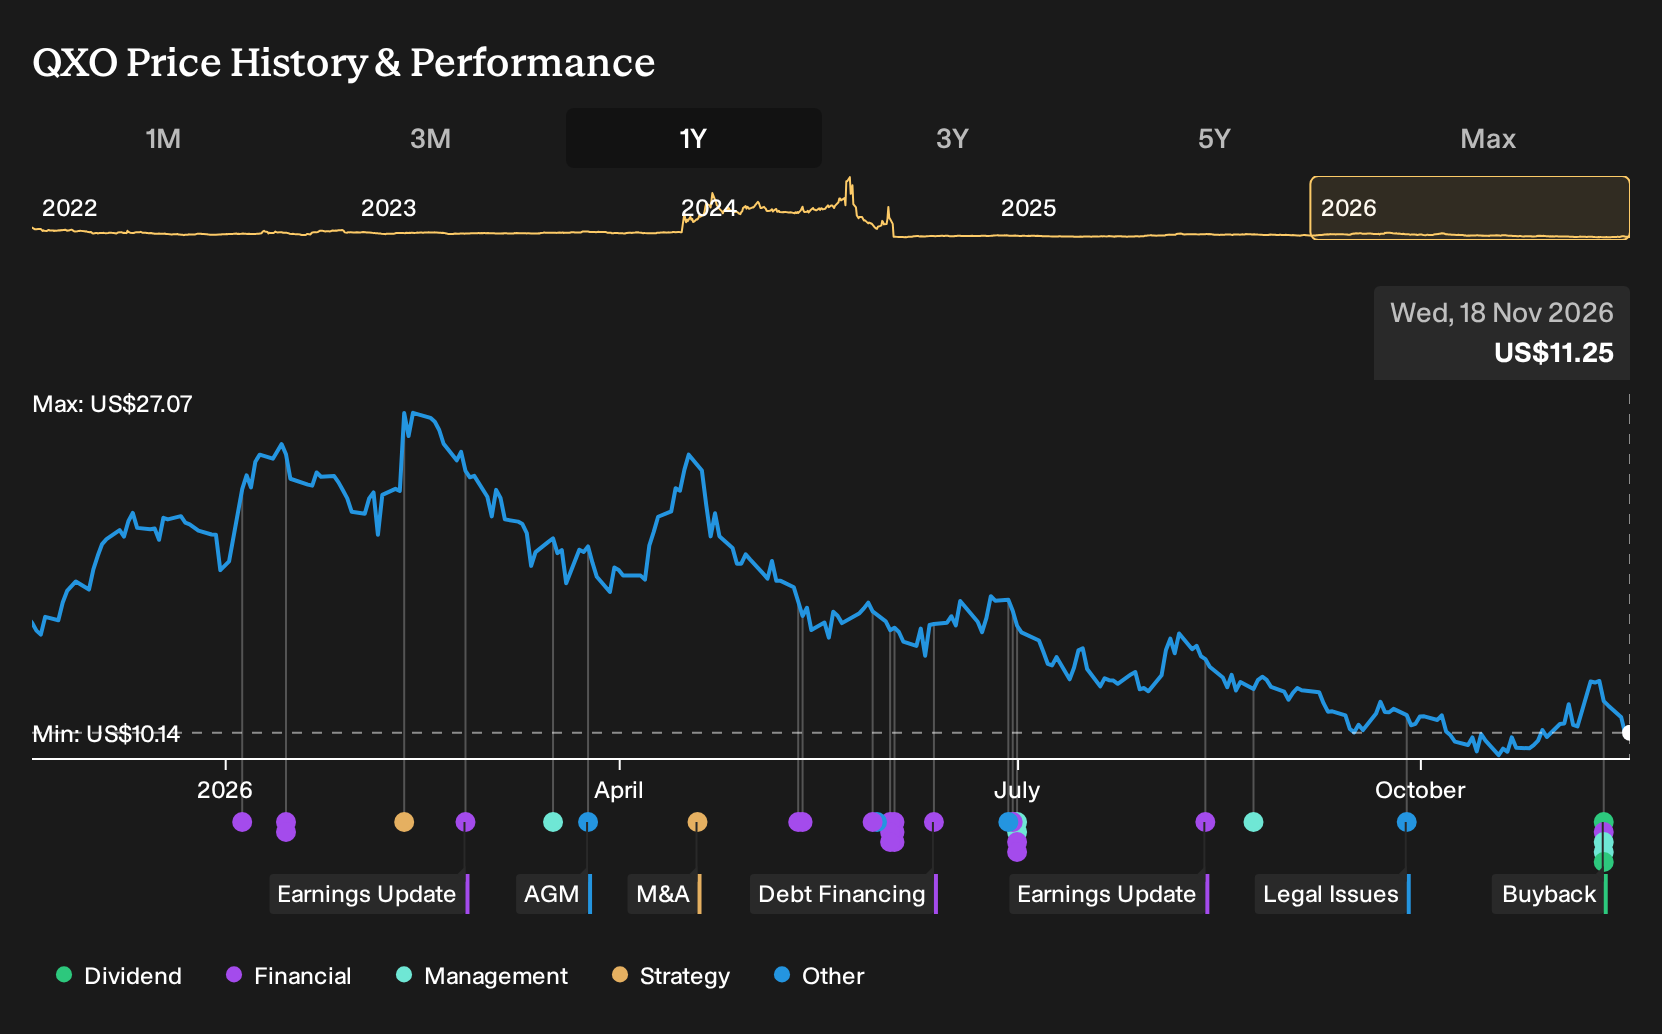
- QXO, Inc. reported third quarter 2026 sales of US$4.895b and a net loss of US$123 million, announced a US$500 million share repurchase plan, and confirmed upcoming leadership changes including a new Chief Financial Officer starting in January 2027.
- The mix of rapid top line expansion alongside continued losses, combined with a large open-ended buyback and a senior finance leadership reshuffle, places QXO’s capital allocation and execution priorities under a brighter spotlight for investors.
- Attention now turns to how QXO’s investment narrative evolves as management pairs heavy revenue growth with a sizeable, open ended repurchase commitment.
Compare QXO’s buyback and loss profile with other fast growing businesses by scanning our hand picked list of 19 high quality undiscovered gems for context on alternative opportunities.
QXO Investment Narrative Recap
For QXO, believers are effectively backing a fast growing building products distributor that is still loss making but scaling quickly through deals and execution. According to OOO97, an investor in the Simply Wall St Community, the core idea is disciplined M&A in a large market, with technology and process work expected to do the heavy lifting on margins. The latest quarter shows strong sales alongside a net loss, so the near term story still hinges on turning scale into cleaner profitability.
The most important short term catalyst is whether QXO can show clear progress on operating leverage and integration after the Beacon and Kodiak acquisitions. Nine month sales of US$9.871b with a loss of US$405 million keep attention on cost control, pricing systems and cash generation. The biggest current risk is that the complex capital structure and recent dilution make it harder for common shareholders to see that operational progress translate cleanly into per share value.
The US$500 million share repurchase authorization sits right in the middle of that debate. QXO is signaling a willingness to commit sizeable capital to its own equity while the business still reports losses, has a fresh acquisition footprint to digest and carries higher risk funding with no customer deposits. There is no set end date for the program, which means execution speed and timing remain open questions for investors tracking near term catalysts.
This buyback also intersects with OOO97’s focus on capital deployment discipline and M&A firepower. A repurchase program of this size can affect how much flexibility exists for future deals or balance sheet repair, so investors may want to see how management balances repurchases against integration spending and data or AI investments that are central to the thesis. For now, the authorization adds a new moving part to monitor alongside margin progression and the upcoming finance leadership transition.
OOO97’s narrative reaches a fair value of US$32.53 per share for QXO by pairing 36.0% annual revenue growth with a future 12.5% profit margin. Together, these factors support higher earnings power and justify that valuation level on their probability weighted view.
Uncover why QXO's fair value indicates a 189% potential upside to its current price before that discount to QXO closes.
Exploring Other Perspectives
Some of the most optimistic analysts frame QXO as a revenue story first. Before this update, they were pencilling in 39.8% annual sales growth for three years and about US$33.0b of revenue by 2029. That outlook assumes the US$500m buyback and heavy M&A spend will boost earnings toward US$364.1m, although views differ widely and may shift after these results.
Explore 2 other QXO fair value estimates, including one that suggests as much as 258% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your QXO research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for QXO. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate QXO's overall financial health at a glance.
Looking for more QXO style investment ideas?
If QXO has sharpened your thinking about growth, risk and capital allocation, it can help to compare it with other businesses that fit different profiles on value, income and resilience. Use the Simply Wall St Screener to line up candidates side by side, then decide which mix of quality, balance sheet strength and potential return best matches your own approach.
- For investors who want quality at a sensible entry point, start with a focused set of potentially attractively priced companies by reviewing the 35 high quality undervalued stocks.
- If capital preservation and financial resilience sit near the top of your checklist, narrow the field using our 30 resilient stocks with low risk scores as a filter for sturdier balance sheets and steadier fundamentals.
- Those looking to combine income with financial strength can scan a list of solid balance sheet and fundamentals (24 results) to see which companies pair robust finances with the potential for more durable returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com