


Bloom Energy has seen its share price swing sharply in recent years, which puts extra focus on a simple question for you as a shareholder or potential buyer. Do today’s earnings support where the stock now trades, or has the story moved faster than the profit line behind it.
- Over the past 3 years the stock has delivered a very large gain of around 12x, which means even small changes in earnings expectations can matter a lot to what feels like a sensible price.
- The 900 MW fuel cell rollout agreed with NTT DATA for global data centers, alongside projects with Oracle and other large customers, can shape how quickly Bloom Energy converts its order pipeline into profit and when cash flows show up.
- Your read on Bloom Energy is one view; the desks covering it have another. See what analysts think Bloom Energy's shares could be worth.
The issue now is whether Bloom Energy’s recent earnings are strong and durable enough to justify the current share price after such a dramatic move.
If you want to test the same earnings question you are asking of Bloom Energy across a broader set of power and grid suppliers linked to data centers and AI infrastructure, it is worth scanning 44 power grid technology and infrastructure stocks.
Does Bloom Energy Look Pricey on Earnings?
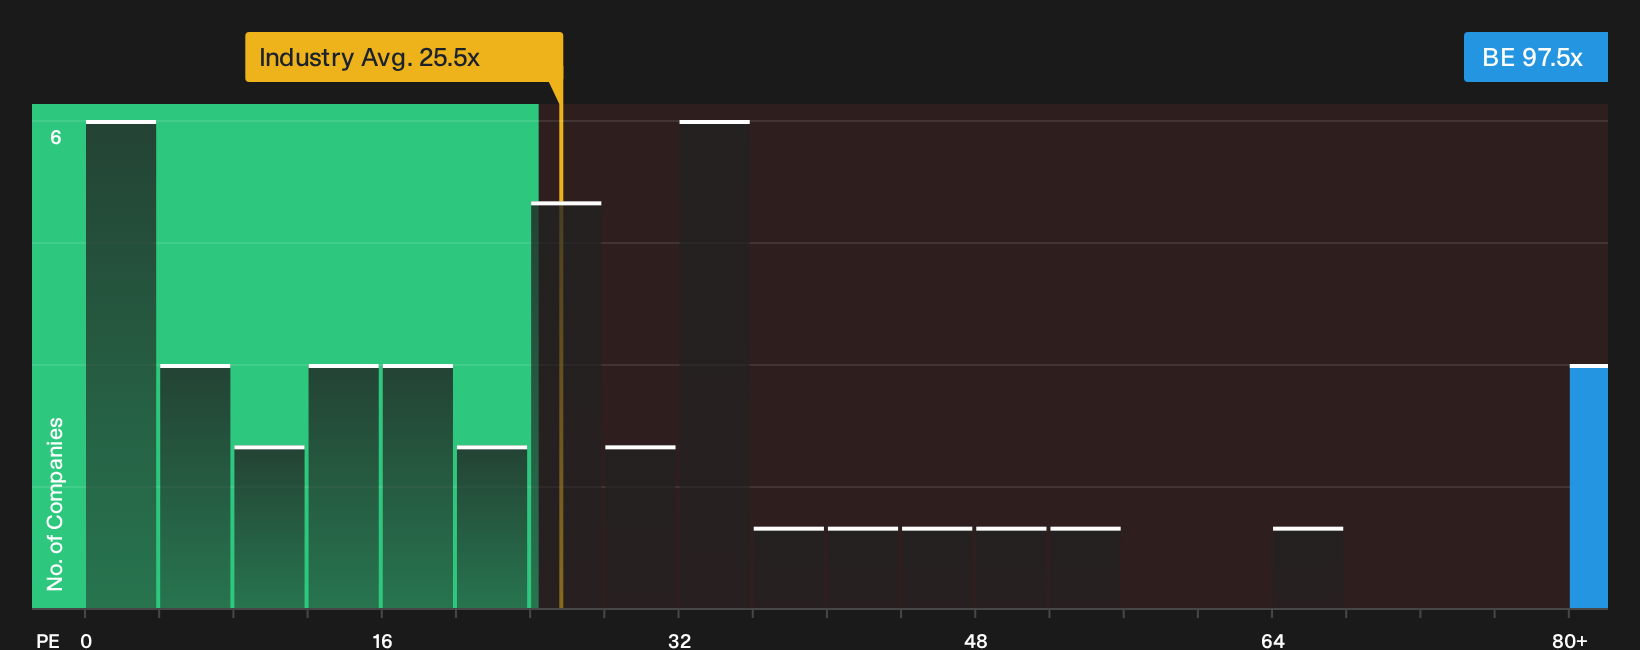
A P/E lens fits Bloom Energy because the market conversation is now squarely about earnings power rather than just revenue potential. The stock trades on a P/E of 97.5x, which is far above the broader Electrical industry average of 25.5x. Against closer peers, the gap is still wide, given a peer group average of 54.0x.
The tailored fair P/E that blends Bloom Energy’s growth profile, margins, sector and risk points to a lower multiple than the current one, which leaves the shares screening as overvalued on this metric. Because recent fuel cell deals such as the 900 MW NTT DATA program have already pushed expectations higher, the current P/E implies investors are paying a premium price for the earnings analysts see ahead. If you want to see how large that gap is and whether the premium still looks acceptable once you compare it to other Electrical stocks, you can run Bloom Energy through the valuation tools in. Explore the numbers behind Bloom Energy's P/E valuation.
The Bloom Energy Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle for Bloom Energy leaves off. They map out which future paths for growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price, and sit on Simply Wall St’s Community page. Each one treats Bloom Energy’s fair value as a thesis you can track over time rather than a single frozen snapshot.
Bullish and bearish views on Bloom Energy separate mainly on how quickly interest from big power users turns into cash-heavy projects.
Bull case: 56% undervalued
According to JRY, a Simply Wall St Community investor who wrote the Narrative, Bloom Energy’s opportunity set is still widely misunderstood.
"The Bloom Energy story is still early days, Wall Street cannot seem to comprehend that so many areas for their growth , international, other market segments, even personal or community power , are largely untapped…"
Discover why this Narrative puts Bloom Energy at 56% undervalued.
Bear case: 20% overvalued
The bearish analyst Narrative on Simply Wall St sees execution and funding risk around very large AI and data center deals.
"Although Bloom Energy has secured validation from major hyperscalers for on site AI power, the 21% share price decline around September 2026, coupled with worries about funding and timing for very large data center projects, points to a real risk that contracted or verbally committed capacity does not convert into revenue on the timelines implied in current expectations…"
Explore why this Narrative puts Bloom Energy at 20% overvalued.
One question Bloom Energy’s valuation cannot answer on its own
Bloom Energy’s pricing story only goes so far if some of the underlying checks are flashing concern, and the real task is to see exactly what those red flags are and how serious they look. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com