


The Zhitong Finance App learned that according to TrendForce Jibang Consulting's latest memory industry research, the global NAND Flash industry will usher in a reversal of supply and demand in 2027; in a situation where overall supply will grow rapidly, as some cloud service providers (CSPs) drastically cut enterprise SSD orders, and demand from consumer electronics products may further slow down, the market oversupply situation will intensify. TrendForce Jibang estimates that the overall NAND Flash contract will increase from the first quarter of 2027 Prices will shift to a downward trend, and the decline may expand quarterly.
TrendForce Jibang Consulting estimates that in 2027, the global NAND Flash industry's capital expenditure will increase by 26.7% per year to reach 29.9 billion US dollars. Due to strong demand for high-performance storage in North America, the original factory is expanding production and manufacturing processes are continuing. In addition, the penetration rate of QLC products and high-level digital processes have increased. Even if some suppliers consider the slowdown in consumer demand and a slight slowdown in production expansion, it is estimated that the annual growth rate of the global NAND Flash supply level will still be between 25% and 30% in 2027.
As the main growth engine of the NAND Flash industry, the level of demand for enterprise SSDs varies in different regions. In the North American market, US CSPs have benefited from AI agent and general-purpose server projects that have already started, and recently increased demand again in 2027. Some CSPs lowered their total Enterprise SSD orders in 2027 due to factors such as GPU supply, inventory adjustments, and token prices, which surpassed the increase of American manufacturers.
In the consumer market, it is expected that in 2027, due to the depletion of low-priced memory inventory, complete machine products will face upward pressure, and shipments will be affected again. Furthermore, in order to control BOM cost, brand manufacturers needed to reduce product capacity specifications, causing the average carrying capacity of a single machine to drop drastically, and the demand gap widened further.
It is estimated that 1Q27 NAND Flash prices will drop by 0% to 5% per quarter, and all categories will enter a cycle of falling prices starting in 2Q27
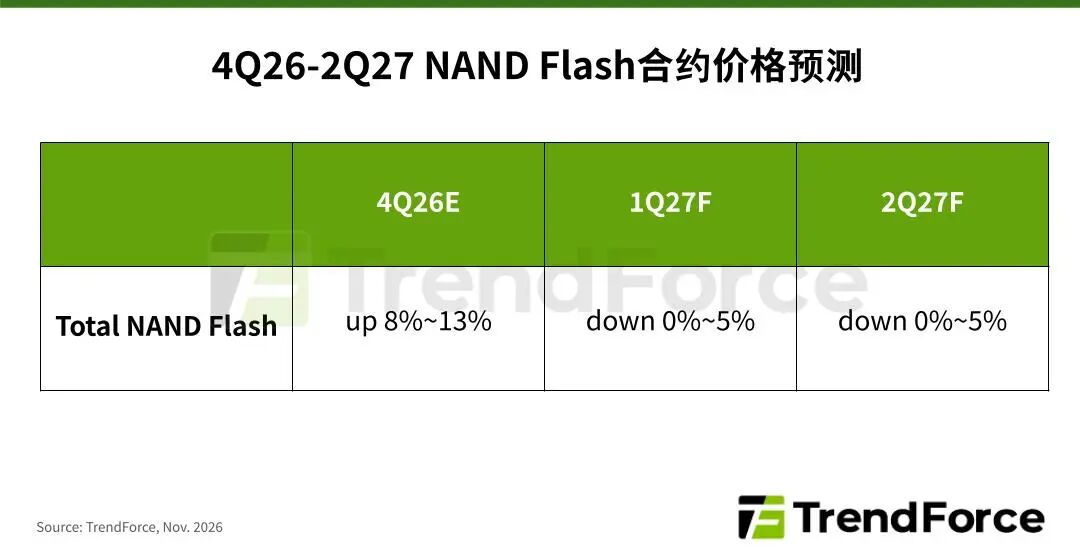
TrendForce Jibang Consulting said that due to the continued decline in global consumer product shipments and the reduction in enterprise SSD orders in some markets, NAND Flash contract prices have shown a slowdown in the fourth quarter of 2026, and TrendForce Jibang Consulting has lowered the quarterly increase of 8% to 13% as a result. The slowdown in demand has triggered pressure to clear inventory, leading to a sharp correction of more than 20% in spot prices recently.
Looking ahead to 2027, as some CSPs cut enterprise SSD demand margins to offset the growth of orders in North America, the annual supply growth rate will be significantly higher than the increase in demand, and the oversupply trend intensifies. It is expected that the overall NAND Flash contract price for the first quarter will be reduced by 0% to 5% quarterly, and all products will enter a cycle of price decline starting in the second quarter.
TrendForce Jibang Consulting pointed out that subsequent market development will depend on the degree of removal of some CSP inventories, changes in the global GPU supply pattern and procurement strategy, and the continued adoption of downsized memories in the consumer market in 2028.