


AbCellera Biologics has seen its share price surge this year, which naturally puts fresh attention on whether that move still lines up with the book value sitting on its balance sheet. With sentiment shaped by fresh clinical data and capital raising, the key issue for you is how much of that is already reflected in the current valuation.
- Year to date, AbCellera Biologics has gained about 221.3%, which raises the question of how closely the current share price tracks the value of its net assets.
- Recent positive Phase 2 results for ABCL635, new pipeline additions, and a US$200 million offering may support higher expectations for future returns on the firm’s equity base and its funding needs.
- Your read on AbCellera Biologics is one view; the desks covering it have another. See what analysts think AbCellera Biologics's shares could be worth.
The stock's next move may depend on whether the current price still has a clear anchor in AbCellera Biologics' book value relative to the industry average.
If you want other reference points for this kind of book value story, compare AbCellera Biologics with companies in the same space using the 35 high quality undervalued stocks
Does AbCellera Biologics Look Fairly Valued on Book Value?
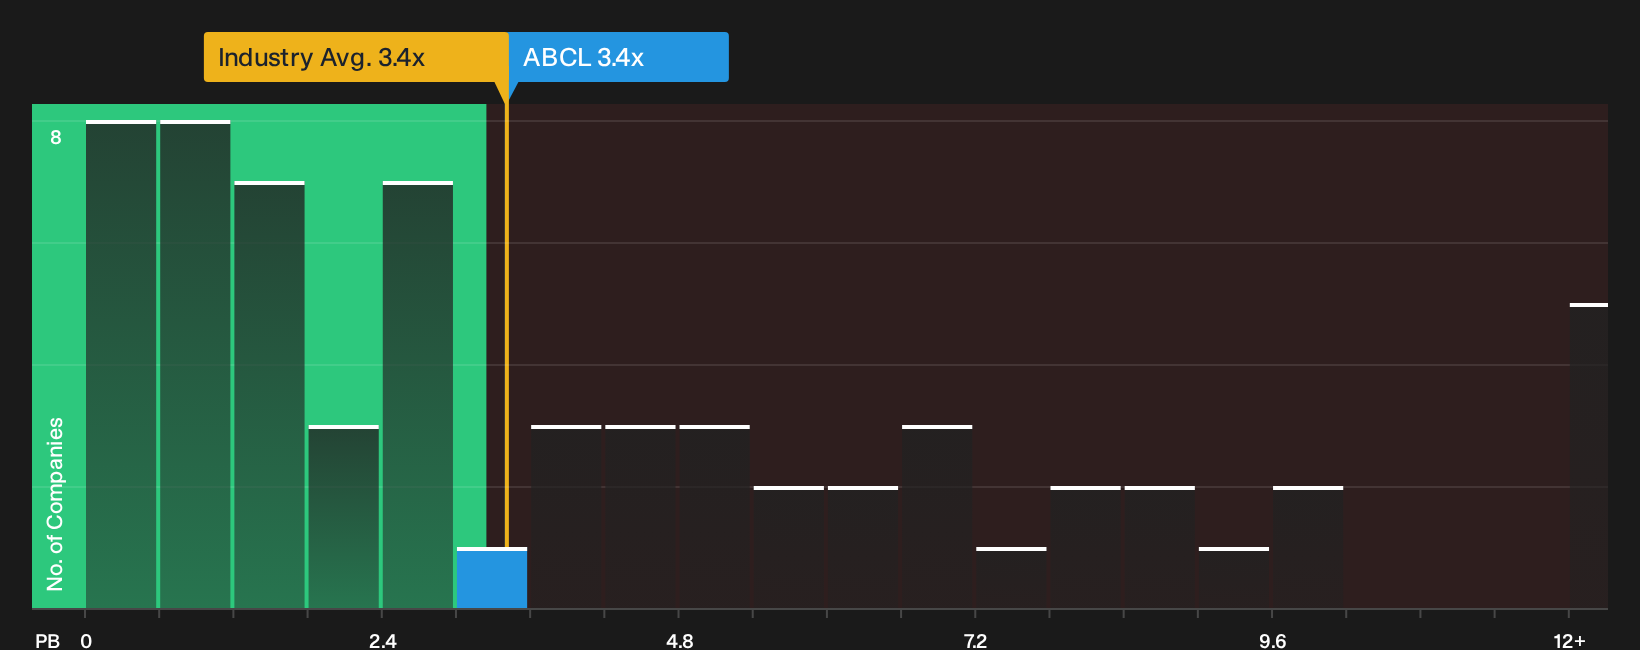
P/B is a useful lens for AbCellera Biologics because much of the story today is about the value investors place on its equity base rather than near term earnings. On that measure, the stock trades at about 3.4x book value, almost exactly in line with the Life Sciences industry average of roughly 3.4x.
Because the recent Phase 2 success for ABCL635 has raised expectations around the pipeline, the fact that AbCellera Biologics shares change hands at a P/B multiple broadly matching sector peers suggests the market is pricing in that news without assigning a clear premium or discount to the balance sheet. For you, the key question is whether the current mix of clinical assets, cash from the US$200 million offering, and future capital needs justifies paying a sector level P/B multiple for this particular business. Explore the numbers behind AbCellera Biologics's P/B valuation.
The AbCellera Biologics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for AbCellera Biologics pick up where the valuation puzzle leaves off, explaining which paths for growth, profitability, and earnings would need to occur for the stock to be worth meaningfully more or less than it is today on book value. Instead of giving you just a single output from a ratio or model, they outline the future that number relies on so you can track over time whether that story is still holding up.
One of the top narratives on AbCellera Biologics: 36% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Multi program T cell engager collaborations with partners such as Jazz Pharmaceuticals and Vertex, which have already brought in over US$110 million in upfront payments..."
Discover why this Narrative puts AbCellera Biologics at 36% undervalued.
One more angle on AbCellera Biologics that could change your view
Before you lean too heavily on book value and pipeline narratives, it is worth knowing that our broader checks on AbCellera Biologics flag specific concerns that deserve a closer look. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com