


With approval from the Securities Regulatory Commission, Orient Securities (03958) acquired 100% of the shares in Shanghai Securities, and the integration of Shanghai state-owned brokerage firms with a price of 25.12 billion yuan has entered the implementation stage.
The Zhitong Finance App learned that on November 18, Orient Securities issued an announcement stating that the acquisition of 100% of the shares in Shanghai Securities was approved by the Securities Regulatory Commission, agreeing to the company's registration application to issue shares and pay cash to purchase assets and related transactions. This means that brokerage firms within the Shanghai State-owned Assets System have been merged and restructured, and that all supervision and approval procedures have been completed. The purchase transaction price was 25.120 billion yuan, of which 23.55 billion yuan for shares and 1,570 billion yuan for cash.
This is a transaction that uses “low premium+low cash consumption” in exchange for a “jump in scale+business complementarity”, making Orient Securities a scarce target with both defensive safety pads and offensive flexibility in the current brokerage sector. However, the company's PB is only 0.45 times. Has this 10 billion acquisition brought it an opportunity to revalue it?
The acquisition valuation is low, and the share exchange introduces strategic shareholders
Orient Securities's acquisition of 100% of Shanghai Securities's equity payment method is “mainly shares, supported by cash”. On the one hand, it obtains strategic shareholder entry through equity swaps to improve the shareholder structure and increase share value. On the other hand, the cash burden is small, and there is little financial pressure. After the merger, the advantages of both parties can be fully integrated to exert greater synergy.
According to the restructuring report, the company replaced shares by issuing A shares. It plans to issue about 2,289 million shares, accounting for 21.22% of the total share capital after issuance, of which approximately 1,221 million shares will be issued to Bailian Group, 457 million shares to Cathay Pacific Haitong, 399 million shares to international investment, approximately 187 million shares to Shanghai International, and 24.4 million shares to Shanghai City Investment Group. After the issuance was completed, the above investors became the main strategic shareholders of the company.
In addition, the full cash consideration of 1,570 billion yuan was paid to Cathay Pacific Haitong Securities, funded from Orient Securities's own funds. From a financial security perspective, as of September 2026, the company had cash equivalents of up to 151,946 billion yuan, and the impact of this cash payment on the balance sheet was minimal. After the transaction is completed, Orient Securities's total assets are expected to exceed 600 billion yuan and net assets to exceed 100 billion yuan. The asset scale is expected to rank among the top ten in the industry.
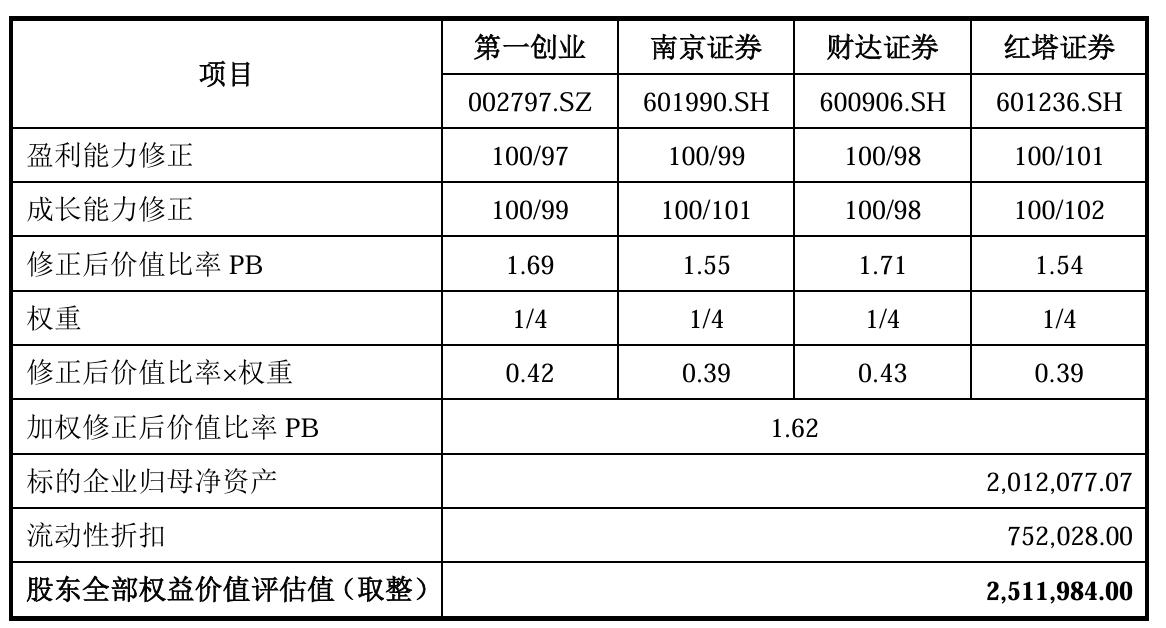
Image source: Company announcement
Orient Securities used “equity dilution” rather than “financial leverage” in exchange for a leap in scale, and the valuation of this acquisition was not high. Judging from asset pricing, as of March 2026, Shanghai Securities had net assets of 20.21 billion yuan and cash of 32,526 billion yuan. The total net cost ratio and realization rate were 1.25 times and 0.77 times, respectively, lower than the level of the industry (comparable company). There was not much goodwill generated on the books, but net book assets and cash both increased significantly after the merger.
The synergy effect is bigger and stronger, and the best target for defensive investment
The business of Orient Securities and Shanghai Securities is highly complementary. The business models of the two companies are not very different, but their core competitive advantages complement each other. The core business of Shanghai Securities is wealth management, and it has solid offline channels and investment tools. Orient Securities's core advantage lies in asset management and investment banking business, but the brokerage business has also maintained a steady growth trend. There are complementary business advantages, but what really has a large-scale effect is the expansion of customer and service networks.
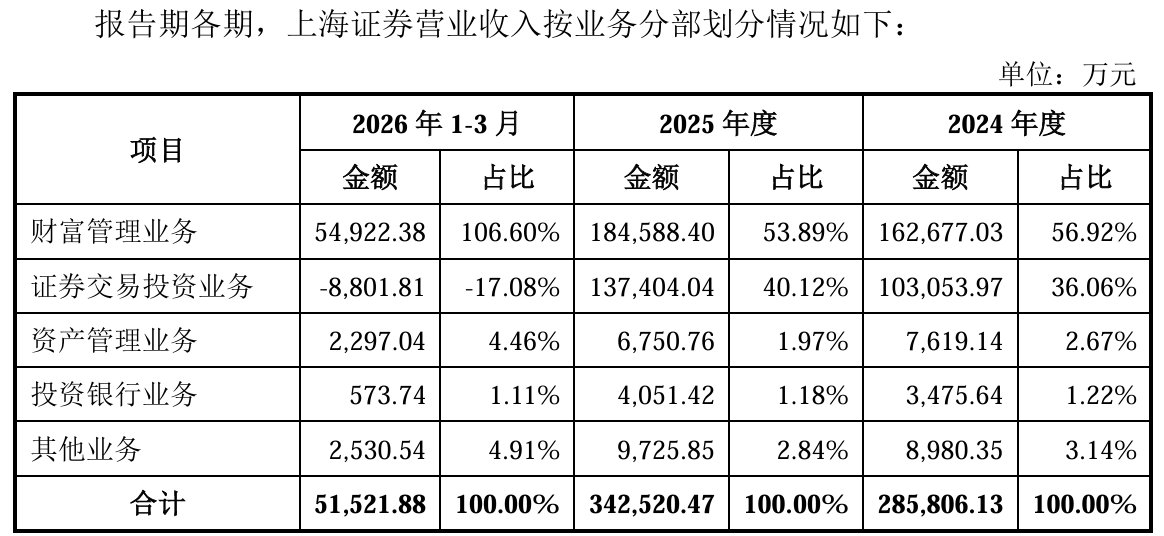
Image source: Company announcement
As of the end of June 2026, Orient Securities had about 3.4856 million customer fund accounts, while Shanghai Securities had a brokerage network with many years of experience in Shanghai and the Yangtze River Delta. After the merger, the number of customer fund accounts will exceed 5 million, and the number of branches will expand to about 250, including 77 sales departments in Shanghai, ranking first in the industry.
After the merger of the two companies, Orient Securities will record significant growth in revenue from core businesses such as brokerage, asset management, and investment banking, and under the synergy, it is possible to explore the demand for quality services from both customers and improve asset quality. Furthermore, the profitability of Shanghai Securities is also strong. In 2025, it achieved net profit of 1,323 billion yuan, an increase of 38.81% over the previous year, and a high double-digit compound growth in the past few years. After the merger, the company's profit will increase by more than 20%.
This wave of acquisitions by Orient Securities is not only an increase in account performance, but also a strong implementation of the policy of building a strong financial country with Chinese socialist characteristics. The acquisition, which was completed under the guidance of various departments and participating leaders, and the efforts of Orient Securities's current management team, expanded the professional team, strengthened financial infrastructure barriers, consolidated the moat for business, and laid a good foundation for future sustainable and healthy development. It is expected that the various businesses will record steady, significant, and sustainable healthy growth in the future.
In the capital market, Orient Securities will usher in definitive allocation opportunities, which are mainly driven by two core logic:
First, the geographical conflict and the Fed's interest rate hike, compounded by the AI overvaluation bubble, continued to interfere with capital market valuations. The panic index soared repeatedly, and defensive investment became the first choice. However, the brokerage sector is generally undervalued. After a year of retreat, the sector's PB value is only 0.6 times. It is less sensitive to “killing valuations” and is highly defensive. However, Orient Securities's PB is only 0.45 times lower than the industry average, and has multiple safety margins in the defense sector.
Second, Orient Securities increased its overall strength after this acquisition, and the competitiveness and resilience of the industry were significantly improved. Furthermore, the regulatory authorities clearly supported mergers, acquisitions, restructuring and subsequent integration of the industry, and the trend of concentrating industry resources on leading brokerage firms will only strengthen in 2027. Meanwhile, Orient Securities ranks among the top ten in terms of assets through this acquisition, and will substantially improve its position in terms of obtaining business qualifications and entering institutional business. The company introduced a number of strategic shareholders such as Bailian Group through equity swaps. The shareholding structure is more stable, which has effectively boosted market confidence in the current pessimistic market sentiment.
Overall, Orient Securities officially entered the implementation stage after the acquisition of Shanghai Securities was approved by the Securities Regulatory Commission, but there is still some cycle until the acquisition is completed, yet this also gave the market higher expectations. The valuation of this acquisition is low. The target is of high quality. Its net asset value, cash flow and performance have all continued to grow, and the company's cash consumption under the “equity replacement+cash” model is small, and the company's performance will be greatly enhanced later.
After the acquisition is completed, Orient Securities's various businesses are expected to grow in scale and seize a larger market share in the industry under the synergy effect. For funds seeking defensive allocations, Orient Securities's PB of only 0.45 times provides a high fault tolerance rate, constituting a potential trigger for valuation repair, making it the most scarce variety in defensive allocations.