

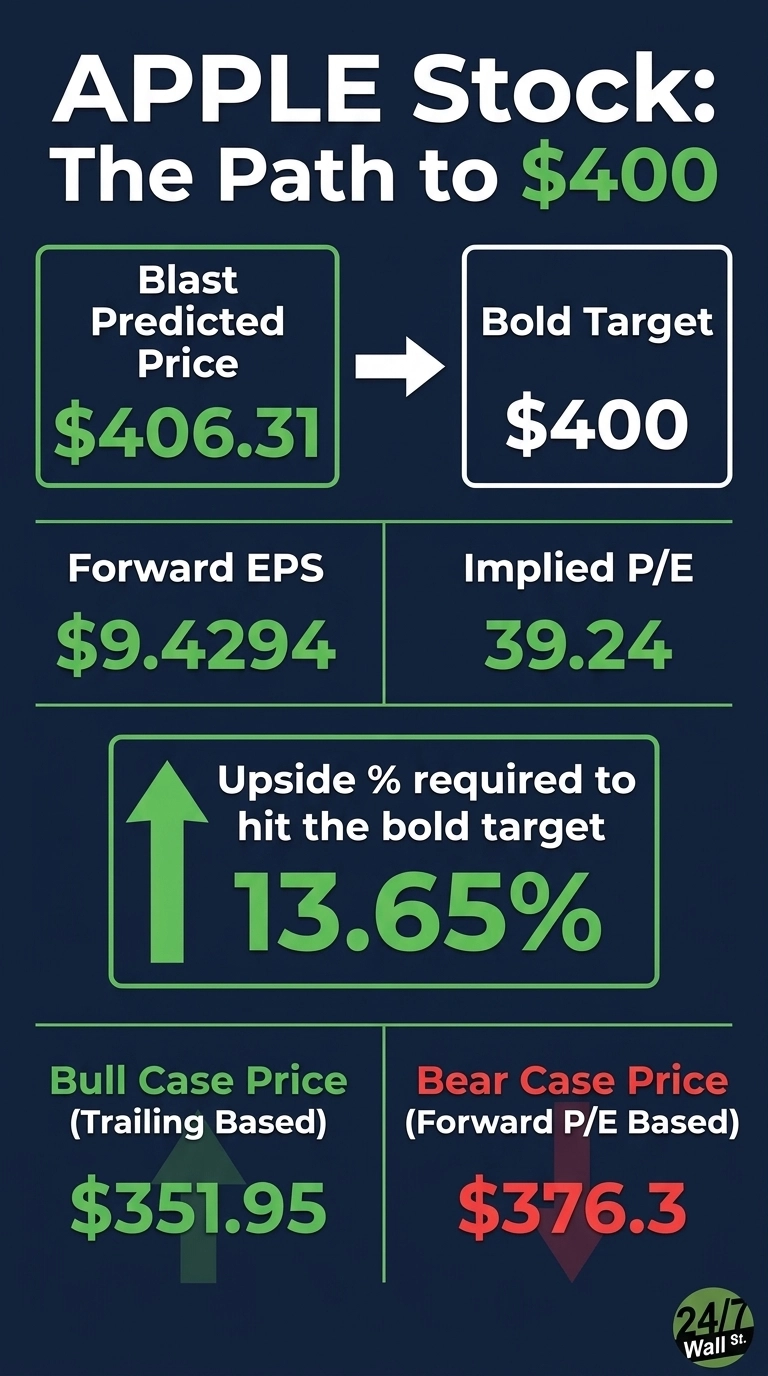
Apple (NASDAQ:AAPL) last closed at $351.95 and was trading near $350.69 in premarket. If the stock reaches $400, a $5,000 investment bought at the last close would be worth about $5,682.63, a gain of roughly 13.65%.
Shares are already up 29.45% year to date, so the next question is whether Apple’s record fiscal year can carry the stock past $400. This forecast uses the model’s 1-year period, which ends in 2027.
What $5,000 Could Become If Apple Hits Its Base-Case TargetIn the base case, a $5,000 investment in Apple could be worth about $5,772 by 2027, a total return of 15.44%. That depends on a 1-year price target of $406.31, just above the $400 mark in the title.
On the model’s monthly path, the base case first moves above $400 at $410.06 in October 2027. The bull path gets there sooner, reaching $401.98 in April 2027.
 24/7 Wall St.
The target blends trailing P/E, forward P/E and analyst targets, weighted 20%, 50% and 30%. It uses forward EPS of $9.4294 and a forward P/E near 37x. The model’s confidence score is 0.9, which it rates as high.
Analysts are more conservative, with a consensus target of $346.37, below the current price. Analyst ratings break down as 6 strong buy, 18 buy, 13 hold, 3 sell and 3 strong sell.
Bull, Base and Bear Outcomes for a $5,000 Apple Stake Scenario (1-Year) Target Price Total Return Value of $5,000 Bull $461.15 31.03% $6,551.50 Base $406.31 15.44% $5,772 Bear $342.48 -2.69% $4,865.50Over the model’s 5-year period, which runs to 2031, the base case rises to $560.87. That would turn $5,000 into $7,968. The bull case reaches $9,616.50 and the bear case $5,433.50. Even after five years, the bear case ends at $382.46, still short of $400.
Three Drivers That Could Push Apple Past $400 Earnings MomentumFiscal 2026 revenue reached $478.83 billion, up 15.06%. EPS came in at $8.98, ahead of the $8.82 consensus. The September quarter extended Apple’s run of EPS beats to ten quarters in a row. Management expects December-quarter revenue to grow 7% to 10%, which would make it the best revenue quarter in Apple’s history.
Services and the Installed BaseServices revenue hit an all-time high of $31.57 billion, with a gross margin of 76%. Apple has more than 2.5 billion active devices in use and over 1.5 billion paid subscriptions. The CFO said the company is “optimistic about the long-term future of our services business.”
Product Cycle and Siri AICEO John Ternus called the holiday lineup “our most ambitious lineup yet.” It includes the iPhone Duo, iPhone 18 Pro, Touch on Mac and the all-new Siri AI. In Greater China, September-quarter revenue rose 21%.
Risks That Could Keep Apple Below $400Valuation is the biggest hurdle. Apple trades at about 39x trailing earnings, and Bloomberg reports that the stock’s safe-haven status has made it one of the priciest stocks in the market.
The September quarter also got a one-time lift from tariff refunds, which added $0.05 to EPS and about 1 percentage point to gross margin. Management called memory pricing “unprecedented” and guided December-quarter gross margin to 45% to 46%, down from 47.9%.
Some segments are slipping. iPad revenue fell 10% and Wearables, Home and Accessories fell 8%. Inventory rose to $14.54 billion from $5.72 billion. Apple also faces tariff and geopolitical risk, counts on third-party suppliers and is the subject of ongoing regulatory investigations. If these pressures win out, the bear case leaves the $5,000 investment at $4,865.50.
Where a $5,000 Apple Stake Could LandOver the 1-year period, the model puts a $5,000 Apple position between $4,865.50 and $6,551.50, with the base case at $5,772.
A move to $400 falls inside that range, but it depends on margins holding up and Siri AI driving upgrades. The December-quarter earnings report should offer the next signal. These figures are model estimates, and none of these outcomes is guaranteed.