


Let’s dig into the relative performance of Hubbell NYSE:HUBB and its peers as we unravel the now-completed Q3 electrical systems earnings season.
Like many equipment and component manufacturers, electrical systems companies are buoyed by secular trends such as connectivity and industrial automation. More specific pockets of strong demand include Internet of Things (IoT) connectivity and the 5G telecom upgrade cycle, which can benefit companies whose cables and conduits fit those needs. But like the broader industrials sector, these companies are also at the whim of economic cycles. Interest rates, for example, can greatly impact projects that drive demand for these products.
The 12 electrical systems stocks we track reported a solid Q3. As a group, revenues beat analysts’ consensus estimates by 4.7% while next quarter’s revenue guidance was 7.4% above.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 8.4% since the latest earnings results.
Hubbell NYSE:HUBB
A respected player in the electrical segment, Hubbell (NYSE:HUBB) manufactures electronic products for the construction, industrial, utility, and telecommunications markets.
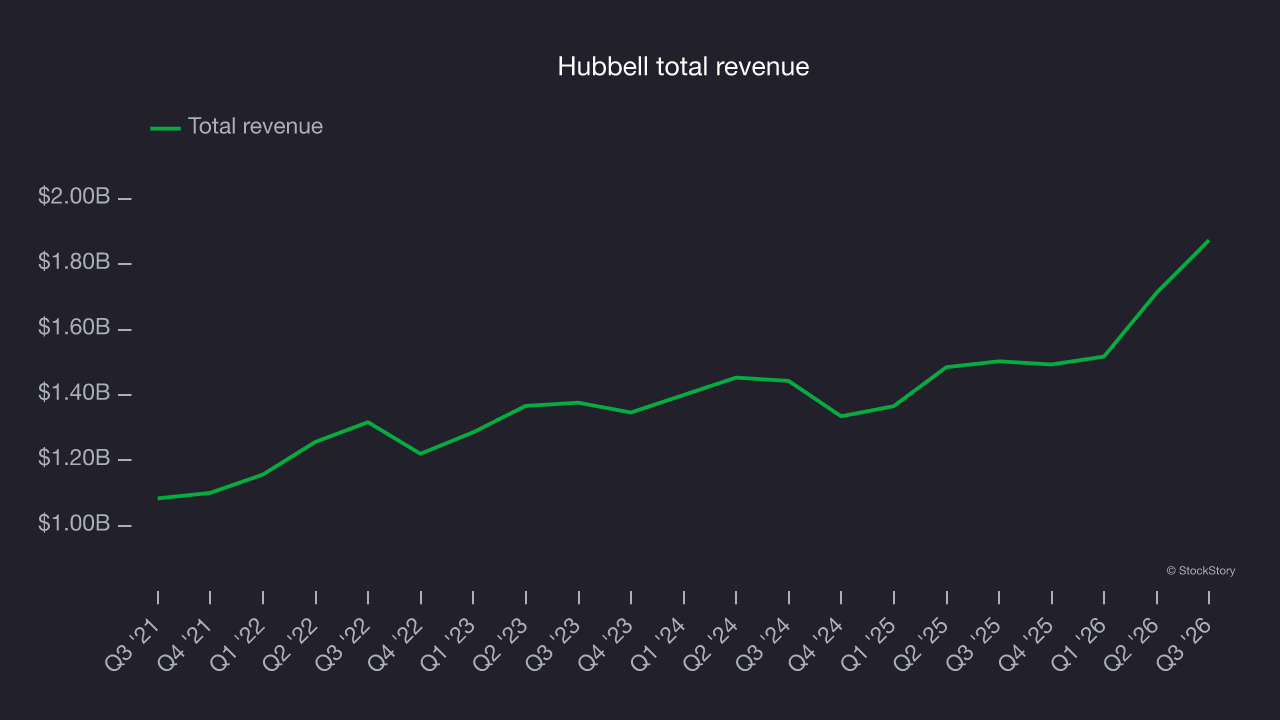
Hubbell reported revenues of $1.87 billion, up 24.6% year on year. This print exceeded analysts’ expectations by 0.7%. Despite the top-line beat, it was still a mixed quarter for the company with a decent beat of analysts’ EBITDA estimates but a slight miss of analysts’ organic revenue estimates.
Mr. Bakker continued, “Third quarter results were highlighted by >20% organic growth in Electrical Solutions, led by strong datacenter markets and bolstered by content gains and capacity expansion investments. NSI results were strong in the quarter, and performance and integration efforts are trending ahead of our initial expectations. Utility Solutions delivered solid organic growth in the quarter, led by distribution, transmission and substation markets. Orders and end market demand remained strong, driving continued backlog build in the quarter, and we remain focused on proactively investing in capacity expansion to serve our customers in high growth areas.”
The market seems disappointed with the results as the stock is down 6.6% since reporting and currently trades at $429.06.
Is now the time to buy Hubbell? Access our full analysis of the earnings results here, it’s free.
Best Q3: Powell (NASDAQ:POWL)
Originally a metal-working shop supporting local petrochemical facilities, Powell (NYSE:POWL) has grown from a small Houston manufacturer to a global provider of electrical systems.
Powell reported revenues of $396.7 million, up 33.1% year on year, outperforming analysts’ expectations by 19.7%. The business had an exceptional quarter with a beat of analysts’ EPS estimates.
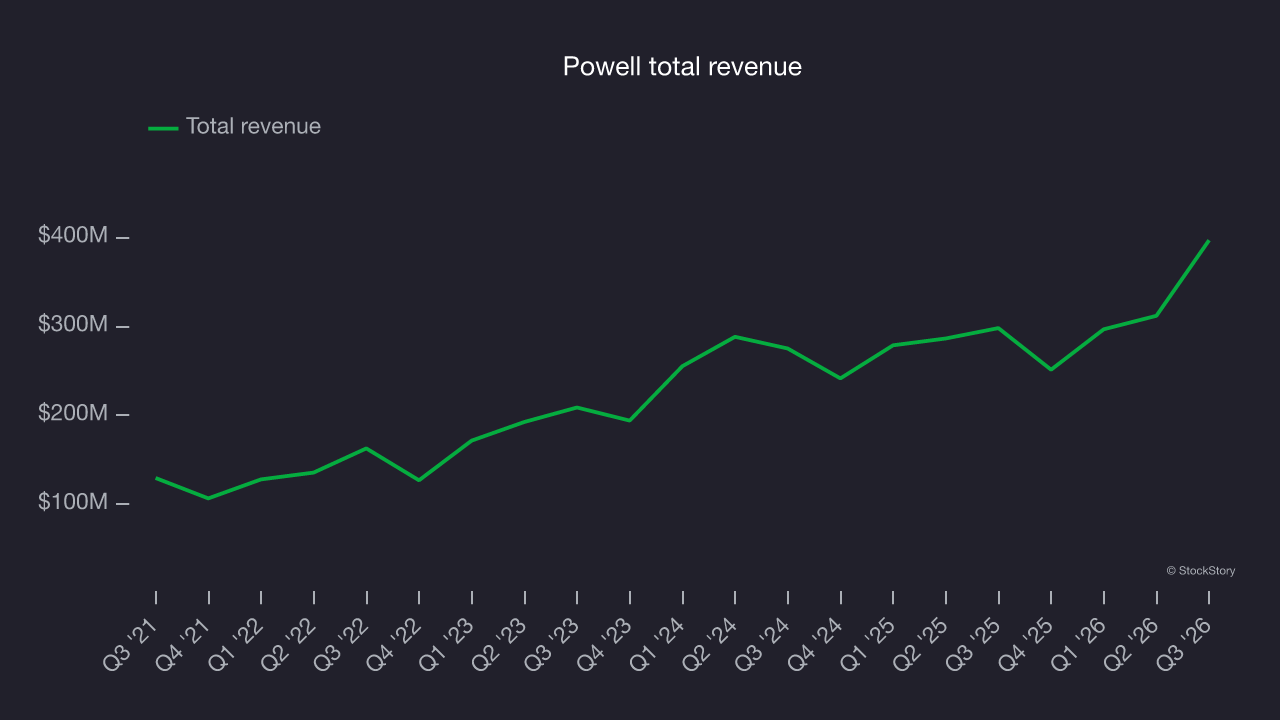
Powell scored the biggest analyst estimate beat in the group. The market seems content with the results as the stock is up 2.8% since reporting. It currently trades at $155.50.
Is now the time to buy Powell? Access our full analysis of the earnings results here, it’s free.
Slowest Q3: Whirlpool (NYSE:WHR)
Credited with introducing the first automatic washing machine, Whirlpool (NYSE:WHR) is a manufacturer of a variety of home appliances.
Whirlpool reported revenues of $3.68 billion, down 8.8% year on year, falling short of analysts’ expectations by 5.9%. It was an underwhelming quarter as it posted full-year EPS guidance missing analysts’ expectations significantly and a significant miss of analysts’ EPS estimates.
Whirlpool delivered the weakest performance against analyst estimates, slowest revenue growth, and weakest full-year guidance update among its peers. The stock is flat since the results and currently trades at $26.57.
Read our full analysis of Whirlpool’s results here.
GE Vernova (NYSE:GEV)
Born from the energy business of industrial giant General Electric in a 2023 spin-off, GE Vernova (NYSE:GEV) designs, manufactures, and services power generation equipment and grid technologies to help customers build more reliable and sustainable electric systems.
GE Vernova reported revenues of $12.64 billion, up 26.8% year on year. This number topped analysts’ expectations by 5.2%. Overall, it was a very strong quarter as it also logged a solid beat of analysts’ EBITDA estimates and full-year revenue guidance slightly topping analysts’ expectations.
The stock is down 12.7% since reporting and currently trades at $781.51.
Read our full, actionable report on GE Vernova here, it’s free.
Allegion (NYSE:ALLE)
Allegion plc (NYSE:ALLE) is a provider of security products and solutions that keep people and assets safe and secure in various environments.
Allegion reported revenues of $1.17 billion, up 9.6% year on year. This print beat analysts’ expectations by 3.3%. It was a very strong quarter as it also put up a solid beat of analysts’ organic revenue estimates and a solid beat of analysts’ EBITDA estimates.
The stock is up 18.2% since reporting and currently trades at $187.88.
Read our full, actionable report on Allegion here, it’s free.
Market update
Over the past year, investors have been forced to repeatedly answer the same question: What is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Growth Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.