


The end of the earnings season is always a good time to take a step back and see who shined (and who didn’t). Let’s take a look at how consumer discretionary - real estate services stocks fared in Q3, starting with Forestar Group NYSE:FOR.
The Consumer Discretionary sector, by definition, is made up of companies selling non-essential goods and services. When economic conditions deteriorate or tastes shift, consumers can easily cut back or eliminate these purchases. For long-term investors with five-year holding periods, this creates a structural challenge: the sector is inherently hit-driven, with low switching costs and fickle customers. As a result, only a handful of companies can reliably grow demand and compound earnings over long periods, which is why our bar is high and High Quality ratings are rare. Real estate services companies provide brokerage, property management, appraisal, and advisory services, earning transaction-based commissions and recurring management fees. Tailwinds include long-term housing demand driven by demographic growth, technology platforms that expand market access, and commercial real estate complexity that sustains advisory needs. Headwinds are pronounced: rising interest rates directly suppress transaction volumes by reducing housing affordability and commercial deal activity. Commission-rate compression, driven by discount brokerages and regulatory changes, erodes per-transaction revenue. The industry is highly cyclical, with revenue swings amplified by leverage. PropTech (property technology) disruptors threaten traditional intermediary models.
The 13 consumer discretionary - real estate services stocks we track reported a softer Q3. As a group, revenues missed analysts’ consensus estimates by 2.1% while next quarter’s revenue guidance was 9.7% below.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 12.8% since the latest earnings results.
Forestar Group NYSE:FOR
As a majority-owned subsidiary of homebuilding giant D.R. Horton, Forestar Group (NYSE:FOR) develops and sells finished residential lots to homebuilders, focusing primarily on land acquisition and development for single-family homes.
Forestar Group reported revenues of $580.8 million, down 13.4% year on year. This print fell short of analysts’ expectations by 4.7%. Overall, it was an underwhelming quarter for the company with full-year revenue guidance missing analysts’ expectations significantly and a significant miss of analysts’ EPS estimates.
Tomnitz concluded, “Our strong balance sheet, experienced teams and broad platform provide us with significant financial and operational flexibility to navigate changing market conditions and capitalize on opportunities for growth. These strengths, combined with our strategic relationship with D.R. Horton and $2.2 billion of contracted future revenue, position us well to continue supplying homebuilders with finished lots and capturing market share. We remain focused on disciplined capital allocation while positioning Forestar for growth and long-term shareholder value.”
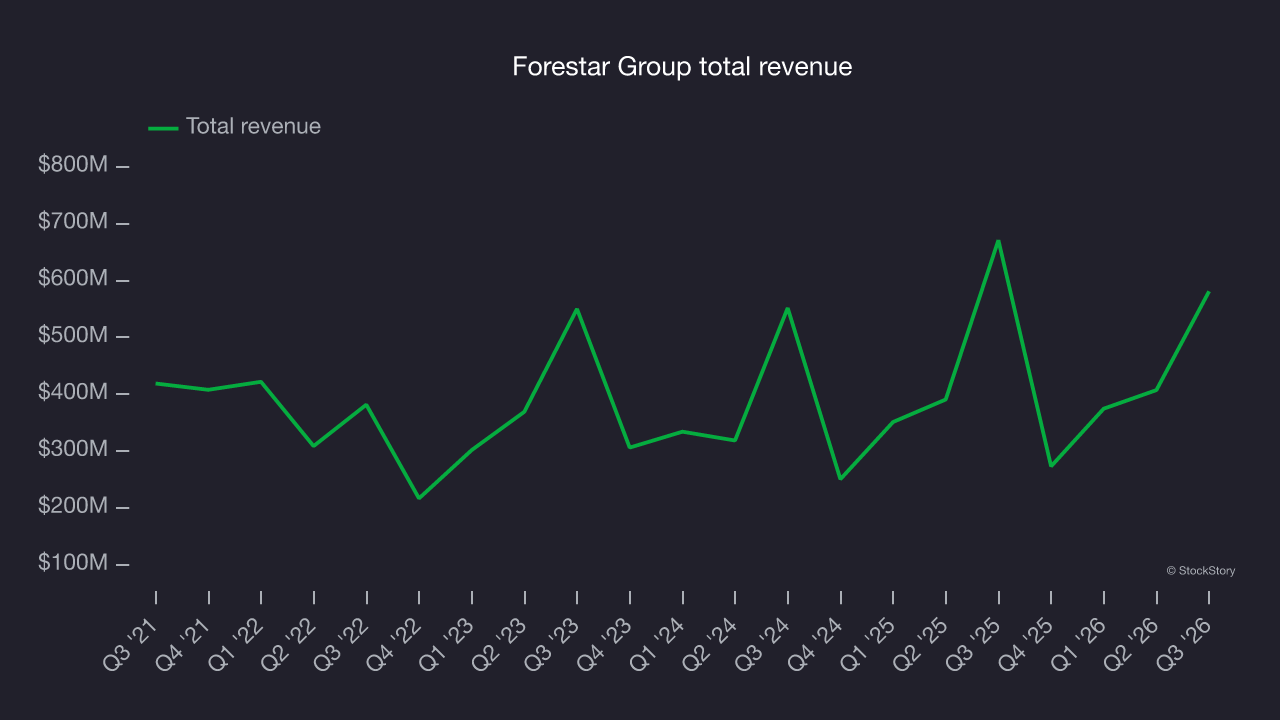
Forestar Group delivered the weakest full-year guidance update among its peers. The market seems disappointed with the results as the stock is down 13.7% since reporting and currently trades at $22.36.
Read our full report on Forestar Group here, it’s free.
Best Q3: The Real Brokerage (NASDAQ:REAX)
Founded in Toronto, Canada in 2014, The Real Brokerage (NASDAQ:REAX) is a technology-driven real estate brokerage firm combining a tech-centric model with an agent-centric philosophy.
The Real Brokerage reported revenues of $727.9 million, up 28% year on year, outperforming analysts’ expectations by 6.4%. The business had a solid quarter with full-year EBITDA guidance exceeding analysts’ expectations and full-year revenue guidance exceeding analysts’ expectations.
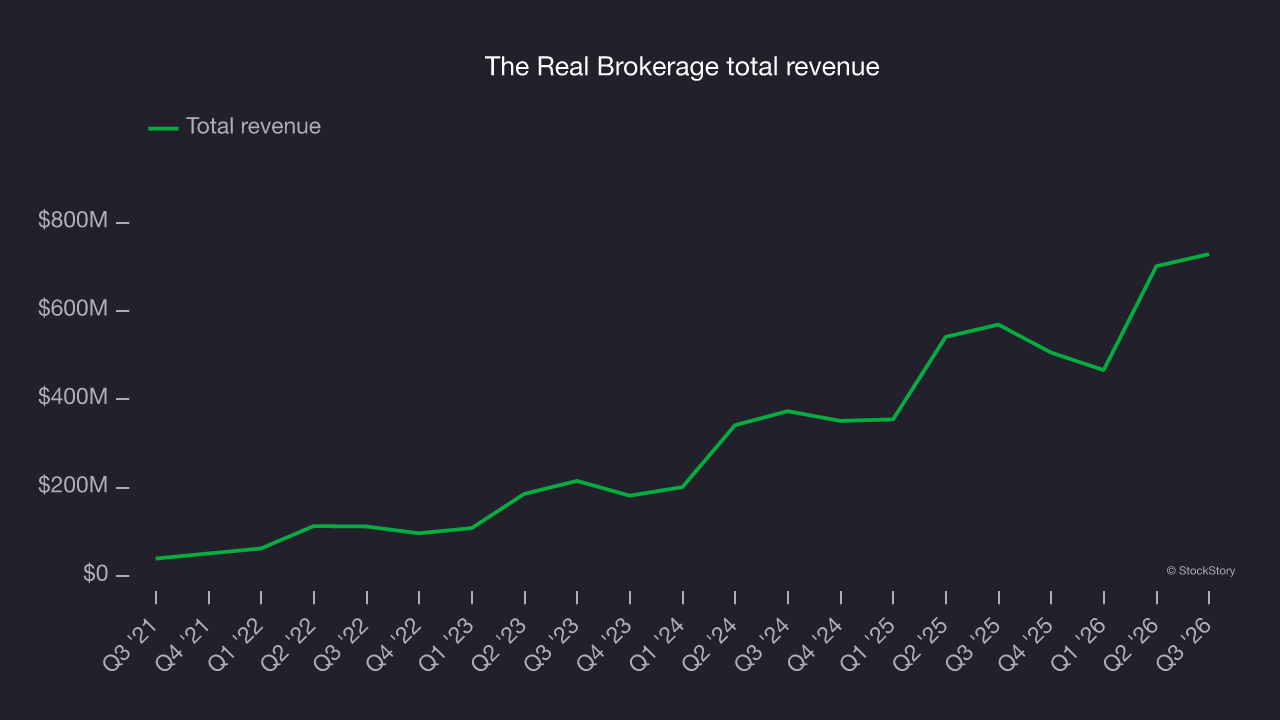
The Real Brokerage delivered the biggest analyst estimate beat, highest guidance raise, and highest full-year guidance raise in the group. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 45.3% since reporting. It currently trades at $9.30.
Is now the time to buy The Real Brokerage? Access our full analysis of the earnings results here, it’s free.
Slowest Q3: Offerpad (NASDAQ:OPAD)
Known for giving homeowners cash offers within 24 hours, Offerpad (NYSE:OPAD) operates a tech-enabled platform specializing in direct home buying and selling solutions.
Offerpad reported revenues of $78.07 million, down 41.2% year on year, falling short of analysts’ expectations by 27.9%. It was an underwhelming quarter as it posted revenue guidance for next quarter missing analysts’ expectations significantly and a significant miss of analysts’ EBITDA estimates.
Offerpad delivered the weakest performance against analyst estimates, weakest guidance update, and slowest revenue growth of the whole group. As expected, the stock is down 24.2% since the results and currently trades at $1.57.
Read our full analysis of Offerpad’s results here.
Marcus & Millichap (NYSE:MMI)
Founded in 1971, Marcus & Millichap (NYSE:MMI) specializes in commercial real estate investment sales, financing, research, and advisory services.
Marcus & Millichap reported revenues of $208.4 million, up 7.5% year on year. This result topped analysts’ expectations by 1.6%. More broadly, it was a mixed quarter as it also logged a solid beat of analysts’ EBITDA estimates but a significant miss of analysts’ EPS estimates.
The stock is down 16.8% since reporting and currently trades at $23.85.
Read our full, actionable report on Marcus & Millichap here, it’s free.
Cushman & Wakefield (NYSE:CWK)
With expertise in the commercial real estate sector, Cushman & Wakefield (NYSE:CWK) is a global Chicago-based real estate firm offering a comprehensive range of services to clients.
Cushman & Wakefield reported revenues of $2.81 billion, up 7.7% year on year. This print surpassed analysts’ expectations by 1.1%. Overall, it was a satisfactory quarter as it also recorded a beat of analysts’ EPS estimates.
The stock is down 3.7% since reporting and currently trades at $13.12.
Read our full, actionable report on Cushman & Wakefield here, it’s free.
Market update
Over the past year, investors have been forced to repeatedly answer the same question: What is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Strong Momentum Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.