


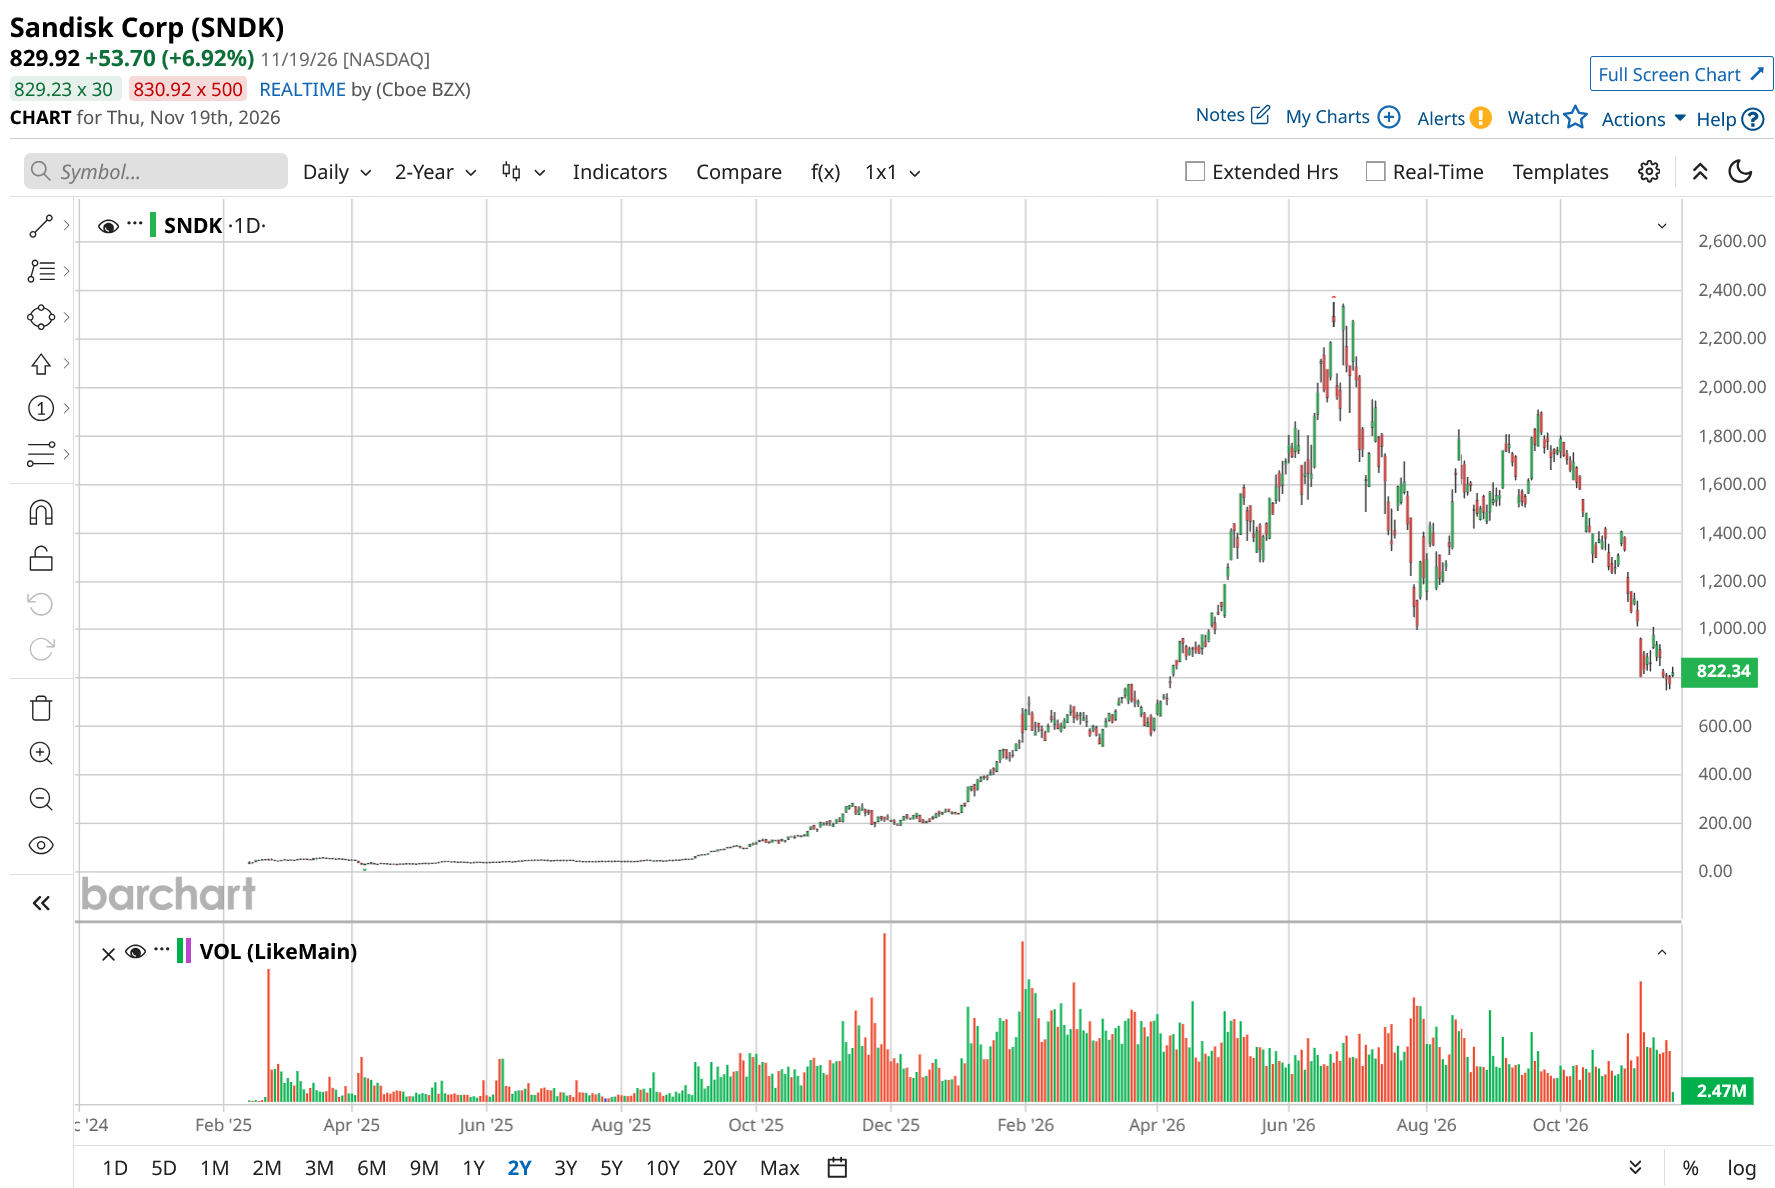
Wall Street loves a comeback story, but few have been as spectacular as Sandisk's (SNDK). Since separating from Western Digital (WDC) in February 2025, the flash-memory specialist has become one of the stock market's biggest winners, rising more than 2,000%, and riding an explosion in artificial intelligence infrastructure spending and soaring memory prices.
Yet the conditions behind that extraordinary rally may be changing. NAND flash prices have started retreating, and industry forecasts suggest more supply could be coming just as demand weakens.
That makes tomorrow, Nov. 20, a particularly interesting date for Sandisk shareholders.
Sandisk's 8-for-1 Stock Split Arrives Tomorrow
Sandisk's much-anticipated 8-for-1 stock split takes effect after today's closing bell, with split-adjusted trading beginning Friday, Nov. 20.
For every share investors own, they'll receive seven additional shares. Someone holding 100 shares today will own 800 tomorrow. Based on Wednesday's $776.22 closing price, each share would be worth approximately $97.03 afterward. Shares are up about 7% this morning to $829.92 in early market trading.
The total investment value doesn't change. A $77,622 position remains worth $77,622, excluding subsequent market movements.
The split follows an extraordinary rally since Western Digital spun off its flash-memory business in February 2025.
Sandisk's operating performance helps explain that enthusiasm. According to its Oct. 29 earnings release, fiscal first-quarter 2027 revenue reached $11 billion, rising 23% sequentially. Net income totaled $8.1 billion, while gross margin reached 85%. Management also forecast second-quarter revenue between $12.2 billion and $12.6 billion.
Those numbers suggest the memory boom is still delivering extraordinary profits. But the next stage could look different.
A Warning Sign for the Memory Boom
Memory prices have historically moved in cycles. Manufacturers expand production to capitalize on strong demand, only to discover that additional supply eventually puts pressure on selling prices. Sandisk could be approaching another turning point.
TrendForce published a new forecast this morning predicting that NAND flash contract prices, which are expected to rise 8% to 13% in the fourth quarter, will decline between 0% and 5% in both the first and second quarters of 2027.
More troubling, NAND spot prices have already corrected more than 20%.
TrendForce expects global NAND bit supply to increase 25% to 30% next year, supported by $29.9 billion in industry capital expenditures. Meanwhile, Chinese cloud providers are reducing enterprise SSD orders enough to offset additional demand from North American customers.
That's a potentially uncomfortable combination: more memory chips competing for fewer incremental orders.
The risk is particularly relevant to Sandisk because, unlike Micron Technology (MU), which also produces DRAM and high-bandwidth memory, Sandisk concentrates on NAND flash and related storage products.
Falling NAND prices could therefore pressure Sandisk's margins even if AI infrastructure spending continues growing.
What SNDK Investors Should Watch Next
Granted, falling spot prices don't immediately translate into lower contract revenue. Sandisk's latest results demonstrate that its customers are still paying premium prices, while its 85% gross margin provides room to absorb some pricing pressure. And strong AI demand could keep the industry tighter than TrendForce anticipates.
Still, investors should remember that Sandisk's remarkable rally has depended heavily on favorable NAND pricing. If prices reverse while manufacturers continue expanding production, the earnings outlook could change quickly.
That makes the next several quarters more consequential than tomorrow's split. Investors should watch whether Sandisk maintains its revenue guidance, whether gross margins begin narrowing, and whether TrendForce's anticipated oversupply actually develops.
The Bottom Line
Sandisk's 8-for-1 split makes its shares more accessible, but it doesn't make the underlying business more valuable. The company is generating record profits, yet the first signs of another NAND pricing downturn are appearing just as manufacturers prepare to increase supply.
For shareholders, Nov. 20 marks an exciting milestone. But the more important date may be early 2027, when Sandisk's extraordinary memory boom faces its first real test.
On the date of publication, Rich Duprey did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.