

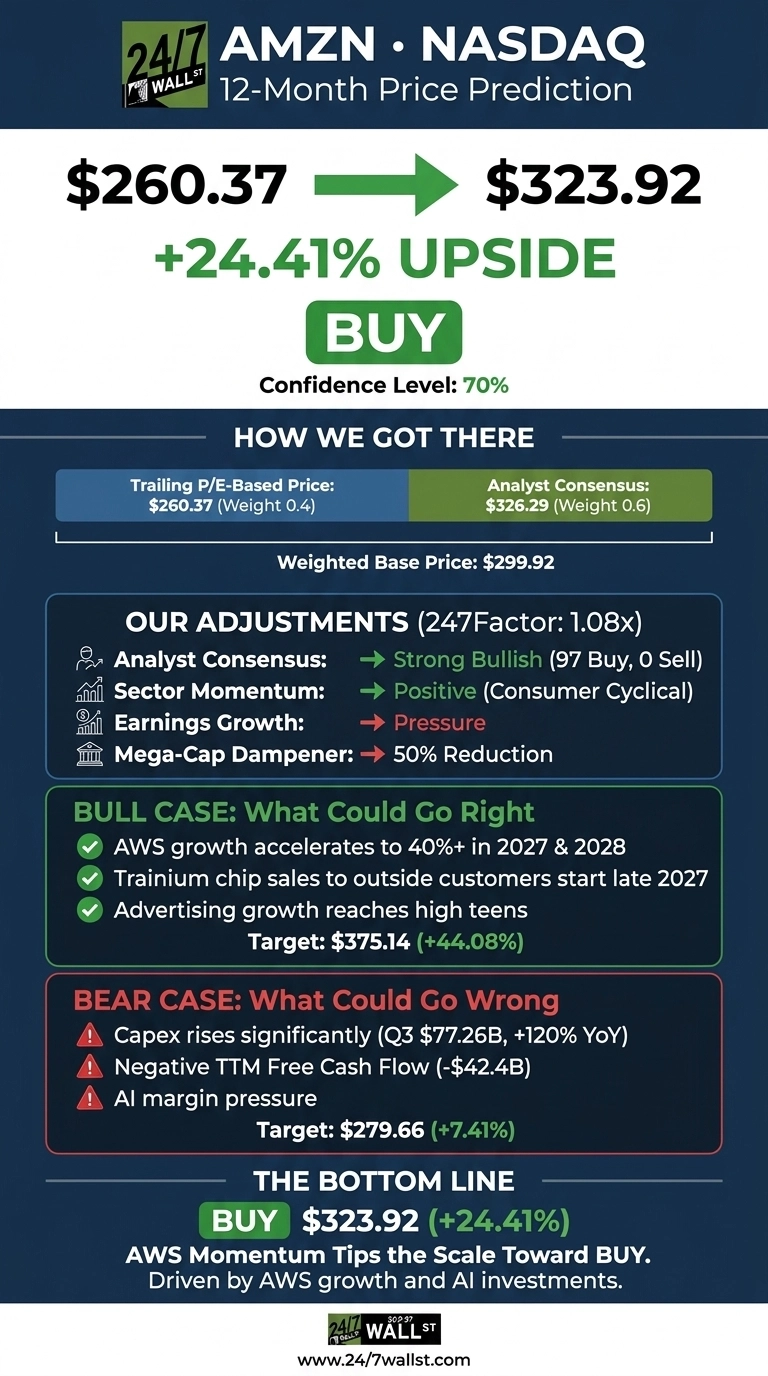
The 24/7 Wall St. price target for Amazon (NASDAQ:AMZN) is $323.92 over the next 12 months. That means 24.41% upside from the model’s reference price of $260.37.
 24/7 Wall St.
 Price Target Summary Metric Value Current Price $260.37 Price Target from 24/7 Wall St. $323.92 Upside/Downside 24.41% Recommendation BUY Confidence Level 70%
Amazon earns a buy rating from the model with fairly high confidence. AWS drives most of that view. It grew 39% last quarter, its fastest rate in nearly five years, and management expects growth above 40% in both 2027 and 2028.
Our five-year base case reaches $496.74, which works out to 13.79% a year. Meanwhile, NVIDIA (NASDAQ:NVDA) is down 15.84% year to date.
A Record Operating Margin Hidden Behind a Narrow MissAmazon trades at $257.06 in premarket trading. Shares are down 3.7% over the past week, up 2.82% over the past month, down 1.36% over the past quarter and up 11.37% year to date. The 52-week range runs from $196 to $287.20. Barron’s argued on Monday that Amazon has the best-looking chart in the Magnificent Seven (Barron’s).
Third-quarter revenue of $201.94 billion missed the $202.20 billion consensus. EPS of $1.89 also missed expectations of $1.9579. The rest of the report was firmer.
Operating income rose 61.15% to $28.08 billion, and the 13.9% operating margin was the highest Amazon has ever reported. Management said the Prime Day calendar shift cut retail growth by about 400 bps.
Why Bulls See $375 and BeyondBullish projections point to $375.14 in a year and $610.71 in five. AWS has a $578 billion backlog, and Bedrock token volume grew nearly 17x. Amazon plans to start selling Trainium chips to outside customers in late 2027, which would put it in more direct competition with NVIDIA.
Advertising growth is expected to the high teens in Q4. Analysts are mostly bullish: 16 Strong Buy and 43 Buy ratings against 2 Holds, with a consensus target of $326.29.
Capex Bills Are the Risk Worth WatchingThird-quarter capex rose 120% to $77.26 billion. Trailing free cash outflow reached $42.4 billion, and management plans to spend meaningfully more in 2027. On the call, CFO Brian Olsavsky warned that AI “puts margin pressure on the business as a whole because the margins are lower there.”
Net income fell 2.37%, but the prior-year quarter included $9.5 billion in Anthropic gains, and operating cash flow rose 19.4%. Even the bearish scenario still lands at $279.66 in a year, above today’s price.
How Amazon Stacks Up Against NVIDIA, Microsoft and Alphabet Company Trailing P/E Cloud/AI Segment Growth Amazon 36x AWS 39% NVIDIA 31x Data Center 117% Microsoft 29x Azure 48% Alphabet 13x Google Cloud 103%NVIDIA is the benchmark in our headline. Over five years it returned 437.53%, compared with 44.86% for Amazon. Over the past month, though, it fell 26.87%. AWS is also an NVIDIA customer: it is rolling out an additional 2 million GPUs, so Amazon earns revenue from AI demand either way (we profiled seven of the non-chip suppliers driving that same expansion in a free report).
Microsoft (NASDAQ:MSFT) is Amazon’s closest hyperscaler rival. Azure is growing faster than AWS, and Microsoft holds $677 billion in commercial remaining performance obligations, yet it trades at a lower multiple.
Alphabet (NASDAQ:GOOGL) looks cheap at 13x. That multiple is distorted, however, because a $99 billion equity gain in Q2 inflated trailing earnings. On these numbers, Amazon trades at a premium to its peers. Since our 24/7 Wall St. price target sits just below the analyst consensus, the peer group makes it look reasonable.
AWS Momentum Tips the Scale Toward BUYThe 24/7 Wall St. price target of $323.92 has a buy rating at 70% confidence. AWS acceleration is what tips the balance.
That outlook improves if AWS keeps growing above 40% and Trainium sales outside AWS begin on schedule. It weakens if capex keeps going up while free cash flow stays negative into 2028.
Here is where our model projects Amazon could trade going forward, assuming current growth trends and market conditions hold.
Year Price Target from 24/7 Wall St. 2026 $323.92 2027 $331.70 2028 $384.12 2029 $429.52 2030 $463.24Amazon would need to keep executing its current AWS strategy for these projections to hold. Results could beat them if Trainium becomes a large business with outside customers, or fall short if AI margins and capex payback disappoint.