

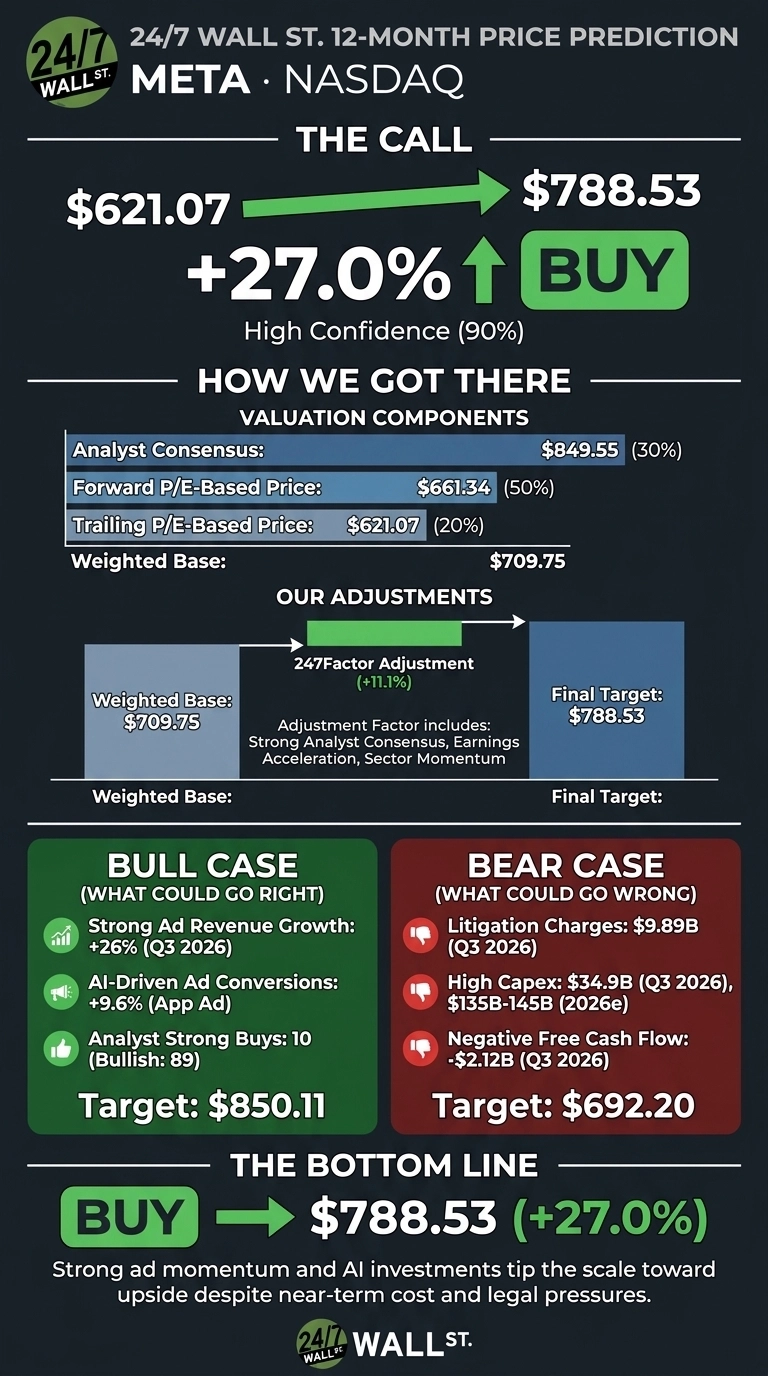
The 24/7 Wall St. price target for Meta Platforms (NASDAQ:META) is $788.53. The target means 26.96% upside from $621.07. The stock earns a buy rating from our model with high confidence.
 24/7 Wall St.
 Price Target Summary Metric Value Current Price $621.07 Price Target from 24/7 Wall St. $788.53 Upside/Downside 26.96% Recommendation BUY Confidence Level 90%
Meta’s advertising engine keeps beating revenue forecasts, while one-time charges have distorted earnings per share.
Fourth-quarter revenue guidance of $73 billion to $76 billion is well above third-quarter revenue of $64.60 billion. Easier comparisons could turn recent EPS misses back into beats.
A Litigation Charge Hid a Strong Ad QuarterOver the past month the stock has fallen 12.84%. It is down 6.11% year to date, which leaves it about 20.4% below its $779.82 52-week high.
Third-quarter revenue rose 26.07% and beat the $63.39 billion consensus. GAAP EPS of $3.83 missed expectations because of a $9.89 billion charge for the settlement with state attorneys general over teen mental health claims. Without that charge, EPS would have been $7.40.
Advertising revenue climbed 26% to $63.06 billion. Ad impressions grew 10% and the average price per ad rose 14%. Jim Cramer said in September, “This teen abuse lawsuit could have been an existential threat to Meta.” The settlement turned that threat into a known cost.
Why Bulls See $850 Within ReachThe bull case rests on AI making Meta’s ads work better. Meta’s JEM ranking model raised app ad conversions by 9.6%. Nearly 10 million advertisers used generative AI creative tools, and partnership ads passed a $15 billion annual revenue run rate.
On the October call, the CFO, Susan Li, said Meta is set “to sustain strong overall revenue growth throughout 2027.” Analysts lean heavily bullish. There are 10 strong buys and 46 buys, against 6 holds and 1 sell. Our bull case reaches $850.11.
Spending and Lawsuits Could Cap GainsThird-quarter capital spending reached $34.91 billion, and free cash flow fell to -$2.12 billion. Meta expects 2026 capex of $135 billion to $145 billion, the kind of data-center outlay that feeds a whole chain of infrastructure vendors (we rounded up seven of them in a free report on the AI infrastructure buildout).
More youth-related trials are scheduled. The bear case of $692.20 still is above today’s price. On the other side, operating income would have grown 11% without the legal charge. Meta’s Muse models also cut content-processing costs by more than 80%.
Meta Versus Alphabet and PinterestAlphabet (NASDAQ:GOOGL) is Meta’s closest rival in digital ads. Alphabet trades at 12x earnings, compared with Meta’s 21x. However, Alphabet’s Search revenue grew only 12%. A one-time equity loss of $8.7 billion also distorted Alphabet’s EPS, a pattern similar to Meta’s.
Pinterest (NYSE:PINS) is a pure-play social advertising company. It grew revenue just 11.89%, and its European revenue was flat.
Company Q3 Revenue Growth Q3 EPS Surprise Meta 26.07% -32.79% Alphabet 24.65% -28.52% Pinterest 11.89% -5.23%Meta’s faster ad growth supports its premium multiple. Compared with these peers, our 18x forward anchor looks reasonable.
Ad Momentum Tips the Scale Toward UpsideThe 24/7 Wall St. price target of $788.53 carries a buy rating at 90% confidence. What tips the scale is an ad business growing 26% while one-time charges hide its real earnings power.
Fourth-quarter revenue landing within guidance and capex starting to produce positive free cash flow would strengthen the outlook. It gets weaker if youth trials bring new charges or growth in ad pricing stalls. Keep an eye on whether Meta’s ad business drives another earnings surprise.
If current growth and market conditions hold, the 24/7 Wall St. price target model projects the following prices for Meta.
Year Price Target from 24/7 Wall St. 2026 $618.42 2027 $787.05 2028 $926.75 2029 $1,047.18 2030 $1,164.53This forecast rests on Meta maintaining its current strategy. Making money from Muse could add significant upside, while further litigation or capex overruns could pull the stock lower.