


Canadian Natural Resources has delivered a powerful 5 year share price run, and with fresh deal news in play, the live question for investors is whether the current valuation is still adequately backed by its earnings power.
- The stock has returned 204.2% over the past 5 years, which puts a lot of weight on the idea that its profit engine can keep justifying a much higher price than in the past.
- The agreed C$2.53b all cash purchase of Advantage Energy may support future production and earnings, but it also adds capital commitments that matter when you line the share price up against the income statement.
- There is a second opinion on Canadian Natural Resources worth weighing. See what analysts think Canadian Natural Resources's shares could be worth.
For investors, the debate is whether Canadian Natural Resources' current share price, after this run and recent acquisition plans, still lines up with what its earnings suggest is reasonable.
If you want to pressure test Canadian Natural Resources' earnings based valuation debate against other candidates on your watchlist, compare it with 2 high quality undervalued stocks.
Is Canadian Natural Resources Still Cheap on Earnings?
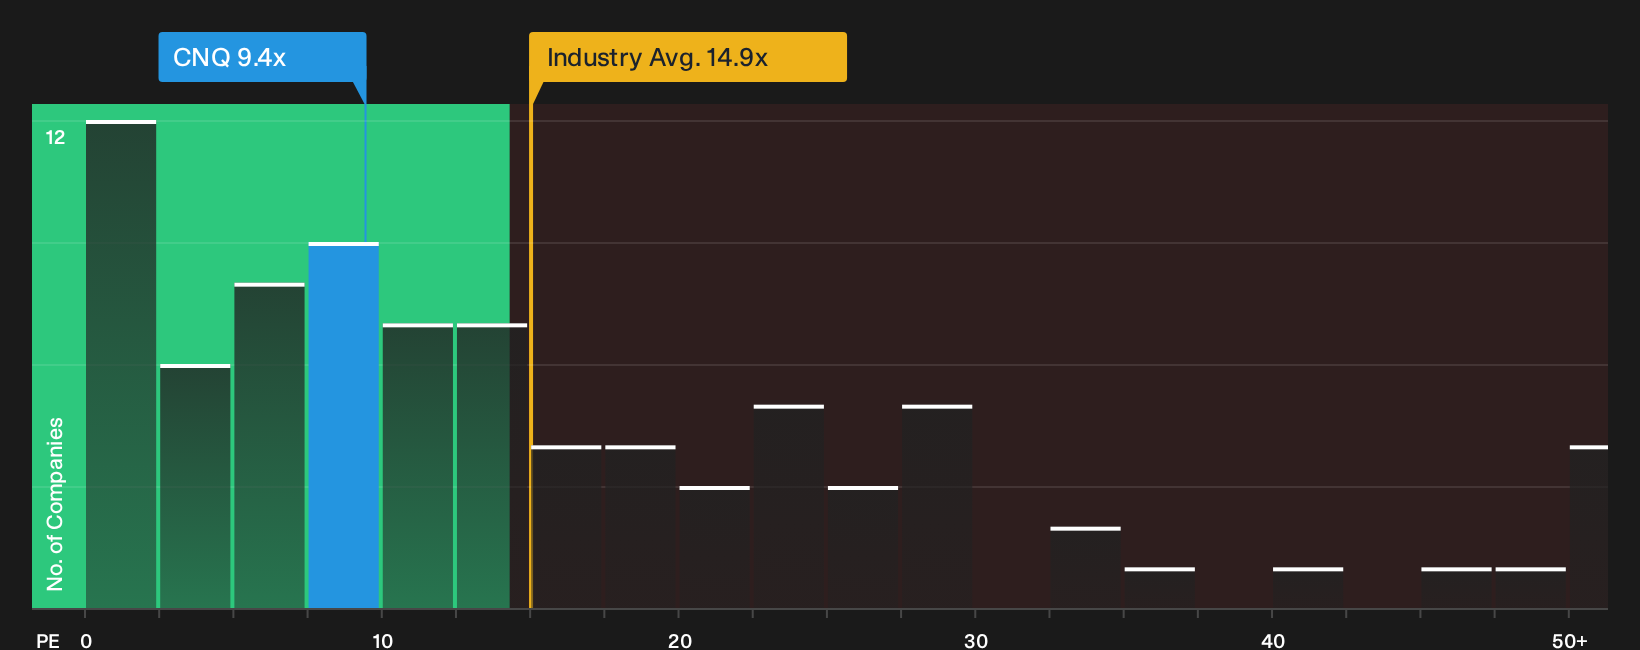
The P/E ratio fits Canadian Natural Resources because profit is a key lens for a mature producer where earnings do a lot of the heavy lifting. On this yardstick, the stock trades at about 9.4x earnings, which is well below the oil and gas industry average of roughly 14.9x and under the broader peer group at around 21.1x.
Because the tailored fair multiple for Canadian Natural Resources sits above the current 9.4x level, the market price screens as undervalued relative to what that model suggests would be typical for its mix of size, margins and risk. The recent C$2.53b Advantage Energy deal has put growth plans back in focus, yet the earnings multiple still prices the shares at a discount to that fair benchmark and to many peers. Explore the numbers behind Canadian Natural Resources's P/E valuation.
The Canadian Natural Resources Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Canadian Natural Resources valuation question leaves off by spelling out which future paths for growth, margins and earnings would need to play out for the shares to look materially richer or cheaper than today. Rather than lean on a single P/E or model line, each narrative lays out its own set of assumptions for Canadian Natural Resources' value so you can later compare those expectations with the reported numbers.
Bulls and bears are both focused on cash generation at Canadian Natural Resources, but they draw very different conclusions about how much is already priced in.
Bull case: 13% undervalued
The analyst consensus Narrative on Simply Wall St argues the long life asset base and capital return policy are not fully reflected yet.
"The updated free cash flow allocation policy, which now directs 75% of free cash flow to shareholders once net debt falls below $16b and 100% once it reaches $13b, sets up a framework in which future cash generation is increasingly tied to dividends and buybacks…"
Discover why this Narrative puts Canadian Natural Resources at 13% undervalued.
Bear case: roughly fairly valued
The bearish analyst Narrative on Simply Wall St leans on paused growth projects and sensitivity to weaker cash generation.
"While Canadian Natural Resources has moved to direct 100% of free cash flow to shareholder returns after net debt fell to about $12.1b, any period of weaker cash generation would still require the company to meet explicit buyback targets…"
Explore why this Narrative puts Canadian Natural Resources at roughly fairly valued.
One more angle on Canadian Natural Resources that could change the picture
Numbers only tell part of the story for Canadian Natural Resources, because the people setting priorities and how they are rewarded can heavily shape what happens next. See who runs Canadian Natural Resources and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com