

Dell Technologies (NYSE:DELL) has had a breakout 2026. Shares are up 165.55% year to date as AI servers moved from a side business to the center of Dell’s revenue.
The run has been volatile. The stock fell 26.68% over the past month, and the current price of $330.75 stands far below the 52-week high of $594.69. Barron’s even ran a “time to sell” call this week. Below, I lay out how Dell could still hit $600 per share in 2027.
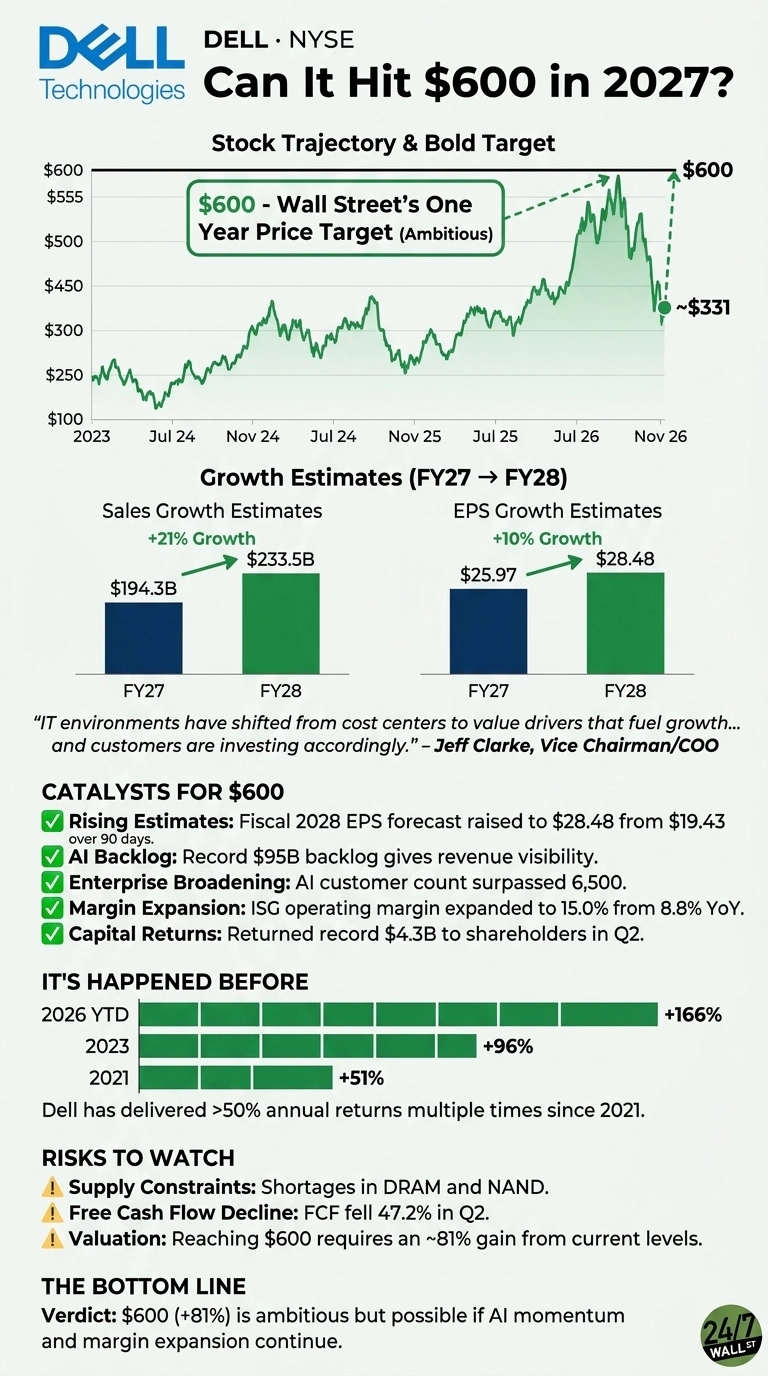
The business case starts with demand. In fiscal Q2, Dell booked a record $60.9 billion in AI orders and ended the quarter with a $95 billion backlog. Jeff Clarke put it this way: “IT environments have shifted from cost centers to value drivers that fuel growth and competitive advantage, and customers are investing accordingly.”
Wall Street Already Sees Big Upside for DellThe consensus 1-year target is $583.68, which implies 76% upside. Analysts expect fiscal 2027 revenue of about $194.3 billion, and that figure climbs to $233.5 billion for fiscal 2028, the year that covers most of calendar 2027.
Estimates are also rising. Ninety days ago, the fiscal 2028 EPS forecast was $19.4275. Today it is $28.4833.
 24/7 Wall St. Here’s What It Takes for Dell to Reach $600
At $330.75, Dell trades at roughly 12x fiscal 2028 earnings estimates. At $600, the multiple would be about 21x, which still looks reasonable for a company guiding to 148% non-GAAP EPS growth this year. Getting there mostly requires the market to give back the valuation it took away this fall.
Several factors could push Dell to $600.
- Earnings beat run: Dell has exceeded EPS estimates five straight quarters, including a 43.69% surprise in fiscal Q2. If that pattern holds, current forecasts are probably too low.
- Raised guidance: Management lifted fiscal 2027 revenue guidance to $192 billion, with AI server revenue of $74 billion.
- Enterprise broadening: AI customers have passed 6,500, and management said “the acceleration is enterprise.”
- Margin expansion: ISG operating margin expanded to 15% from 8.8%, and traditional servers grew 122%.
- Product leadership: Dell was “the first to ship RAC systems engineered on the NVIDIA Vera Rubin platform.”
- Capital returns: Dell returned a record $4.3 billion to shareholders in Q2.
Among the key challenges are supply constraints in DRAM and NAND, along with free cash flow that fell 47.2% in Q2.
Dell’s Track Record Says $600 Is Within ReachReaching $600 requires a gain of about 81%. Dell has done that recently.
In 2023, shares returned about 96%, and the 2026 gain of 165.55% is even larger. In 2024 and 2021, Dell gained roughly 56% and 51%. A $600 price would also sit less than 1% above the 52-week high, so the stock has already traded near that level.
$600 Is a Stretch, but the Blueprint ExistsReaching $600 would mean an 81% gain in 2027. Analysts already expect 76% upside, EPS estimates keep rising and the $95 billion backlog gives Dell revenue visibility.
If supply eases and the beat run continues, a return to a higher earnings multiple gets Dell there. Returns this large are rare, and this is the guide for how Dell could deliver outsized gains in 2027.