


Recent news from Norwegian Cruise Line Holdings (NCLH) caught my attention yesterday.
The cruise operator said that it would cut Halifax from 17 of the 21 summer visits for the Norwegian Breakaway, opting to spend an extra day in Bermuda. The company said it made the changes based on passenger feedback.
I live in Halifax, and while I’m not happy about the news, plenty of cruises are coming to my town next summer and fall. The Port of Halifax will be just fine.
However, I already view NCLH stock negatively relative to its peers. This will not help its cause.
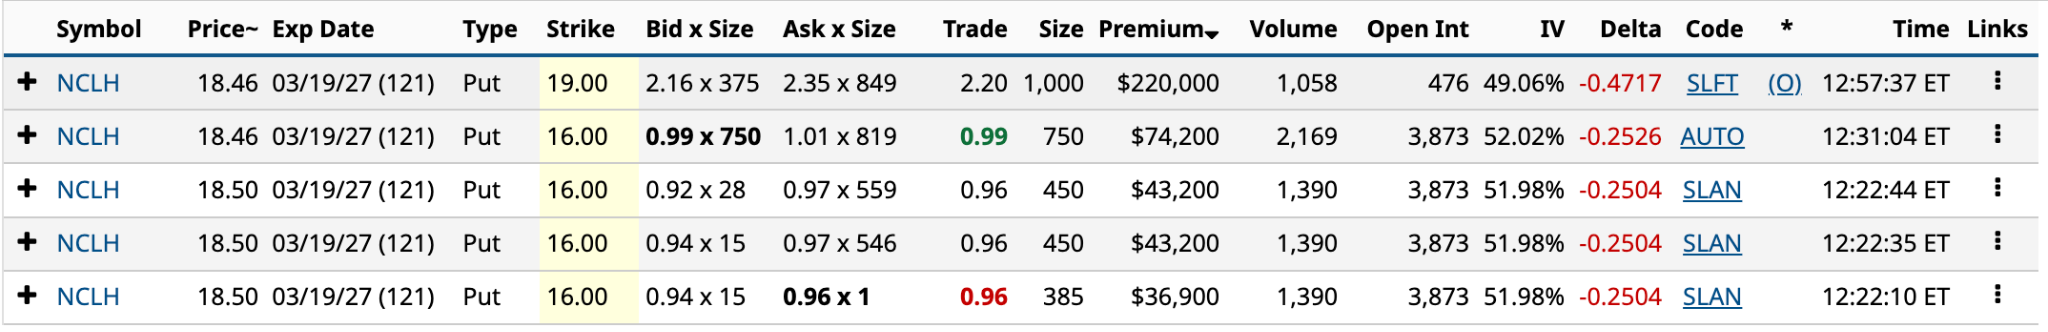
As a result of yesterday’s news, my focus for today’s unusual options activity lands on NCLH. In Wednesday’s trading, the stock had total options volume of 24,091, slightly higher than the 30-day average, with two unusually active options accounting for about 17%.
A close look at the two options’ options flow doesn’t point to any particular trade, bullish or bearish, but I’ll consider three possible options strategies anyway.
Here goes.
The NCLH Options in Question

As I said, NCLH had two unusually active options yesterday. A March 19/2027 $23 call and a March 19/2027 $19 put with a combined volume of 4,144. The call is OTM (out of the money), while the put is ITM (in the money). The former’s new volume is significantly higher, as the Vol/OI (volume-to-open-interest) points out.
Looking at the options flow, there were five trades of 100 contracts or more expiring in 121 days. All were puts. The largest single trade was 1,000 contracts for the $19 strike.
If You’re Bearish
If you’re bearish about NCLH, as I am, you might consider a Bearish Risk Reversal, which involves buying the March 19/2027 $19 ITM put at $2.30 per share (I’m using the latest prices to keep it simple) and selling the OTM March 19/2027 $23 call for $0.64 in premium for a $1.66 per share net debit [$2.30 put price - $0.64 call premium].
In this trade, you make money below the $17.34 breakeven [$19 strike price - $1.66 net debit] down to $0, where your maximum profit would be $17.34 per share, or $1,734. The call expires worthless.
The problem is that the maximum loss is unlimited. So, if the share price jumps to $40 at expiration in March, the loss would be $18.66 per share [$40 share price - $23 + $1.66 net debit]. The put expires worthless.
Given the chances of the war in Iran restarting and pushing oil prices higher—one of the cruise line's higher costs—the likelihood of the share price jumping to $40 is lower today than it has been in some time. The expected move over the next 121 days is 18.13%. At yesterday's last trade price of $17.99, the upper price at expiration would be $21.25, well below the $23 strike price.
If You’re Bullish
If you’re bullish, you would do the opposite by executing a Bullish Risk Reversal, selling the $19 put and buying the $23 call for a net credit of $1.66 per share [$2.30 put premium - $0.64 call price].
Based on the 18.13% expected move, the share price on the downside at expiration would be $14.73. That would result in a $2.61 per-share loss [$19 put strike price - $1.66 net credit - $14.73 share price] and likely assignment.
However, the risk for this trade is moderate relative to the bearish risk reversal because the maximum loss is capped at $17.34 per share [$19 strike price - $0 share price - $1.66 net credit] should the share price fall to $0.
But let’s say the Iran war doesn’t restart over the next 17 weeks and NCLH’s share price jumps to $40 at expiration. That would produce a $18.66 per share profit [$40 share price - $23 strike price + $1.66 net credit]. And that profit is uncapped.
If You’re Neither
If you expect NCLH to remain range-bound or rise slightly over the next 121 days, the options strategy to use would be a Skewed Short Strangle, which involves selling the $19 put for $2.30 per share premium and selling the $23 call for $0.64 per share premium, for a net credit of $2.94.
The skewed short strangle differs from the standard Short Strangle, which is typically directionally neutral with similar deltas near zero for both the call and put, in that one delta skews (hence the name) higher depending on whether you’re bullish or bearish.
Based on the $23 long call, the delta is 0.2312, and the $19 long put’s delta is -0.5142. Because you’re short, you flip the deltas to -0.2312 for the $23 call and 0.5142 for the $19 put. That gives us a net delta of 0.2830, which skews slightly bullish and is the equivalent of holding 28 NCLH shares.
The maximum profit for this trade is the net credit of $2.94 per share. That would happen if the share price at expiration is between $19 and $23, where both options expire worthless. You make money, just not the maximum profit, if the share price is between $19 and $16.06 on the downside at expiration and between $23 and $25.94 on the upside. You begin to lose money below $16.06 and above $25.94.
Since I’m slightly bearish on NCLH, I’d lean toward a bearish risk reversal, although the skewed short strangle has the lowest risk profile of the three.
On the date of publication, Will Ashworth did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.