


Electronic measurement provider Keysight (NYSE:KEYS) reported calendar Q3 2026 [fiscal Q4 2026] results exceeding the market’s revenue expectations, with revenue up 40.5% year on year to $1.99 billion. In addition, next quarter’s revenue guidance ($2.05 billion at the midpoint) was surprisingly strong, coming in 5.8% above analysts’ consensus estimates. Its non-GAAP profit of $3.61 per share was 6.8% above analysts’ consensus estimates.
For more on Keysight, read the full research report, available free.
Keysight Q3 CY2026 highlights:
- Revenue $1.99 billion vs S&P consensus estimates of $1.95 billion (40.5% year-on-year growth, 2.4% beat)
- Adjusted EPS $3.61 vs S&P consensus estimates of $3.38 (6.8% beat)
- Revenue guidance $2.05 billion at the midpoint for Q4 CY2026, above analysts’ consensus estimates of $1.94 billion
- Adjusted EPS guidance $3.66 at the midpoint for Q4 CY2026, above analysts’ consensus estimates of $3.25
- Operating margin 29.4%, up from 15.3% in the same quarter last year
- Free cash flow margin 23.3%, up from 13.2% in the same quarter last year
- Market capitalization $48.74 billion
"Keysight delivered the strongest year in the company’s history, with robust order and revenue growth and significant earnings per share expansion,” said Satish Dhanasekaran, Keysight’s President and CEO. “As we look ahead, the investments we have made to differentiate our portfolio position us to deliver growth and outperform our markets in fiscal 2027.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Even a weak business can perform well for one or two quarters, but a high-quality one grows for years. Keysight’s 7.7% annualized revenue growth over the last five years was favorable. Its growth outpaced that of the average industrials company and shows its offerings resonate with customers.
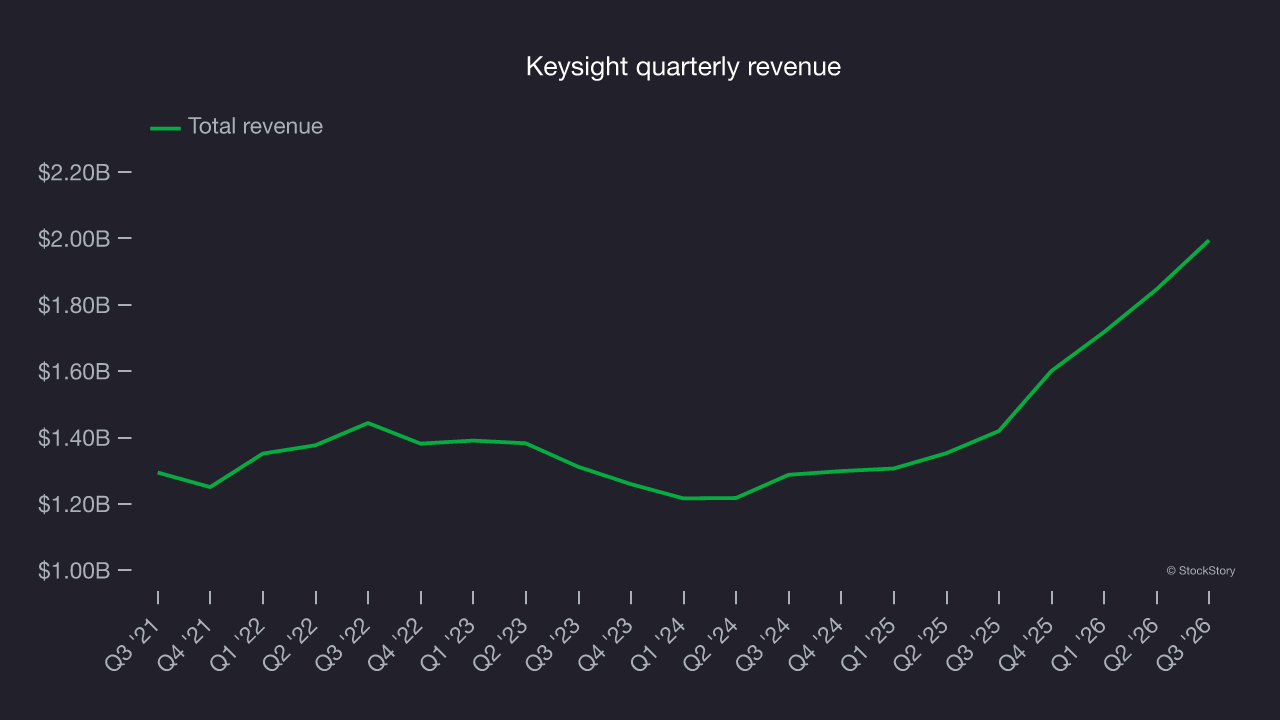
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Keysight’s annualized revenue growth of 19.9% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 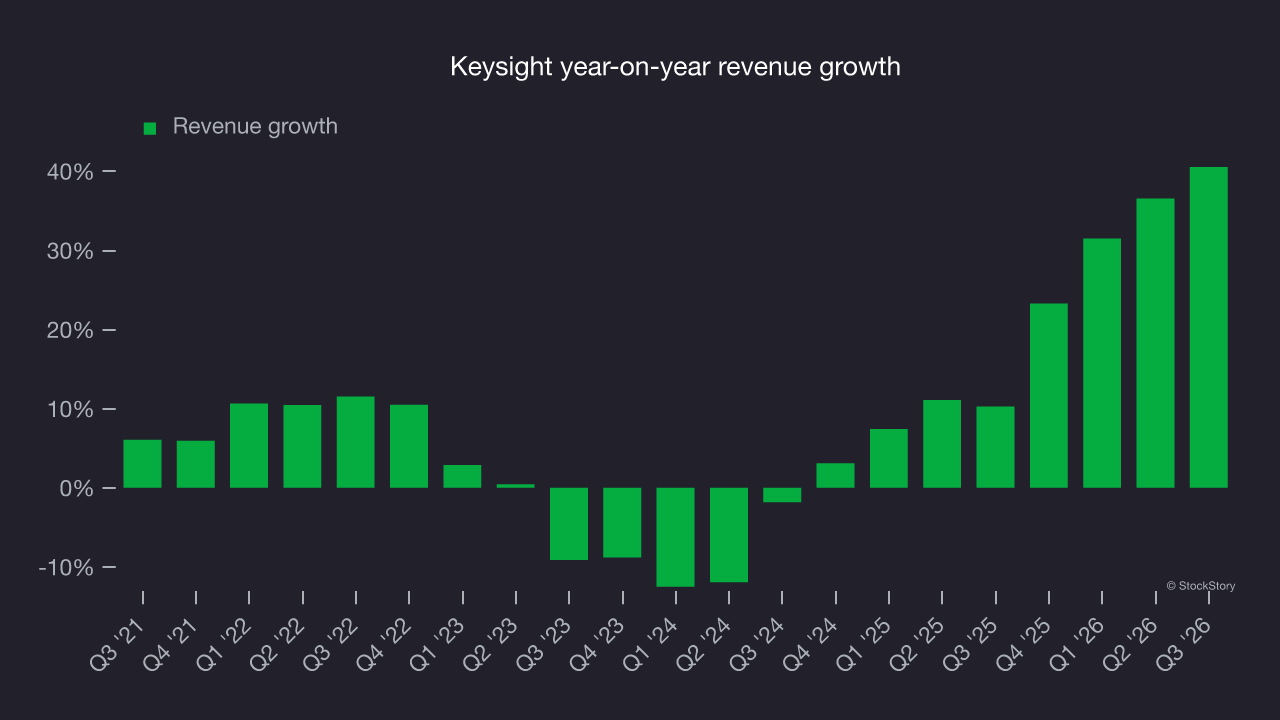
This quarter, Keysight reported strong year-on-year revenue growth of 40.5%, and its $1.99 billion of revenue beat Wall Street’s consensus estimates by 2.4%. Company management is guiding for a 28.1% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 13.7% over the next 12 months, according to S&P, a deceleration versus the last two years. Still, this projection is strong and indicates the market expects success for its products and services.
Operating margin
Keysight’s operating margin was broadly unchanged over the last five years. Its costs have broadly tracked its revenue, leaving its long-term profitability largely unchanged. Its trailing 12-month operating margin was 23.8%.
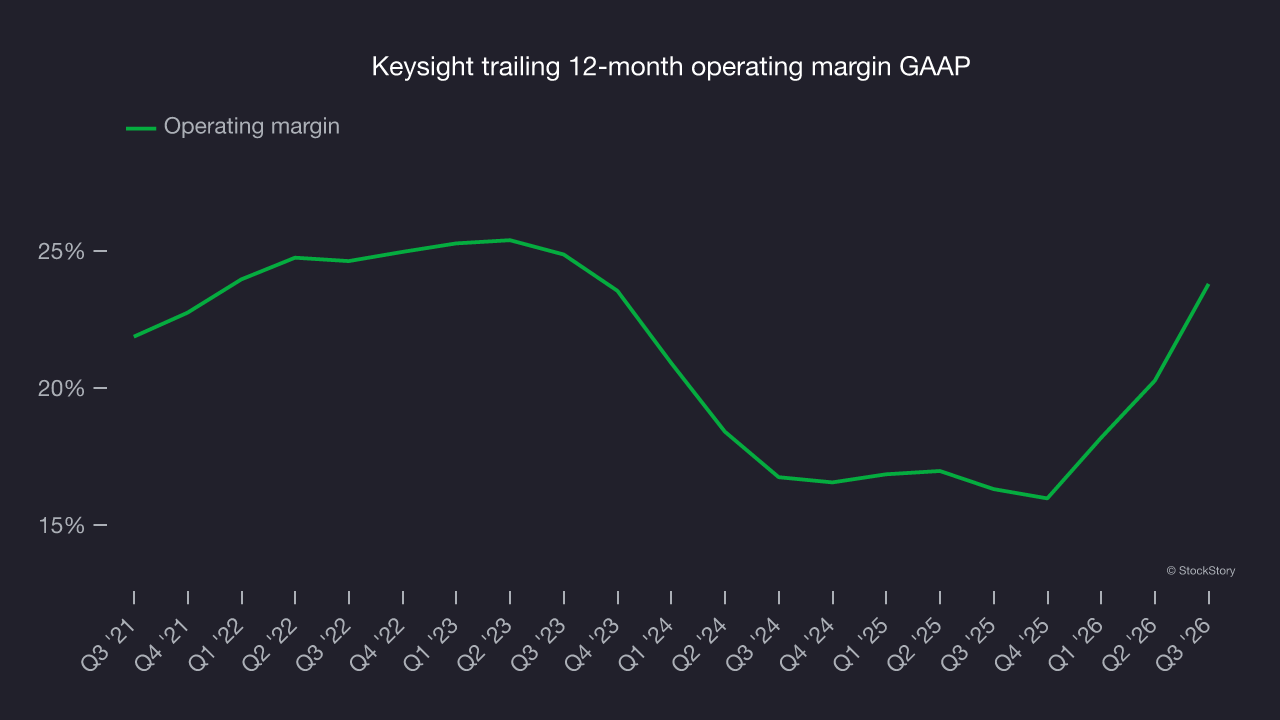
In Q3, Keysight generated an operating profit margin of 29.4%, up 14.1 percentage points year on year. The increase was solid, and because its operating margin rose more than its gross margin, it appears to have been more efficient with expenses such as marketing, R&D and administrative overhead.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Keysight’s EPS grew at a 13.5% compounded annual growth rate over the last five years, higher than its 7.7% annualized revenue growth. However, this alone doesn’t reveal much about its business quality because its operating margin didn’t improve.
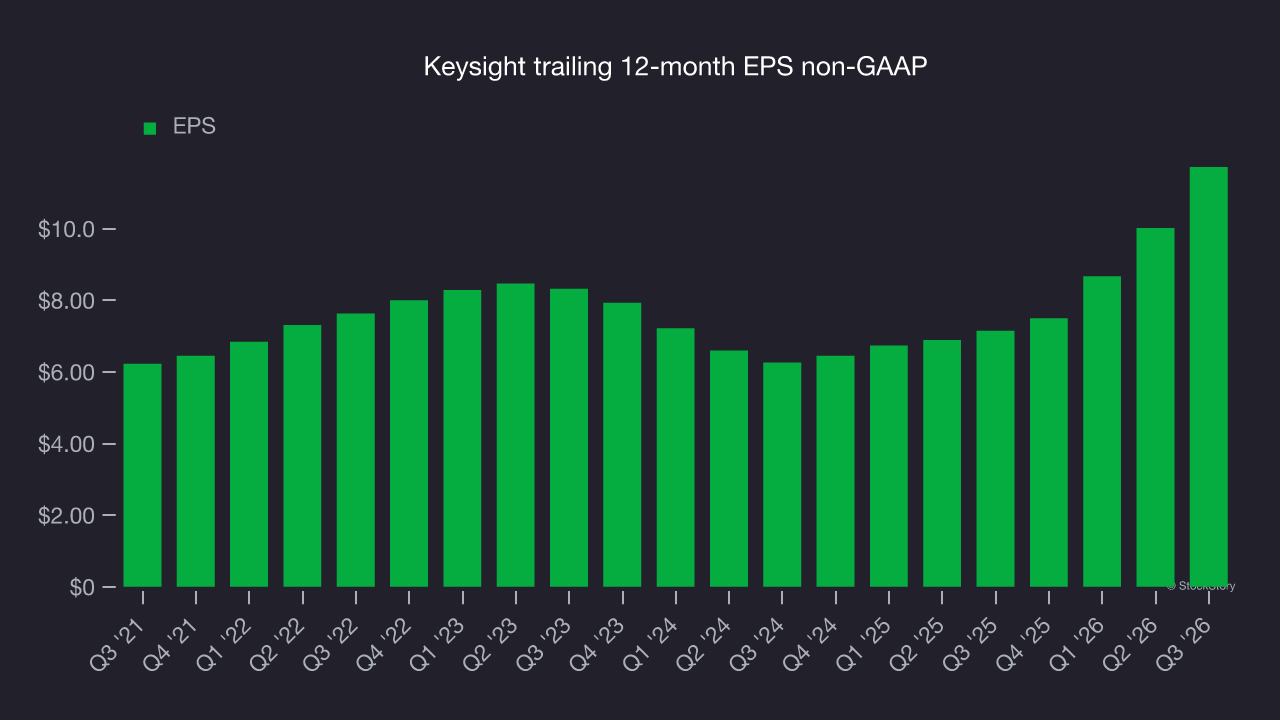
A closer look at Keysight’s earnings helps explain the drivers of its performance. A five-year view shows that Keysight has repurchased its stock, shrinking its share count by 7.5%. This indicates its EPS outperformed its revenue not because of increased operational efficiency but financial engineering, as buybacks boost per share earnings. 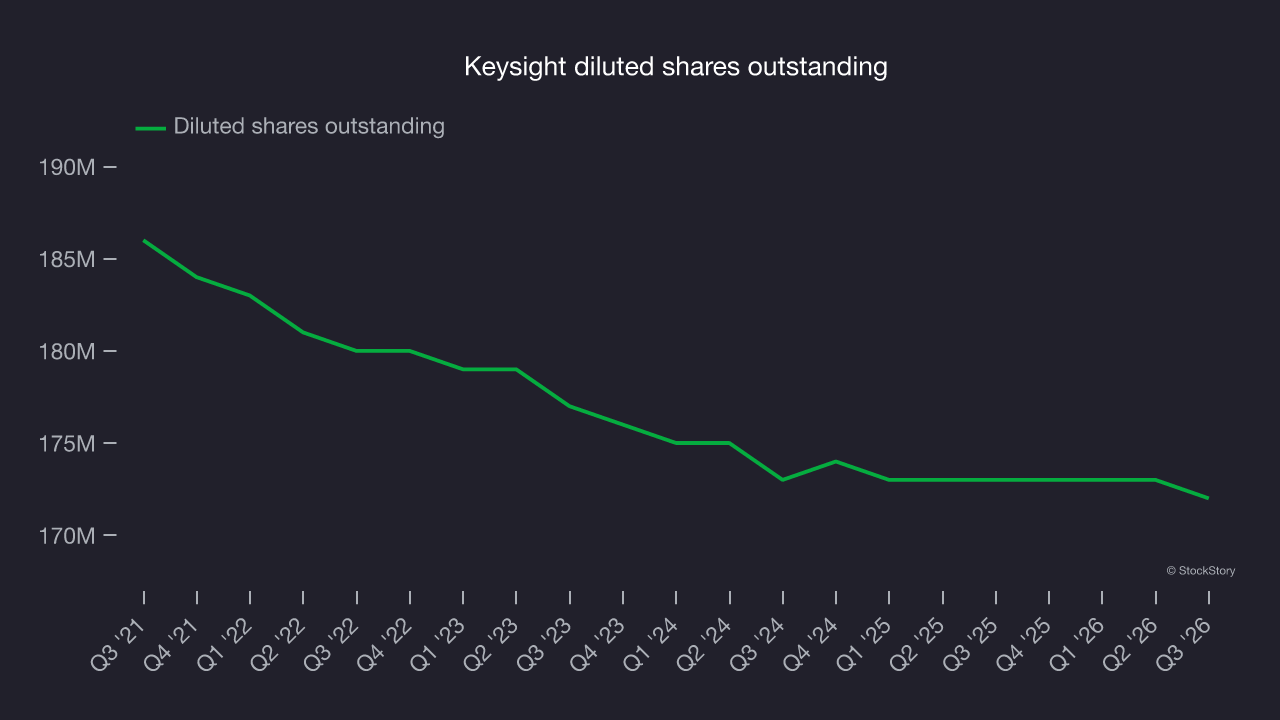
As with revenue, examining EPS over a more recent period can provide insight into an emerging theme or development for the business.
Keysight’s two-year annual EPS growth of 36.8% was higher than its five-year trend. That acceleration is a positive sign, especially given the already high base.
In Q3, Keysight reported adjusted EPS of $3.61, up from $1.91 in the same quarter last year. This result beat analysts’ consensus estimates by 6.8%. Over the next 12 months, Wall Street expects Keysight’s full-year EPS to grow 19.2% from $11.72 to $13.97, according to S&P.
Key takeaways from Keysight’s Q3 results
Keysight’s outlook stood out: EPS guidance for next quarter came in well ahead of analysts’ consensus estimates, and its revenue forecast also topped Wall Street’s consensus. Those forecasts were important positives in the quarterly report. Shares remained flat at $280.00 immediately after the release.
Keysight’s latest quarterly results matter when deciding whether to invest, but longer-term business quality and valuation matter more. Read more in our full research report here (it’s free).