


Financial technology platform Intuit (NASDAQ:INTU) reported revenue ahead of Wall Street’s expectations in calendar Q3 2026 [fiscal Q1 2027], with revenue rising 12.1% year on year to $4.35 billion. On the other hand, next quarter’s revenue guidance of $4.94 billion was less impressive, coming in 3.3% below analysts’ consensus estimates. Its non-GAAP profit of $2.91 per share was 10.2% above analysts’ consensus estimates.
For more on Intuit, read our free full research report.
Intuit Q3 CY2026 highlights:
- Revenue $4.35 billion vs S&P analyst consensus of $4.31 billion (12.1% year-on-year growth, 1.1% beat)
- Adjusted EPS $2.91 vs S&P analyst consensus of $2.64 (10.2% beat)
- Adjusted operating income $1.05 billion vs analysts’ consensus estimates of $958.6 million (24% margin, 9.1% beat)
- Revenue guidance The company lowered its revenue guidance for the full year to $23.22 billion at the midpoint from $23.4 billion, a 0.7% decrease
- Adjusted EPS guidance Management reiterated its full-year adjusted EPS guidance of $23 at the midpoint
- Operating margin 19.9%, up from 13.7% in the same quarter last year
- Free cash flow margin 22.7%, down from 28.9% in the previous quarter
- Billings $4.38 billion at quarter end, up 12% year on year
- Market capitalization $83.71 billion
“We delivered a solid first quarter, with results above the top end of our guidance,” said Sasan Goodarzi, Intuit’s chairman and chief executive officer. “Our AI-driven expert platform increasingly does more of the work for consumers, businesses and accountants, turning financial data into intelligence and action that helps them achieve better outcomes. I’m pleased with the innovation we’ve launched this quarter, and we’re focused on disciplined execution as we build durable, long-term growth.”
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Intuit grew its revenue at a 16.3% compounded annual growth rate. Though this growth is acceptable on an absolute basis, revenue growth alone is not enough to assess the software sector, which can display significant earnings volatility. The bar for the sector is particularly high, reflecting the non-essential and hit-driven nature of the products and services offered. Additionally, the five-year growth rate starts around Covid, when revenue was depressed before rebounding. Still, there are other things to like about Intuit.
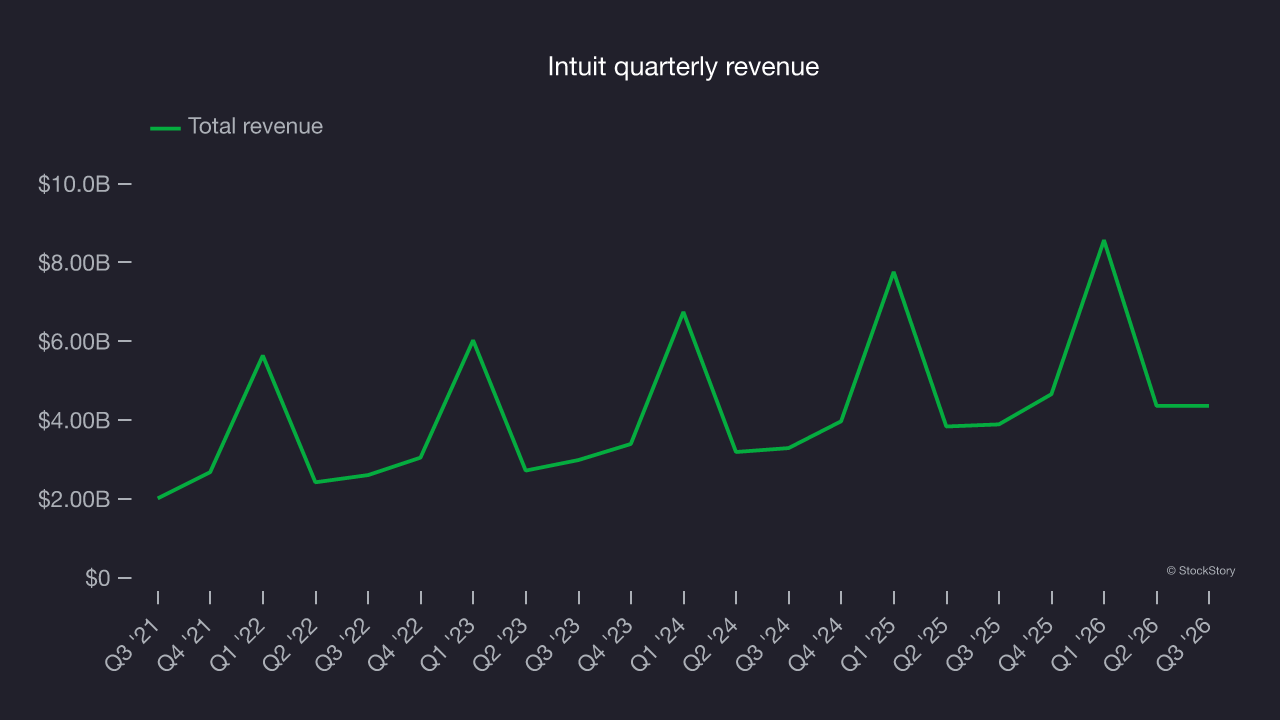
Long-term growth is the most important, but within software, a half-decade historical view may miss new innovations or demand cycles. Intuit’s recent performance shows its demand has slowed as its annualized revenue growth of 14.9% over the last two years was below its five-year trend. Decelerating revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 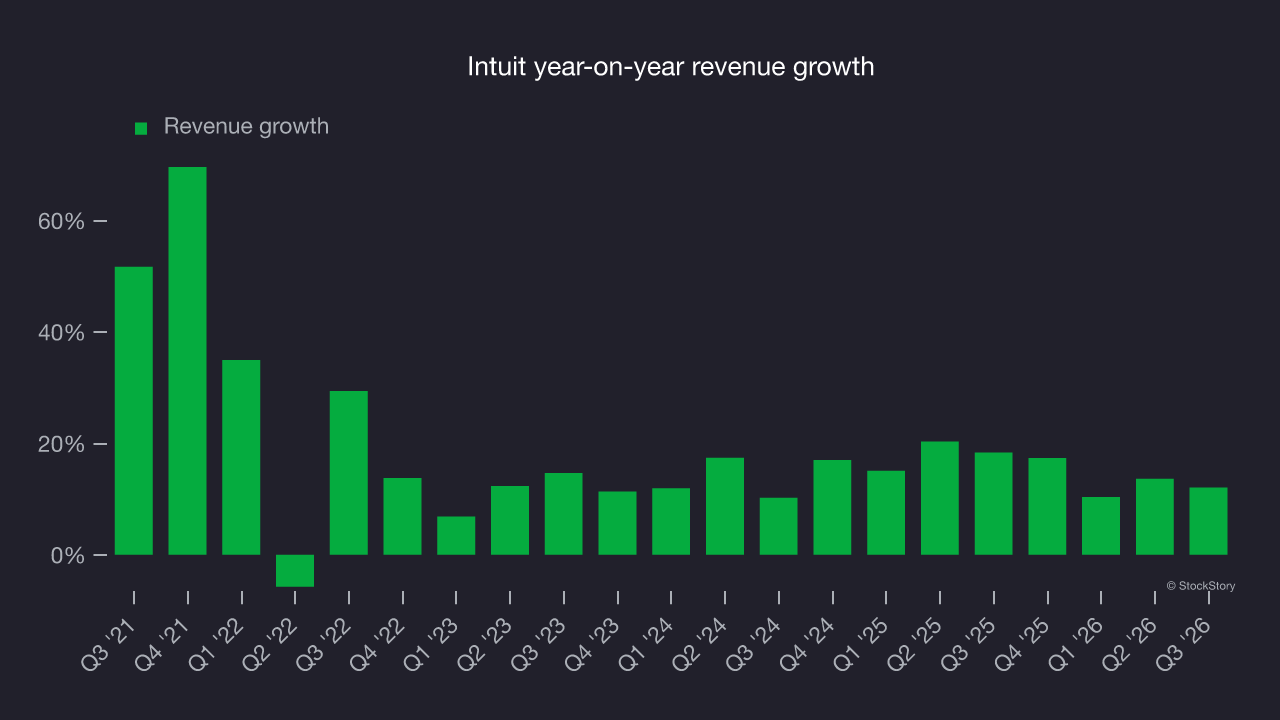
This quarter, Intuit reported year-on-year revenue growth of 12.1%, and its $4.35 billion of revenue exceeded Wall Street’s consensus estimates by 1.1%. Company management is currently guiding for a 6.3% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 8.9% over the next 12 months, according to S&P, a deceleration versus the last two years. This underwhelming projection indicates its products and services will see some demand headwinds. On the positive side, the company is tracking well in other measures of financial health.
Billings
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
Intuit’s billings came in at $4.38 billion in Q3, and over the last four quarters, billings growth was underwhelming, averaging 12.6% year-on-year increases. This performance mirrored its total revenue and suggests that increasing competition is making it harder to acquire and retain customers. 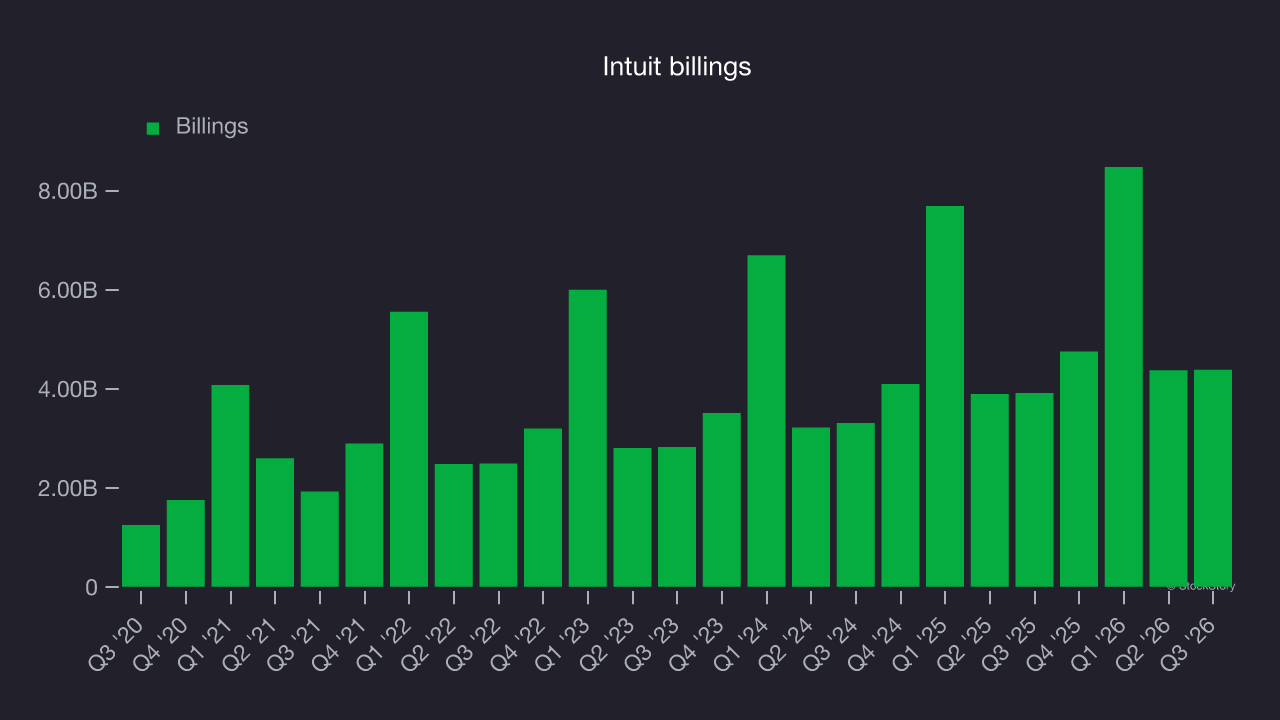
Customer acquisition efficiency
The customer acquisition cost, or CAC, payback period represents the months required to recover the cost of acquiring a new customer. Essentially, it’s the break-even point for sales and marketing investments. A shorter CAC payback period is ideal, as it implies better returns on investment and business scalability.
It’s relatively expensive for Intuit to acquire new customers as its CAC payback period was 28.8 months this quarter. The company’s slow recovery of its sales and marketing expenses indicates it operates in a competitive market. On the positive side, once Intuit acquires customers, they typically stay and increase their spending, a sign of high switching costs.
Key takeaways from Intuit’s Q3 results
Intuit’s quarter could have been better: Adjusted operating income beat analysts’ consensus estimates by a wide margin and revenue narrowly topped Wall Street’s consensus, but the guidance fell short. Full-year EPS guidance missed expectations, as did the revenue outlook for next quarter. Shares plunged 10.3% to $268.25 immediately after the results.
Intuit may have had a tough quarter, but assessing whether it offers an investment opportunity requires a broader view. Consider valuation, business quality and the latest earnings. For more on Intuit, read the full research report here (it’s free).