


Tempus AI has just seen its share price slide while signing fresh collaboration deals that speak directly to its revenue pipeline. That mix of a weaker stock and new commercial commitments puts the focus squarely on whether the business you are paying for today is supported by the cash flows it can realistically generate.
- The share price fell 21.5% over the past week, which forces anyone looking at Tempus AI to ask if sentiment has swung further than its underlying cash flow profile.
- AstraZeneca’s renewed agreement, with a US$200 million commitment through 2031, may support more predictable future billings and could influence how steady Tempus AI’s cash generation looks over time.
- If you'd rather focus on sales, this one's for you. See what Tempus AI's 7.2x P/S says about the price.
The issue now is whether the current Tempus AI share price is adequately backed by the cash flows suggested by its Discounted Cash Flow (DCF) intrinsic value estimate.
If you want more context around Tempus AI's recent pullback and new agreements, it can help to compare it with 36 healthcare AI stocks.
Is Tempus AI a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here relies on Tempus AI eventually converting its data and diagnostics platform into sustained surplus cash. Latest twelve month free cash flow shows a loss of about US$140.6 million, so the whole framework assumes a move from cash burn today to positive and growing free cash generation over the coming decade.
Those projections incorporate recovering and then expanding free cash flow into the hundreds of millions of US$ per year, which is a confident path given where Tempus AI is starting from. AstraZeneca’s extended collaboration through 2031, with its US$200 million commitment, helps explain why the Discounted Cash Flow (DCF) view places the estimated intrinsic worth substantially above the current share price of $59.61, since it points to more visible demand for Tempus AI’s services. Find out what Tempus AI could be worth using our Discounted Cash Flow (DCF) estimate.
The Tempus AI Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where Tempus AI's valuation gap leaves off by explaining which paths for growth, profitability and earnings would need to unfold for the stock to be worth materially more or less than it is today, and they sit on the Community page. Each one links its number to a clear view on how Tempus AI's revenue potential, cost structure and risk profile might evolve, giving you something concrete to revisit as fresh information comes through.
One of the top community narratives on Tempus AI: 21% undervalued
According to QuanD, a Simply Wall St Community investor who wrote the Narrative, Tempus AI is building a healthcare data platform with a reinforcing flywheel.
"It’s building a healthcare data platform where diagnostics generate data, that data improves its AI products, and better products attract more customers…"
Discover why this Narrative puts Tempus AI at 21% undervalued.
One more Tempus AI check that sits beside the cash flow story
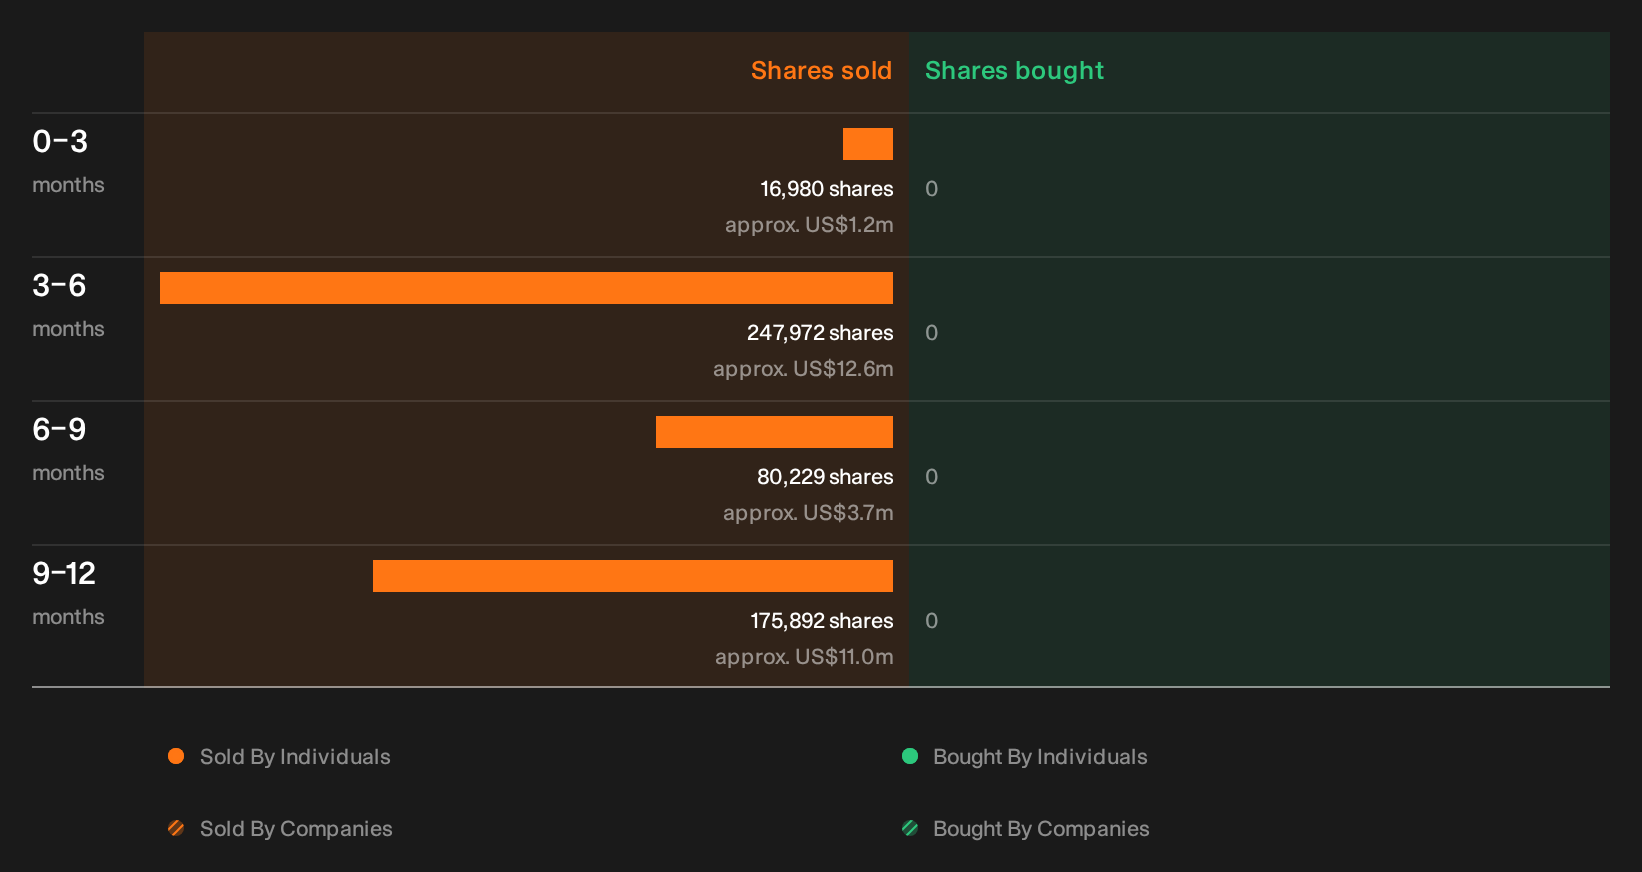
There is one final angle on Tempus AI that valuation models do not capture. It is what recent insider share activity might be signalling about expectations inside the boardroom. See the recent insider selling flagged for Tempus AI.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com