


- Traefik Labs has rolled out Traefik Hub across multiple platforms, including service provider clouds on Nutanix Cloud Platform. This gives providers Layer 7 services such as API gateways, web application firewalls and certificate management on top of Nutanix infrastructure.
- For Nutanix, being the foundation for Traefik Hub based tenant services underlines its role in enabling higher value cloud offerings rather than only supplying core infrastructure.
- We will now look at how Nutanix's investment narrative could be shaped by Traefik powered tenant services on its cloud platform.
Nutanix Investment Narrative Recap
To own Nutanix, you need to believe the business can keep turning its hybrid multicloud and AI platform into durable subscription revenue, even while hardware server prices stay 4 to 5 times higher than a year ago and are expected to remain elevated with long lead times through FY27. The analyst consensus narrative on Simply Wall St leans on that multiyear modernization and AI workload story as the backbone.
The key near-term catalyst is execution against that software-heavy pitch, while more flexible payment structures in FY27 are expected to keep free cash flow margin roughly flat around 28%. The biggest risk is that delayed deployments from expensive hardware and tougher VMware migration competition slow recognized revenue and earnings faster than Nutanix’s newer products can offset.
The Traefik Hub launch on Nutanix Cloud Platform matters most because it speaks directly to that hybrid multicloud and AI thesis. Service providers using Nutanix can now package higher value Layer 7 services, such as API gateways and web application firewalls, above the base infrastructure, which supports the idea of Nutanix as more than a single-product HCI vendor.
Set that against the current backdrop where Nutanix reports US$2.853b in revenue, annual recurring revenue of US$2.549b and net income of US$1.507b, with earnings that grew about 7x over the past year and net margins at 52.8%. If Traefik-powered tenant services gain adoption, they could feed that recurring mix, although competition for VMware migrations and earnings forecasts that decline over the next 3 years remain front-of-mind risks.
Nutanix's narrative projects US$4.2b revenue and US$673.9m earnings by 2029. This aligns with analyst assumptions of 13.8% yearly revenue growth and an earnings decrease of about US$833m from US$1.5b today.
Uncover why Nutanix's fair value indicates a 38% potential upside to its current price, which could narrow quickly.
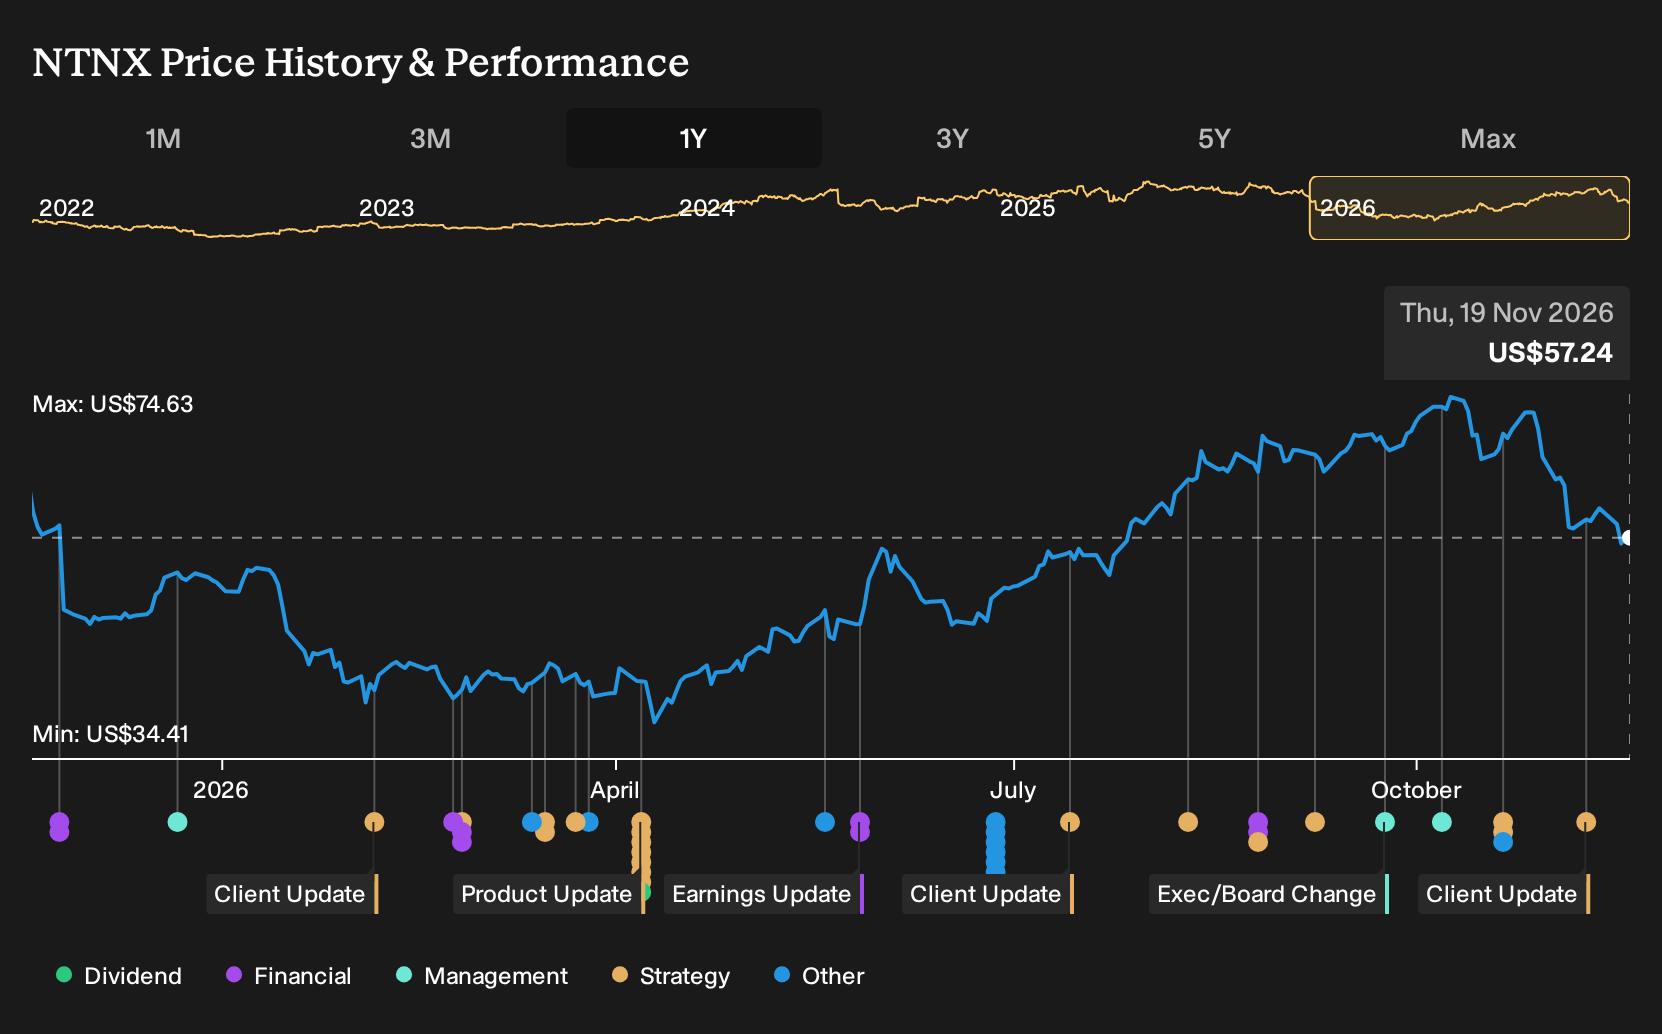
Exploring Other Perspectives
One alternate angle you might explore is the risk that AI offerings on Nutanix, including Traefik powered services, take longer to translate into meaningful ARR. The most cautious analysts were working off revenue growth of 12.6% and earnings of about US$517.0m by 2029, well below the US$673.9m consensus, so their pre news view already looked more restrained. This new Traefik Hub rollout could push some of those narratives to evolve, which is why it helps to compare several viewpoints before you decide how Nutanix fits your own portfolio story.
Explore 3 other Nutanix fair value estimates, including one that suggests it could be worth just $79.27!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Nutanix research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nutanix. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nutanix's overall financial health at a glance.
Looking for more Nutanix sized investment ideas?
If Nutanix sits on your watchlist, it can help to compare it with a wider field of potential opportunities that match different goals, from resilience to income to future growth potential. The Simply Wall St Screener lets you do exactly that by filtering for fundamentals that matter to you, then surfacing a focused set of companies to research further.
- If capital preservation comes first for you, start with companies screened for balance sheet strength and resilient fundamentals through the list of solid balance sheet and fundamentals (25 results).
- If you want income to play a bigger role in your returns, look at stocks with higher yields and robust payout profiles via the 8 dividend fortresses.
- If you prefer to hunt for tomorrow's potential leaders before they are widely followed, filter for quality metrics and pricing markers through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com