


Modexus Solutions (MOD) is back in focus after activist investor Jana Partners publicly pushed the company on November 19 to improve margins or consider a sale, which has sharpened attention on the stock’s risk reward trade off.
Recent headlines around a potential Samsung takeover, a new US$500m buyback and the Modine to Modexus Solutions rebrand have all arrived just as activist pressure heats up. Yet the shares still fell 2.4% on the day to US$134.56 and remain down 31.9% over three months, even though the 5 year total shareholder return is extremely large and the 3 year total shareholder return is up 183.2%. Momentum has cooled in the short term while the longer record remains very strong.
Spot opportunities around Modexus Solutions by scanning a curated set of AI infrastructure peers in our 53 AI infrastructure stocks that are shaping the next leg of data center and thermal management growth.Bulls see Modexus Solutions as a discounted play on AI thermal infrastructure, while bears see a peaked story masked by buybacks and M&A noise. With the numbers now on the table, which case fits the current valuation?
Most Popular Narrative: 36% Undervalued
Modexus Solutions' analyst consensus Narrative on Simply Wall St anchors fair value at about $210.89 per share, compared to the latest close of $134.56. This comparison puts a sharp spotlight on whether execution can catch up with those expectations under an 8.8% discount rate.
The accelerating build out of data centers and the need for next generation cooling solutions are driving demand for Modine Manufacturing’s products, with management targeting data center revenue of about US$2b by fiscal 2028 after delivering US$1.1b in fiscal 2026 and guiding to 60% to 80% Data Center sales growth in fiscal 2027, which points to a significant revenue growth engine and potential operating leverage as new capacity fills.
See why 58 investors see Modexus Solutions as 36% undervalued.
Result: Fair Value of $210.89 (UNDERVALUED)
Still, the narrative around Modexus Solutions can crack if supply chain snags persist or if future data center contracts lean heavily on lower margin work.
Find out about the key risks to this Modexus Solutions narrative.
Another View: What Modexus Solutions’ P/E Is Telling You
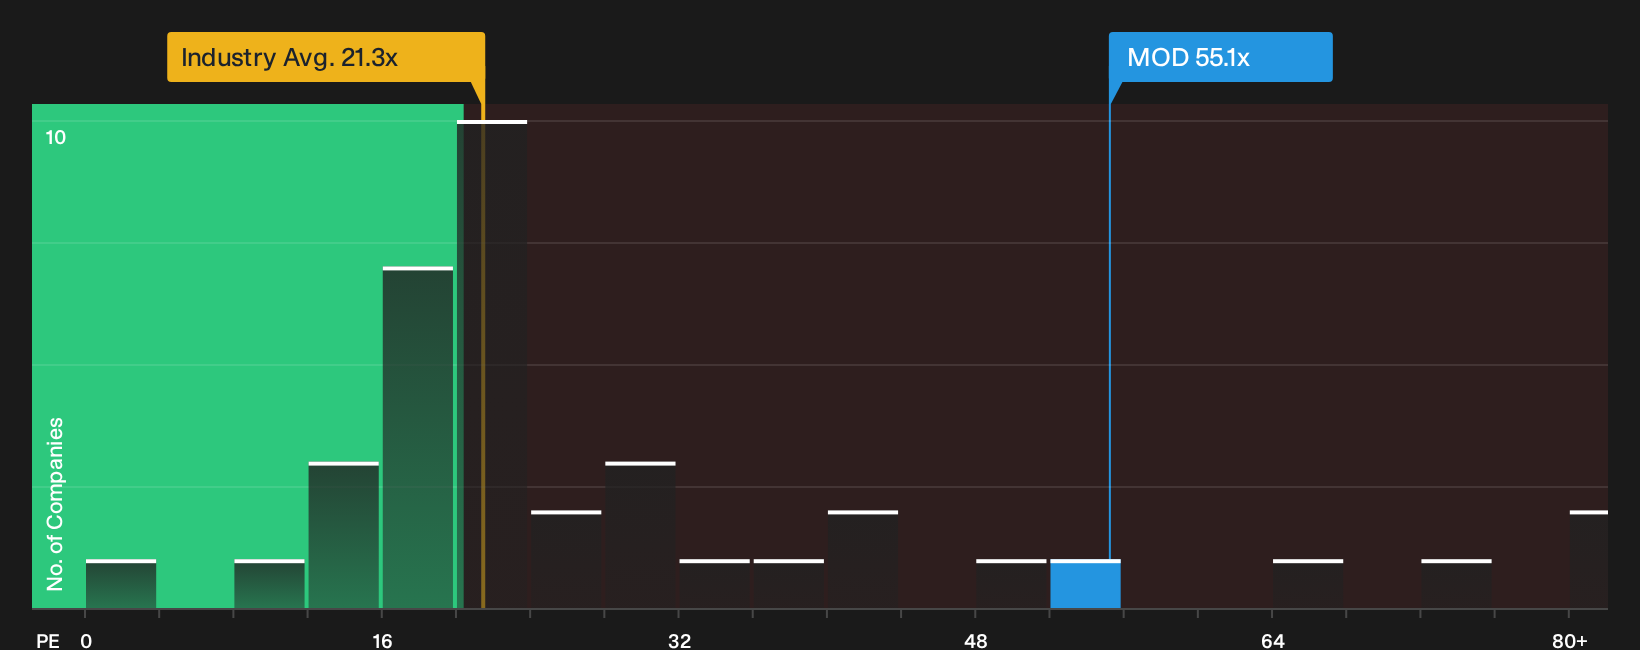
The first story presents Modexus Solutions as 36% undervalued on future earnings power. A different lens uses today’s P/E. On this measure, the stock trades at 55.1x earnings, which is far above the US Building industry at 21.3x and above peers at 29.2x, even though the fair ratio is 77x. That gap leaves investors weighing whether the current multiple already reflects a high level of optimism or whether the market could move closer to that fair ratio if the AI cooling thesis holds.
For anyone considering that trade off, it helps to see how the current pricing compares with other valuation checks, then consider what would need to go right in the business before the market shifted closer to that fair ratio. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Modexus Solutions is clearly split, so take a moment to review the full dataset and decide for yourself using 2 key rewards and 4 important warning signs.
Hunting For More Ideas Beyond Modexus Solutions?
If Modexus Solutions has your attention, do not stop there. Broaden your watchlist with a few focused screens that can surface very different types of opportunities.
- Target potential mispricing by scanning a curated 36 high quality undervalued stocks that combines solid fundamentals with compressed valuations.
- Prioritise resilience and aim to sleep better at night by filtering for a 30 resilient stocks with low risk scores with stronger balance sheets and lower risk scores.
- Unearth tomorrow’s potential leaders early by running a 19 high quality undiscovered gems before the wider market catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com