


Corteva (CTVA) has been hit by a cluster of events in November 2026, including a widened third quarter loss, a delayed 10 Q filing, and a new chlorpyrifos related lawsuit.
The headlines have fed straight into sentiment around Corteva. The 1 day share price return declined 2.87%, the 7 day share price return fell 11.64%, and the 30 day share price return dropped 37.05%. This leaves the year to date share price return down 35.40% and signals fading momentum as investors reassess both earnings quality and legal risk.
Scan how other agriculture and materials names are reacting to similar earnings and legal pressure by checking the hand picked 30 resilient stocks with low risk scores set, which can serve as a potential contrast to Corteva.
Corteva now trades after a sharp reset and a cluster of setbacks, so the real task is weighing legal and earnings uncertainty against a lower entry price, as the valuation section spells out.
Most Popular Narrative: 10% Overvalued
The narrative fair value on Corteva sits at $7.40 per share, which is below the latest close of $8.12. As a result, the focus shifts to whether the underlying earnings story supports paying a premium, according to Bouden, a Simply Wall St Community investor who set out a detailed three year recovery case.
The available history shows a substantial deterioration from FY2025 net income to the LTM figure. This helps explain why the recovery thesis requires margin normalisation rather than merely modest sales growth. The LTM figures also include unusual items of negative US$185m, which may distort reported earnings.
See why 2 investors see Corteva as 10% overvalued.
Result: Fair Value of $7.40 (OVERVALUED)
Still, the weak LTM earnings, together with a reported dividend payout ratio of 468% and US$1.7b in net debt, could quickly undermine the Corteva recovery script.
Find out about the key risks to this Corteva narrative.
Another View on Corteva’s Valuation
The community narrative pegs Corteva at $7.40 per share and describes the stock as 10% overvalued. The SWS DCF model points in a different direction. It places Corteva’s future cash flow value closer to $14.89, which is above the current $8.12 share price and identifies the stock as undervalued.
The gap between a $7.40 recovery case and a $14.89 cash flow estimate leaves a wide band of potential outcomes. It highlights one central question for you as an investor: Which set of assumptions appears more realistic for Corteva’s earnings power over the next few years, and how much uncertainty are you prepared to accept for that possible upside?
Look into how the SWS DCF model arrives at its fair value.
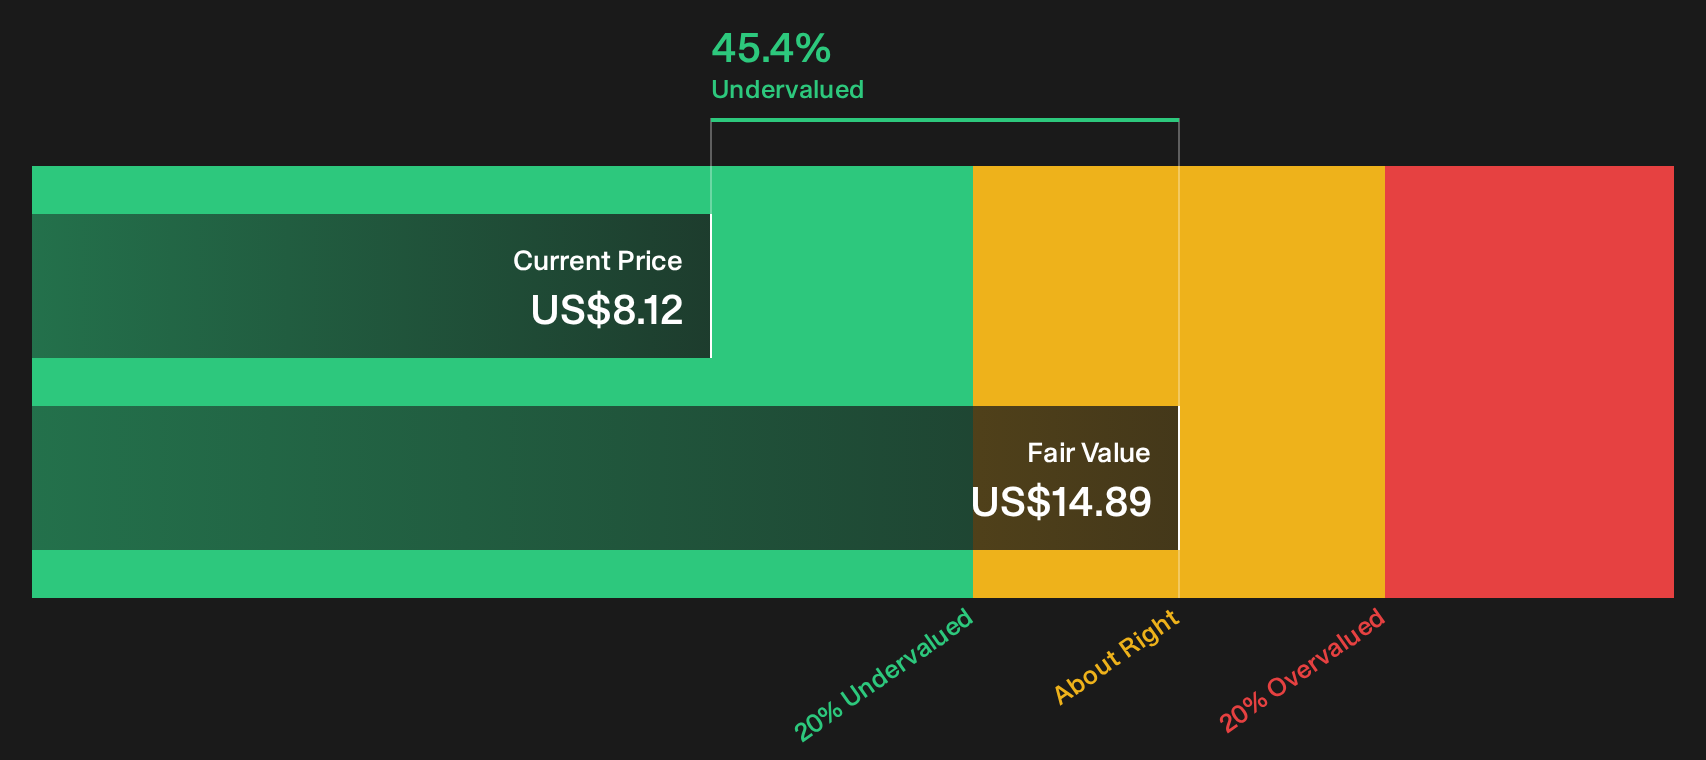
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Corteva for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Corteva is clearly split, with real concerns sitting alongside genuine optimism. Act while the information is fresh and test the data for yourself by weighing up the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Corteva?
If Corteva has you rethinking risk and reward, broaden your watchlist now with a few focused sets of opportunities that match different investing angles.
- Target resilience by scanning companies with steadier balance sheets and fundamentals through the list of solid balance sheet and fundamentals (25 results).
- Hunt for value by checking the 36 high quality undervalued stocks that combine stronger financial profiles with potentially attractive pricing.
- Prioritise consistent cash returns by reviewing the income focused opportunities highlighted in the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com