


As the craze of earnings season draws to a close, here’s a look back at some of the most exciting (and some less so) results from Q3. Today, we are looking at home builders stocks, starting with LGI Homes NASDAQ:LGIH.
Traditionally, homebuilders have built competitive advantages with economies of scale that lead to advantaged purchasing and brand recognition among consumers. Aesthetic trends have always been important in the space, but more recently, energy efficiency and conservation are driving innovation. However, these companies are still at the whim of the macro, specifically interest rates that heavily impact new and existing home sales. In fact, homebuilders are one of the most cyclical subsectors within industrials.
The 9 home builders stocks we track reported a softer Q3. As a group, revenues missed analysts’ consensus estimates by 1.7%.
While some home builders stocks have fared somewhat better than others, they have collectively declined. On average, share prices are down 2.2% since the latest earnings results.
Best Q3: LGI Homes NASDAQ:LGIH
Based in Texas, LGI Homes (NASDAQ:LGIH) is a homebuilding company specializing in constructing affordable, entry-level single-family homes in desirable communities across the United States.
LGI Homes reported revenues of $437.5 million, up 10.3% year on year. This print exceeded analysts’ expectations by 1%. Overall, it was a very strong quarter for the company with a beat of analysts’ EPS estimates.
“Based on our year-to-date results and current market conditions, we are narrowing our full-year closings guidance and now expect to close between 4,600 and 4,800 homes in 2026. The revised outlook reflects slower sales activity in the quarter as affordability pressures continued to weigh on demand. We continue to see interest in homeownership and are leaning into our proven sales and marketing strategies to improve sales pace while maintaining our disciplined approach to balancing affordability and profitability. We are maintaining the remainder of our full-year 2026 guidance.”
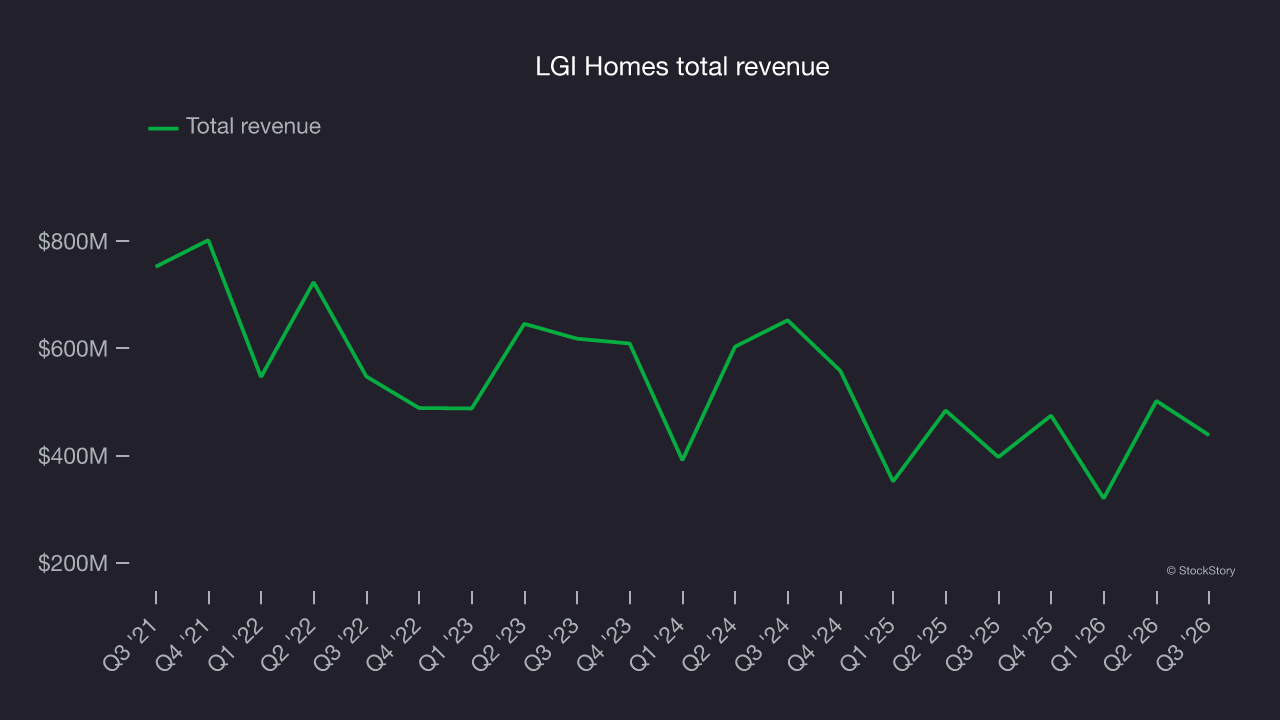
LGI Homes achieved the fastest revenue growth in the group. Investor expectations, however, were likely higher than Wall Street’s published projections, leaving some wishing for even better results (analysts’ consensus estimates are those published by big banks and advisory firms, not the investors who make buy and sell decisions). The stock is down 17.4% since reporting and currently trades at $39.15.
Is now the time to buy LGI Homes? Access our full analysis of the earnings results here, it’s free.
Champion Homes (NYSE:SKY)
Founded in 1951, Champion Homes (NYSE:SKY) is a manufacturer of modular homes and buildings in North America.
Champion Homes reported revenues of $727 million, up 6.2% year on year, outperforming analysts’ expectations by 0.7%. The business had a satisfactory quarter with a narrow beat of analysts’ EBITDA estimates.
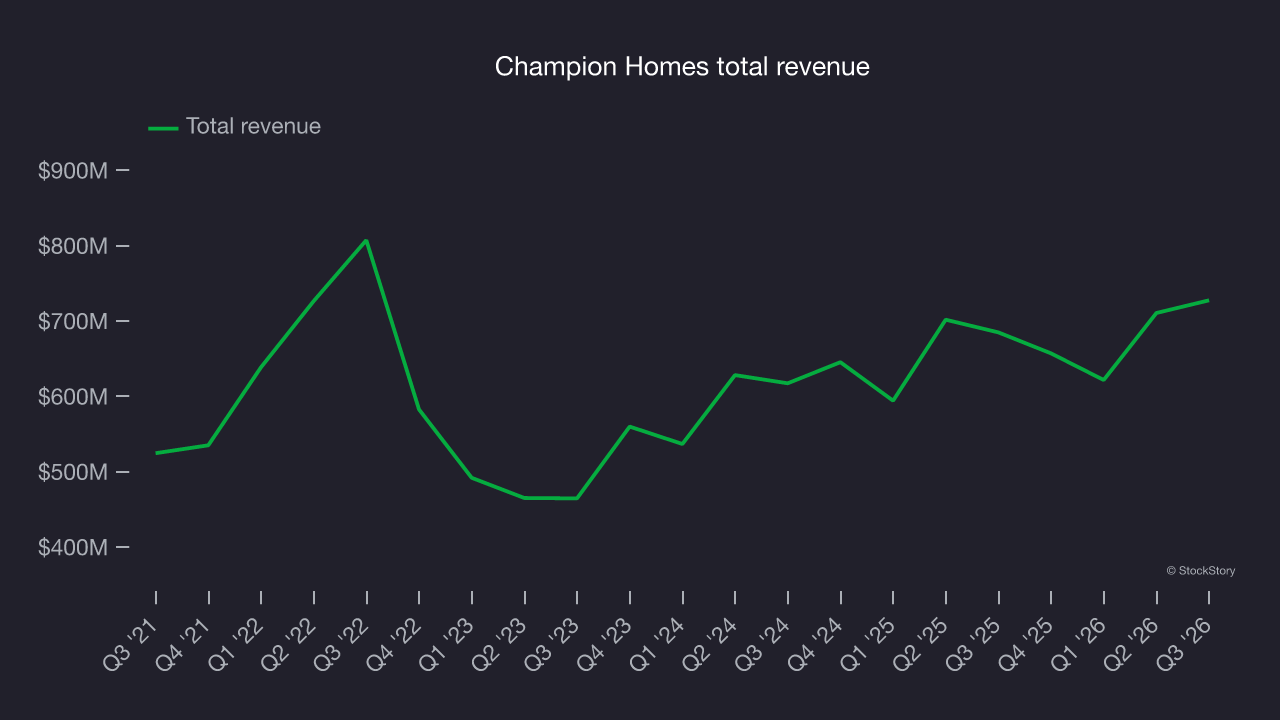
The market seems happy with the results as the stock is up 5.8% since reporting. It currently trades at $91.40.
Is now the time to buy Champion Homes? Access our full analysis of the earnings results here, it’s free.
Weakest Q3: NVR (NYSE:NVR)
Known for its unique land acquisition strategy, NVR (NYSE:NVR) is a respected homebuilder and mortgage company in the United States.
NVR reported revenues of $2.40 billion, down 7.9% year on year, falling short of analysts’ expectations by 6.4%. It was an underwhelming quarter as it posted a significant miss of analysts’ EPS estimates.
As expected, the stock is down 6.7% since the results and currently trades at $5,505.
Read our full analysis of NVR’s results here.
Lennar (NYSE:LEN)
One of the largest homebuilders in America, Lennar (NYSE:LEN) is known for constructing affordable, move-up, and retirement homes across a range of markets and communities.
Lennar reported revenues of $8.05 billion, down 8.7% year on year. This result lagged analysts’ expectations by 3.2%. Overall, it was an underwhelming quarter as it also recorded a significant miss of analysts’ EPS estimates.
The stock is up 2.4% since reporting and currently trades at $80.25.
Read our full, actionable report on Lennar here, it’s free.
KB Home (NYSE:KBH)
The first homebuilder to be listed on the NYSE, KB Home (NYSE:KBH) is a homebuilding company targeting the first-time home buyer and move-up buyer markets.
KB Home reported revenues of $1.30 billion, down 20% year on year. This print met analysts’ expectations. Zooming out, it was a mixed quarter as it also produced a beat of analysts’ EPS estimates but full-year revenue guidance missing analysts’ expectations.
KB Home pulled off the highest full-year guidance raise but had the slowest revenue growth among its peers. The stock is down 5.9% since reporting and currently trades at $45.73.
Read our full, actionable report on KB Home here, it’s free.
Market update
Over the past year, investors have been forced to repeatedly answer the same question: What is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Strong Momentum Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.