


We can readily understand why investors are attracted to unprofitable companies. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. But while history lauds those rare successes, those that fail are often forgotten; who remembers Pets.com?
So should Pioneer Power Solutions (NASDAQ:PPSI) shareholders be worried about its cash burn? For the purpose of this article, we'll define cash burn as the amount of cash the company is spending each year to fund its growth (also called its negative free cash flow). We'll start by comparing its cash burn with its cash reserves in order to calculate its cash runway.
When Might Pioneer Power Solutions Run Out Of Money?
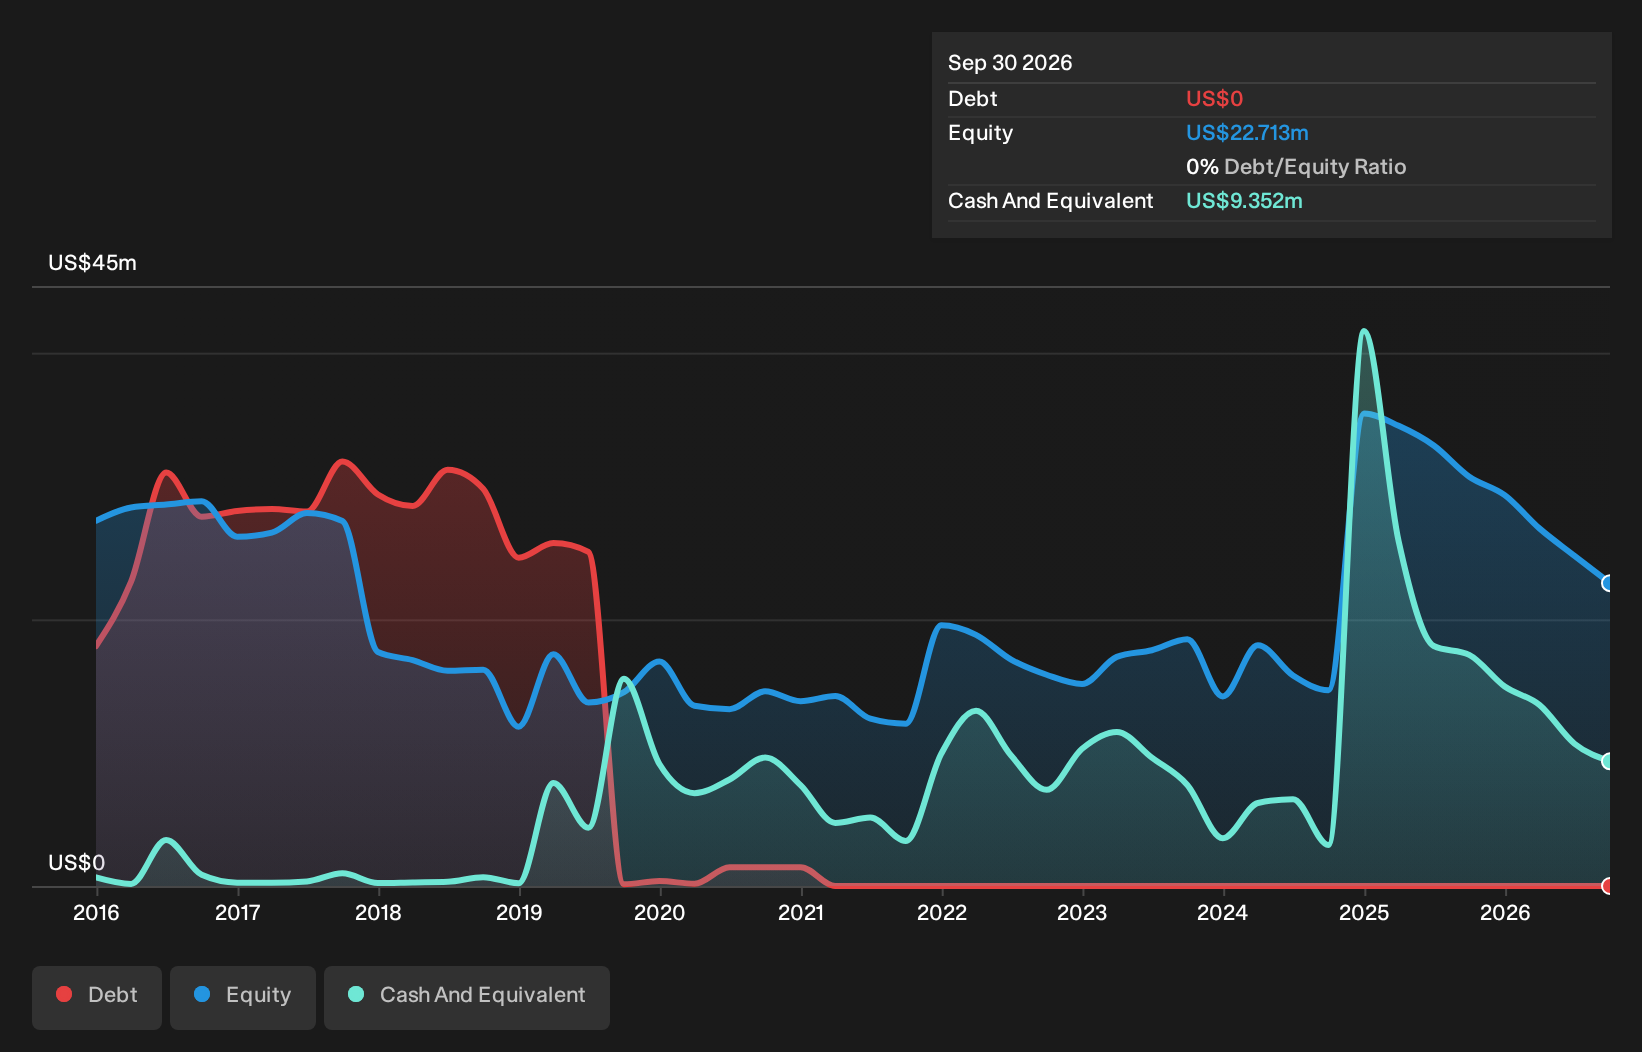
A cash runway is defined as the length of time it would take a company to run out of money if it kept spending at its current rate of cash burn. As at September 2026, Pioneer Power Solutions had cash of US$9.4m and no debt. Importantly, its cash burn was US$8.1m over the trailing twelve months. So it had a cash runway of approximately 14 months from September 2026. That's not too bad, but it's fair to say the end of the cash runway is in sight, unless cash burn reduces drastically. The image below shows how its cash balance has been changing over the last few years.
Check out our latest analysis for Pioneer Power Solutions
How Well Is Pioneer Power Solutions Growing?
We reckon the fact that Pioneer Power Solutions managed to shrink its cash burn by 26% over the last year is rather encouraging. Unfortunately, however, operating revenue declined by 37% during the period. In light of the data above, we're fairly sanguine about the business growth trajectory. Clearly, however, the crucial factor is whether the company will grow its business going forward. So you might want to take a peek at how much the company is expected to grow in the next few years.
Can Pioneer Power Solutions Raise More Cash Easily?
Pioneer Power Solutions seems to be in a fairly good position, in terms of cash burn, but we still think it's worthwhile considering how easily it could raise more money if it wanted to. Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. Many companies end up issuing new shares to fund future growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
Pioneer Power Solutions has a market capitalisation of US$23m and burnt through US$8.1m last year, which is 35% of the company's market value. That's not insignificant, and if the company had to sell enough shares to fund another year's growth at the current share price, you'd likely witness fairly costly dilution.
Is Pioneer Power Solutions' Cash Burn A Worry?
Even though its falling revenue makes us a little nervous, we are compelled to mention that we thought Pioneer Power Solutions' cash burn reduction was relatively promising. Looking at the factors mentioned in this short report, we do think that its cash burn is a bit risky, and it does make us slightly nervous about the stock. On another note, we conducted an in-depth investigation of the company, and identified 2 warning signs for Pioneer Power Solutions (1 is a bit unpleasant!) that you should be aware of before investing here.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of companies with significant insider holdings, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.