


- DICK'S Sporting Goods has already launched its first officially licensed collegiate collections from VRST, CALIA and DSG for Ohio State and Iowa, offering t-shirts, pants and layering pieces across men's, women's and youth in select stores and online.
- The new collegiate ranges expand DICK'S Sporting Goods vertical brands just as Nike, which supplies roughly 31% of its merchandise, signalled a multiyear revenue slump that could pressure athletic footwear and apparel demand.
- We will look at how DICK'S Sporting Goods' investment narrative is strained as Nike's prolonged revenue weakness reshapes its merchandise outlook.
DICK'S Sporting Goods Investment Narrative Recap
To own DICK'S Sporting Goods, you need to believe the core omni channel retail engine and vertical brands can offset pressure from suppliers and weaker banners. According to LunaRodas, an investor in the Simply Wall St Community, the DICK'S banner remained resilient even as Foot Locker dragged on guidance. The recent Nike revenue outlook keeps that concentration risk front and center. The critical short term swing factor is how cleanly DICK'S can keep footwear and apparel turning without relying on a single vendor story.
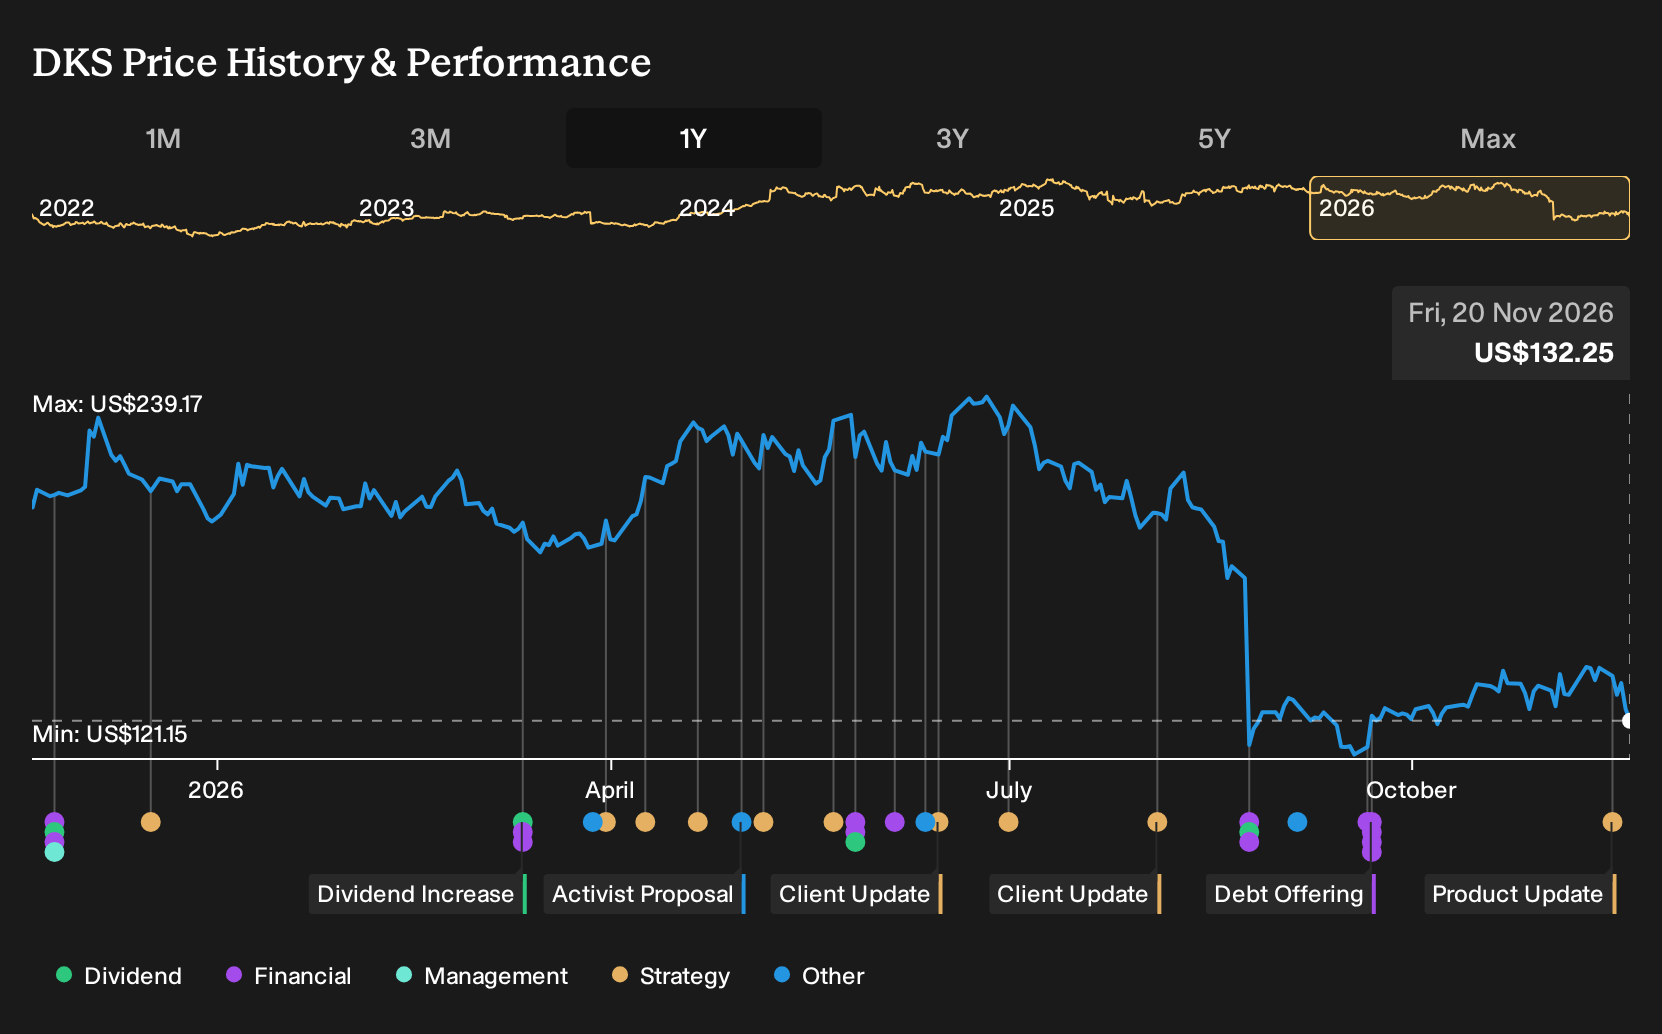
The biggest current risk is margin pressure as promotions, weaker sneaker launches and Foot Locker losses intersect with already compressed net profit margins near 4%, down from 8.5% last year. Nike signalling lower revenue through fiscal 2028 raises the chance that athletic demand stays choppy. If that persists, investors are watching whether DICK'S can protect gross margin through mix, private labels and media assets while still funding store expansion and marketing.
The licensed collegiate launch under VRST, CALIA and DSG looks most relevant right now. LunaRodas argued that DICK'S diversification across footwear, apparel and hardlines helped reduce reliance on any single footwear cycle. This new college focused assortment extends that idea. It leans on in house brands, different logos and a broader fan base. That matters when Nike, at roughly 31% of merchandise purchases, is guiding to years of lower revenue.
For you as a shareholder, the key question is execution. Collegiate capsules for Ohio State and Iowa test whether DICK'S can build meaningful, repeatable demand in categories it controls more tightly. Success could soften the impact of weaker sneaker launches at Foot Locker and a tougher athletic footwear market. Poor sell through would leave DICK'S more exposed to supplier volume swings, promotional pressure and the existing earnings drag from Foot Locker losses.
LunaRodas anchors the narrative at a fair value of $112.77 for DICK'S Sporting Goods, driven primarily by the view that the core DICK'S banner, House of Sport and Field House expansion, Fast Break store rollout, and media assets like GameChanger and DICK'S Media Network together form a cohesive earnings engine, despite volatility at Foot Locker.
Uncover why DICK'S Sporting Goods' fair value indicates a 15% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some analysts focus less on DICK'S Sporting Goods vertical brands and more on spending risk. The lowest estimates before this news assumed revenue growth of only 2.9% a year and earnings of about US$1.0b by 2029. That is a much harsher view on margins and returns, and you should expect those opinions to evolve as the collegiate launch plays through.
Explore 2 other DICK'S Sporting Goods fair value estimates, including one that suggests it could be worth just $157.92.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own independent research and judgment.
- A great starting point for your DICK'S Sporting Goods research is our analysis highlighting 3 key rewards and 4 important warning signs that could inform your investment decision.
- See our latest analysis for DICK'S Sporting Goods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate DICK'S Sporting Goods' overall financial profile at a glance.
Looking for more DICK'S Sporting Goods style investment ideas?
If the DICK'S Sporting Goods story has you thinking about concentration risk, supplier exposure and balance sheet strength, it can help to line it up against a wider watchlist of potential opportunities using the Simply Wall St Screener.
- For investors who want potential upside without paying up for quality, scan a curated set of 40 high quality undervalued stocks that combine fundamentals with discounted pricing on our models.
- If capital preservation ranks high for you, focus on companies with steadier profiles by filtering through our 32 resilient stocks with low risk scores and compare their risk scores side by side.
- For readers who care less about headlines and more about financial resilience, start with a list of solid balance sheet and fundamentals (24 results) to see which businesses pair healthy leverage with robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com