


- Aon appointed Michael J. Sicard as Global President and CEO of Middle-Market and James Wong as head of Risk Capital Advisory for APAC, and worked with Blackstone to launch Cortina syndicate 1956 at Lloyd's to offer multi-year reinsurance capacity.
- The combination of fresh leadership in middle market and APAC risk advisory with the Cortina reinsurance platform reshapes how Aon can deploy advisory expertise, data and capital structures across its risk and capital solutions franchise.
- We will look at how Aon's investment narrative is affected by the Cortina multi year reinsurance launch with Blackstone and new leadership.
Scan how Aon’s leadership and reinsurance moves compare with other potential compounders by checking our curated list of 18 high quality undiscovered gems across the broader market.
Aon Investment Narrative Recap
To own Aon, you need to believe the middle market and capital solutions buildout can offset near term earnings dilution from the USI deal and higher leverage. The analyst consensus Narrative on Simply Wall St leans on integration and execution in U.S. commercial P&C, E&S and specialty as the key drivers. The recent Cortina launch and leadership changes do not fundamentally alter that core bet.
The more immediate swing factor still looks like how quickly USI synergies and revenue dis synergies settle, while buybacks remain constrained. The biggest risk is that integration drag, higher debt and softer organic growth keep pressure on reported EPS, even if the broader Aon platform adds useful capabilities in reinsurance and APAC advisory.
The most relevant recent move for this story is Michael J. Sicard taking on the Global President and CEO of Middle Market role. Bringing in an operator with long experience at USI lines up directly with management’s ambition to run a combined Aon, NFP and USI platform targeting about US$6.5b of middle market revenue once everything is together.
If execution under Sicard keeps the larger middle market business on track, that supports the key catalysts analysts focus on, including the planned US$395m of USI EBITDA synergies and the expansion across E&S and Totalis Specialty. Any misstep here would feed straight into the concerns around integration risk, leverage and the timing of earnings contribution.
Aon's current analyst narrative assumes revenue growth of 9.5% a year, with earnings rising from $3.9b today to a consensus forecast of $4.1b by 2029. This implies an earnings increase of about $0.2b, on projected 2029 revenue of $23.2b and earnings of $4.1b.
Uncover why Aon's fair value indicates a 9% potential upside to its current price that may not last much longer.
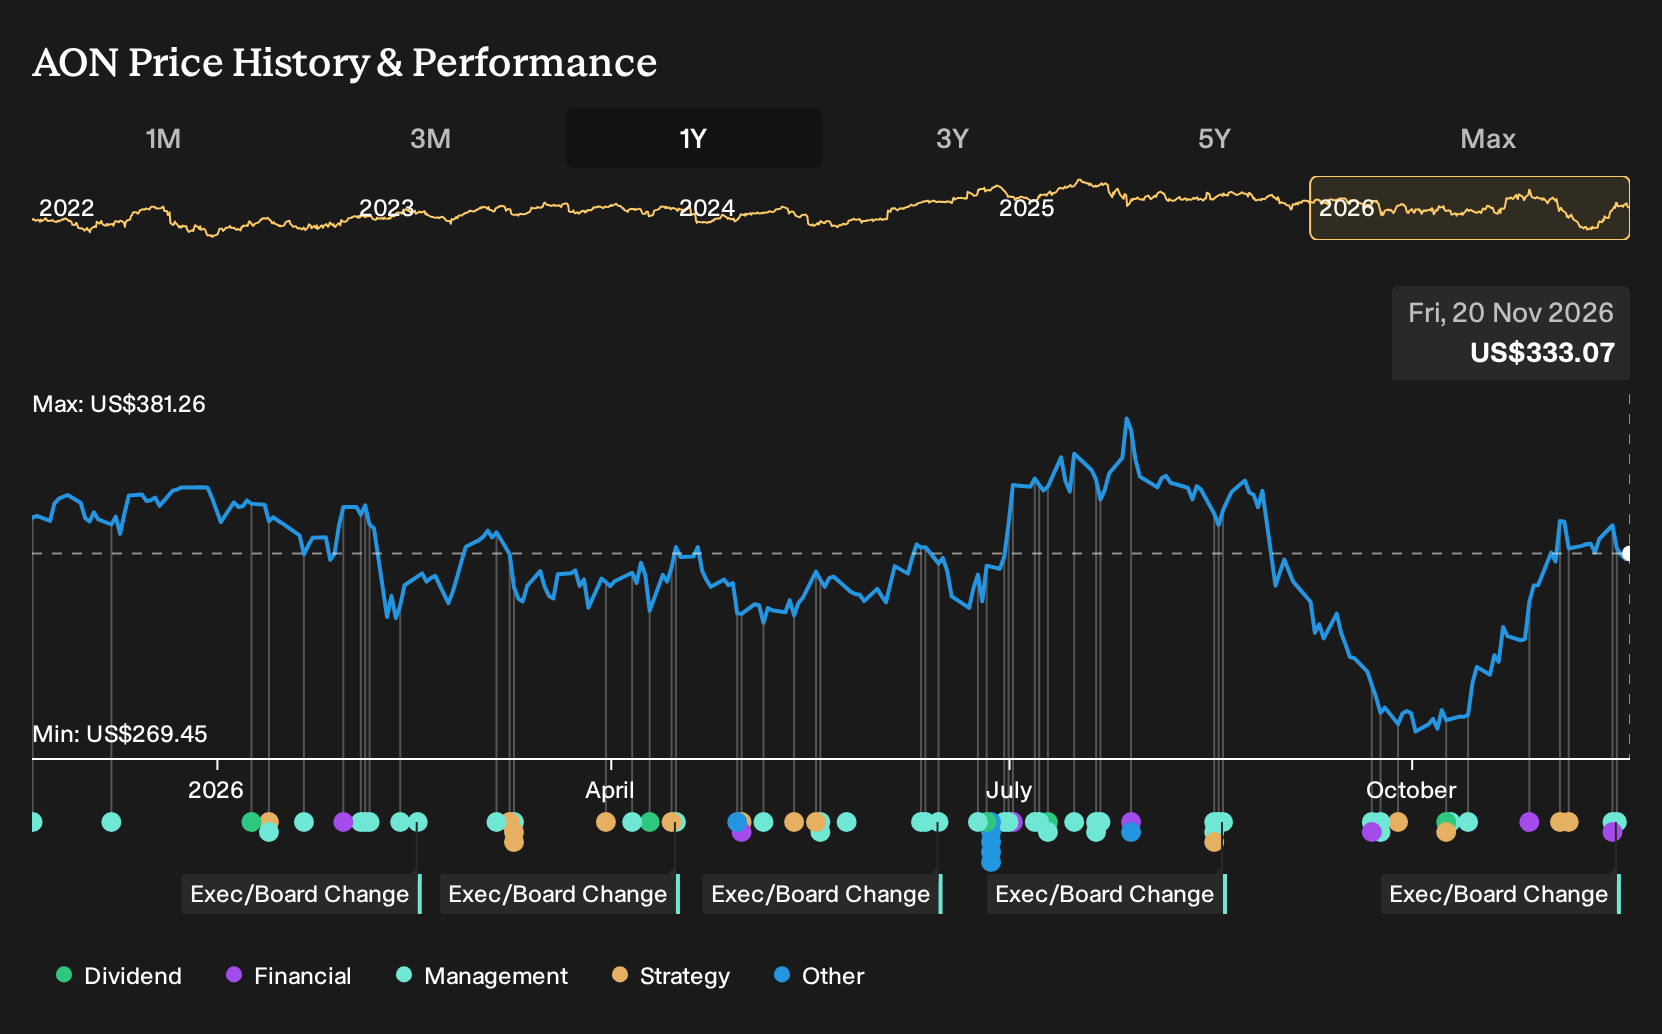
Exploring Other Perspectives
One alternative view puts Aon’s revenue potential at US$25.3b and still only US$4.1b of earnings by 2029, with a rich 27.3x P/E multiple, which is more optimistic than consensus. You might see the Cortina launch plus the Sicard and Wong appointments as reasons that story gains traction, or as assumptions worth stress testing. Investor opinions differ widely. Use this news as a prompt to compare several narratives before deciding what feels reasonable to you.
Explore another Aon fair value estimate, including one that suggests as much as 29% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own judgment carefully.
- A great starting point for your Aon research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Aon. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aon's overall financial health at a glance.
Looking For More Investment Ideas Beyond Aon?
Aon may sit at the center of this story, but your portfolio does not have to rely on a single business. The Simply Wall St Screener can help you scan for other companies that fit the mix of quality, income and resilience you want.
- If you want resilient balance sheets and clean fundamentals to anchor your holdings, start by reviewing our list of solid balance sheet and fundamentals (24 results).
- For investors who care most about getting paid to wait, focus on companies in our curated set of 8 dividend fortresses and see which high yielders meet your income goals.
- If capital preservation matters more than chasing every upside swing, narrow your watchlist using our collection of 32 resilient stocks with low risk scores that score well on downside risk.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com